



Solvent-based Organoclay Market: Why Asia Pacific's 308.8M Lead Matters

Global Solvent-based Organoclay Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The worldwide solvent-based organoclay market has demonstrated steady expansion over the past half-decade, moving from a valuation of approximately 595.2 million USD in 2020 to an estimated 737.56 million USD in 2025. The trajectory reflects a compound annual growth rate of 4.75 percent between 2026 and 2032, with revenue projected to surpass 1 billion USD by the end of the forecast window. This growth is not merely a function of incremental demand but rather the result of sustained industrial reliance on rheology control in non-aqueous systems. Organophilic clays remain indispensable for managing viscosity, suspension stability, and anti-settling behavior across formulations where water cannot be used as a carrier medium.
Despite the favorable top-line outlook, the industry operates against a backdrop of structural friction. One critical challenge lies in raw material dependency and price volatility. Solvent-based organoclay is produced by modifying montmorillonite, typically sourced from bentonite deposits, with quaternary ammonium salts to render the clay organophilic. The performance and cost profile of the final additive are tightly coupled to the purity of the starting mineral and the chemistry of the surface treatment. Producers operating without vertically integrated supply chains face margin pressure when clay sourcing costs fluctuate or when regulatory-compliant amine chemistries become more expensive. Pricing indications for rheological additives in this category have historically ranged between 1,600 and 2,700 USD per metric ton FOB, depending on grade granularity and polarity optimization, making cost predictability a persistent concern for downstream formulators.
A second inflection point involves the regulatory environment. Organoclay grades must align with REACH directives and EPA guidelines, which has accelerated product development toward optimized alkyl quaternary ammonium surface treatments that improve dispersion while maintaining compliance within solvent systems. The regulatory trajectory is not a barrier per se, but it imposes a higher bar for formulation validation, product stewardship documentation, and continuous reformulation to keep pace with evolving chemical restrictions. Suppliers that treat compliance as an afterthought risk losing procurement preference in markets where environmental and safety disclosures carry increasing weight.
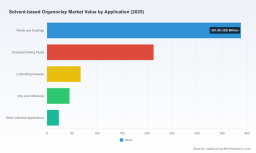
A third challenge is the uneven pace of demand growth across end-use verticals. While paints and coatings, oil-based drilling fluids, lubricating greases, inks and adhesives, and other industrial applications all consume solvent-based organoclay, their growth dynamics differ substantially. Volume expansion in coatings and inks is tied to regional industrialization, construction activity, and packaging trends, whereas drilling fluid demand is more sensitive to upstream oil and gas capital expenditure cycles. This divergence forces suppliers to manage multiple demand rhythms simultaneously and to avoid overconcentration in any single application segment that could be vulnerable to cyclical downturns.
Hectorite Clays Market
For business leaders, the implication is clear. The solvent-based organoclay market is large enough to support profitable participation, but success depends on navigating raw material exposure, regulatory compliance, and application-specific demand variability rather than simply selling a commodity thickener.
Key Demand Drivers and Structural Shifts
Innovation in Product Chemistry and Dispersion Performance
The most visible driver of market evolution is continued advancement in product chemistry. Manufacturers are engineering organoclay grades optimized for low, medium, and high polarity solvent systems, allowing formulators to achieve thixotropic and anti-settling performance with reduced additive loading or fewer secondary rheology modifiers. Easy-dispersible grades have gained commercial prominence because they reduce mixing energy, shorten dispersion time, and lower the risk of agglomeration in high-speed coating production or ink manufacturing. Conventional pre-gel grades remain relevant for applications requiring higher viscosity build-up or specific gel structures, particularly in lubricating greases and certain oil-based drilling fluids. The shift toward grades that perform reliably across a broader polarity range helps formulators simplify supply chains while maintaining performance consistency.
Montmorillonite Clay (Bentonites) Market
Regulatory and Compliance Pressures Shaping Product Design
Regulatory expectations are acting as a design constraint and an opportunity in equal measure. Compliance with REACH and EPA frameworks has pushed producers to refine alkyl quaternary ammonium surface treatments, aiming for formulations that deliver the desired rheological response while minimizing handling concerns and supporting downstream customer documentation requirements. This dynamic favors suppliers that can articulate clear compliance positioning, provide consistent batch-to-batch quality, and support customers with technical data that eases integration into regulated formulations. In practical terms, compliance has become a competitive differentiator rather than a baseline requirement, especially in European and North American applications where procurement teams scrutinize chemical documentation before qualification.
Demand-Side Behavior and Application Broadening
Demand behavior is being reshaped by end-user preference for high-performance, low-maintenance formulations. In paints and coatings, manufacturers increasingly seek rheology additives that support sag resistance, pigment suspension, and shelf stability without compromising application properties. In inks and adhesives, dispersion efficiency and gloss retention are primary considerations. In lubricating greases, organoclays contribute to structure stability and resistance to softening under shear. In oil-based drilling fluids, effective rheology control is essential for carrying cuttings and maintaining wellbore stability. Across these applications, the common theme is a willingness to pay for performance predictability and processing efficiency. This creates room for suppliers offering tailored grades, application-specific technical support, and consistent availability, especially where procurement teams are trying to reduce variation in final product quality.
Supply Chain Configuration and Cost Structure
Cost structure and supply chain configuration are increasingly decisive. Organoclay manufacturing relies on high-purity montmorillonite from dedicated bentonite mines, and producers that control both mineral sourcing and chemical modification gain leverage in cost management, quality control, and supply assurance. Vertical integration helps reduce dependency on external clay suppliers, improves the consistency of the base mineral, and supports a more stable cost base for finished grades. At the same time, logistics, energy costs, and chemical input pricing influence the landed cost of organoclays in different regions. Buyers are therefore paying closer attention to total cost of ownership, not just unit price, because dispersion efficiency, dosage optimization, and performance reliability can offset apparent price differences between suppliers. In a market where pricing spans a meaningful range by grade and polarity optimization, the commercial winner is often the supplier that can demonstrate the best balance between cost, performance, and supply reliability.
Taken together, these drivers suggest that the market is moving away from undifferentiated product sales toward value-added solutions. Formulators are looking for partners who can help them meet performance targets, manage compliance, and stabilize input costs, while suppliers are investing in grade optimization, application support, and supply chain resilience to capture that preference.
Competitive Landscape and Strategic Positioning
The competitive field in solvent-based organoclay includes a mix of established specialty players and regional manufacturers with strong bentonite access. Elementis plc, with its BENTONE series, is recognized for solvent-based organoclay rheological additives including hectorite and bentonite-based grades such as BENTONE 34 and 38. Its positioning emphasizes thixotropic and anti-settling performance for coatings, greases, and industrial applications, supported by a global specialties footprint that spans operations in Europe and the United States. This global reach gives Elementis an advantage in multi-region customer support and technical service, particularly where formulators require consistent performance across markets and regulatory contexts.
Bentonite Performance Minerals operates with a strong focus on vertically integrated production of organically modified bentonite, primarily for oil and gas drilling fluids. Its product range includes powder and granular forms using quaternary amine chemistry designed to address contaminant targeting and rheology control in demanding drilling environments. This application-centric specialization allows BPM to build deep domain expertise and long-term supplier relationships in drilling fluid formulation, where performance under downhole conditions and resistance to electrolyte contamination are critical.
Minerals Technologies Inc. contributes a global perspective as a provider of organoclay rheological additives and specialty minerals for solvent-based systems in paints, coatings, and industrial applications. Its scale and breadth of mineral expertise enable it to serve a wide range of formulators and to maintain supply consistency across major end-use markets. The company’s positioning benefits from its ability to combine mineral sourcing capability with additive product knowledge, which supports both performance and supply assurance for large-volume industrial customers.
A notable cluster of competitive activity sits in Asia, where manufacturers have expanded capacity, emphasized vertical integration, and built export-oriented supply chains. Zhejiang Camp Shinning New Material Co., Ltd. is a leading manufacturer specializing in solvent-based organoclay rheological additives for paints, coatings, inks, grease, and oil drilling fluids. Its product strategy centers on multiple grades optimized for low, medium, and high polarity solvent systems, supported by ownership of its own bentonite mine and ISO certification. This combination of mine-to-finished-product control and grade customization supports cost competitiveness and quality consistency. Hangzhou Jingyi Chemical Co., Ltd., part of a large Asian organoclay manufacturing group with operations dating back to 1984, is another major producer of rheological additives for solvent-based systems. Its annual capacity supports paints, inks, sealants, and lubricants, and its long operating history contributes to established production know-how and export experience.
Indian manufacturers such as Suraiya Private Limited and Bentec Organoclays have carved out roles as experienced producers and exporters of solvent-borne organoclays and rheological additives. Suraiya positions its Smectone organoclays as import substitutes for thickening, gelling, and anti-settling in solvent-based systems, oils, and organic liquids, appealing to formulators looking to diversify supply sources or reduce import dependence. Bentec Organoclays offers various grades of rheological additive organoclays for industrial applications including solvent-based formulations, supporting regional demand and export channels. Weifang Huawei Bentonite Group, another China-based producer, serves rheological needs in solvent-based coatings, drilling, and related sectors, contributing to the broader supply base that continues to expand across Asia.
PW Consulting
The market structure reflects meaningful concentration, with the top three firms holding roughly 48.5 percent and the top five firms holding about 62.3 percent of market share. This concentration indicates that established players retain substantial influence, but it also leaves room for regional specialists and niche manufacturers to compete on grade customization, pricing, and application support. The competitive trend is not purely consolidation or fragmentation; it is a blend of both. Larger players strengthen their position through product breadth, global service networks, and compliance credentials, while regional manufacturers compete by offering tailored grades, responsive technical service, and vertically integrated cost advantages. New entrants and expanding regional suppliers add pressure on pricing and availability, which benefits buyers but raises the bar for differentiation among incumbents.
For strategic planners, the key insight is that supplier selection increasingly hinges on more than price. Performance reliability across polarity ranges, compliance documentation, supply continuity, and application-specific technical support are becoming the decisive variables. Companies that treat organoclay procurement as a pure commodity purchase risk exposing their formulations to variability, while those that engage with suppliers around grade optimization and supply strategy can convert rheological performance into tangible processing and quality advantages.
Future Outlook: Trends Shaping the Next Three to Five Years
Looking ahead, one dominant trend is the continued emphasis on easy-dispersible and polarity-flexible grades. As coating and ink producers seek to reduce processing time, limit agglomeration risk, and simplify formulation architecture, organoclay products that disperse quickly and deliver consistent rheology across a wider solvent spectrum will likely capture additional preference. This creates an opportunity for suppliers that can demonstrate measurable dispersion improvements, lower shear requirements, and stable performance in solvent systems with varying polarity. It also raises expectations for technical support, because formulation gains depend on matching grade selection to specific solvent and pigment/polymer systems rather than using a generic thickener.
A second trend is the tightening alignment between product chemistry and regulatory readiness. As compliance expectations become more embedded in procurement decisions, organoclay grades with cleaner documentation, optimized surface treatments, and consistent batch quality will gain an edge. Suppliers that proactively support customer compliance requirements may see preferential qualification in European and North American accounts, while those with less transparent product stewardship could face longer qualification cycles or displacement by alternatives that reduce regulatory friction. This trend favors organizations that can integrate regulatory readiness into product development rather than treating it as a separate administrative task.
A third trend concerns supply chain localization and diversification. Demand growth in Asia Pacific is significant, and regional production capacity continues to expand, supported by bentonite access and export-oriented manufacturing. At the same time, buyers in other regions are increasingly interested in supply diversification to reduce dependency on single-source suppliers and to improve resilience against logistics disruptions. The combination of regional capacity growth and buyer appetite for alternative sourcing creates an environment where both incumbents and expanding regional players can gain ground if they can deliver consistent quality and dependable lead times.
These trends intersect with commercial opportunity, but they also carry uncertainty. Oil and gas capital expenditure cycles can affect drilling fluid demand, regulatory interpretations can shift product qualification requirements, and raw material availability can alter cost structures. In addition, the market may see substitution pressure in specific applications if alternative rheology technologies improve their performance or cost position. Participants should therefore treat growth as attainable but conditional on product relevance, supply reliability, and the ability to respond to changing compliance and application requirements.
Strategic Implications for Decision Makers
Manufacturers and formulators should treat organoclay selection as a performance-and-risk decision rather than a price-only purchase. Prioritizing grades that match the polarity profile and processing conditions of the target system can improve dispersion, reduce additive loading, and stabilize final product quality. Where possible, qualification programs should include dispersion efficiency, sag resistance, shelf-life behavior, and compliance documentation, not just viscosity build-up. Building relationships with suppliers that can offer multiple grades and application-specific guidance can reduce formulation risk and shorten troubleshooting cycles when solvent systems or raw material inputs change.
Investors evaluating exposure to this market should focus on structural advantages that support durable margins. Vertical integration from bentonite sourcing to finished organoclay production, broad grade coverage across polarity ranges, and a credible compliance narrative are indicators of competitive resilience. It is also important to assess exposure to cyclical end-use segments such as drilling fluids alongside steadier demand in coatings, inks, and greases, because segment mix influences revenue stability. Companies that can combine cost control, product differentiation, and multi-region supply capability are better positioned to navigate both demand growth and competitive pressure.
Procurement and supply chain leaders should seek to lower total cost by balancing price with performance reliability and supply assurance. Multi-supplier qualification can provide leverage and contingency, but it should be paired with clear technical criteria so that alternative grades do not introduce variability in application behavior. Where regional supply diversification is feasible, it can reduce exposure to logistics shocks and import dependency, provided consistent quality and documentation are maintained.
For organizations that need deeper segmentation, pricing nuance, and tailored recommendations across regions and applications, a full market study can provide the granularity required to convert these trends into concrete commercial decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Solvent-based Organoclay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


