



Worldwide Indian Curry Paste Market: Why 6.85% CAGR Dynamics Reshape Growth

Navigating the Global Indian Curry Paste Market: Strategic Insights for Decision-Makers
Market Snapshot and Critical Crossroads
The worldwide Indian curry paste market has evolved from a niche ethnic food segment into a structured global consumer category, driven by sustained demand for convenient, authentic Indian flavors. Measured in USD millions, the market has demonstrated consistent expansion over the past half-decade, with a clear upward trajectory extending through the forecast horizon. Base-year positioning reflects a mature but still-growing revenue base, and the projected compound annual growth rate of 6.85% signals durable momentum rather than a temporary consumption spike. This growth profile is notable because it persists across economic cycles and geographic regions, indicating that Indian curry pastes are transitioning from discretionary gourmet purchases to routine pantry staples in multiple consumer markets.
At a strategic level, the market is defined by concentrated leadership alongside broad fragmentation in specialty and regional niches. A relatively small group of established players commands a meaningful share of total revenue, while a long tail of regional manufacturers, diaspora-focused brands, and private-label operations competes on authenticity, price, or distribution access. This structure matters for decision-makers because it shapes negotiation dynamics with suppliers, influences shelf-space competition, and determines how quickly new entrants can scale. The presence of strong incumbents with established foodservice and retail relationships raises the barrier to entry for pure-play startups, but it also creates clear acquisition and partnership pathways for companies seeking faster market access.
PW Consulting
Several structural challenges now define the industry's next phase. First, quality assurance and food safety risk have moved to the forefront following recent product recall events involving potential foreign-material contamination in widely distributed curry paste lots. These incidents highlight the operational complexity of scaling production across multiple facilities, maintaining consistent metal-detection and sieving controls, and managing lot traceability across long supply chains. For buyers and brand owners, the implication is clear: safety and quality credentials are no longer a baseline expectation but a competitive differentiator that affects retailer trust, import clearance speed, and consumer repurchase behavior.
Second, input cost volatility is reshaping margin planning. Key spices, particularly turmeric and allied ingredients used in curry paste formulations, have experienced significant price swings tied to production conditions, export dynamics, and seasonal availability. This volatility complicates recipe cost modeling, inventory timing, and long-term pricing commitments. Companies that rely on fixed-price contracts or single-origin sourcing are especially exposed, while those with diversified sourcing strategies and flexible procurement frameworks are better positioned to protect profitability without alienating price-sensitive consumers.
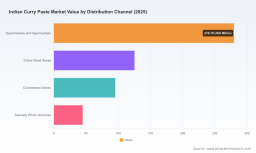
Third, distribution pathways are fragmenting more rapidly than many traditional manufacturers anticipated. Consumers increasingly blend offline grocery trips with online replenishment, while foodservice operators balance consistency, labor savings, and menu differentiation. This dual-channel reality requires brands to maintain distinct packaging, format, and communication strategies for retail shelves and professional kitchen environments, rather than assuming a single go-to-market approach will carry both segments efficiently.
Key Drivers Powering Market Change
Technology and formulation innovation are reshaping what curry paste can be and how quickly it can reach diverse consumers. Advances in spice blending, moisture management, and preservation techniques allow manufacturers to deliver consistent flavor profiles across larger batches while supporting cleaner ingredient narratives. This matters because global consumers and foodservice chefs are increasingly seeking products that combine authentic taste with predictable performance, longer shelf stability, and reduced reliance on artificial additives. Companies investing in process control and sensory consistency are gaining an advantage in both retail and HoReCa channels, where repeat usage depends on dependable results during preparation.
Regulatory and compliance conditions are also becoming a more active force in market expansion. Cross-border trade in value-added spice products now intersects with stricter food safety oversight, import documentation expectations, and recall-management requirements. Recent enforcement actions have underscored how quickly a single quality issue can affect multi-state distribution and brand reputation. At the same time, regulatory alignment and clearer compliance pathways can unlock faster market entry for exporters who invest early in documentation, testing, and traceability. The companies most effectively navigating this environment treat compliance as part of their product architecture rather than a back-office checkpoint.
On the demand side, consumer and operator behavior is shifting toward convenience without sacrificing perceived authenticity. In household and retail settings, shoppers want ready-to-use curry pastes that reduce prep time while still feeling rooted in recognizable Indian flavor traditions. In foodservice and HoReCa environments, operators value paste-based solutions that standardize seasoning, reduce variability across kitchen shifts, and support menu innovation with lower labor intensity. This demand pattern is expanding the addressable market beyond traditional ethnic grocery shoppers and into mainstream retail shelves, convenience channels, and international casual dining formats.
Supply chain and cost structure dynamics are reinforcing the urgency of strategic sourcing. India continues to play a central role as both an ingredient source and an export hub for spice-based prepared products, and the broader export momentum of value-added spice offerings reflects the growing global appetite for Indian culinary inputs. However, raw-material price movement remains sensitive to seasonal production shifts and broader agricultural conditions. Turmeric, in particular, has shown significant price variability, which directly affects formulation economics for many curry paste categories. Firms that manage this risk through forward contracting, blended sourcing, and ingredient substitution flexibility are better equipped to maintain pricing stability and protect consumer value perception.
These drivers interact with one another. Innovation makes it easier to meet consumer expectations; regulatory readiness determines whether those products can move across borders efficiently; demand growth pulls volume through retail and foodservice channels; and sourcing discipline governs whether margin can be sustained during periods of input-price stress. For strategists, the practical takeaway is that success in this market increasingly depends on connecting product development, compliance, and procurement in a single operating logic rather than managing them in isolation.
Competitive Landscape and Leading Strategies
The competitive field combines globally active brands with strong Indian manufacturing footprints and regional successors that have built distribution through ethnic grocery networks and export channels. Companies such as Patak's have long anchored their positioning around a broad portfolio of familiar curry paste and sauce varieties, appealing to both retail consumers and foodservice users who want consistent, recognizable flavor families. Other established manufacturers, including MTR Foods, Haldiram's, Dabur India, Tasty Bite Eatables, Kitchens of India, ITC Limited, and Priya Foods, leverage deep domestic production capabilities, brand recognition in India, and growing international distribution to compete across packaged curry paste and related meal solutions.
Pasta Sauce Market
In North America and similar export markets, Indian-origin brands such as Rani Brand and Sukhi's Gourmet Indian Foods have built presence by focusing on convenience formats and direct access to ethnic retail shelves. Specialty manufacturers like Aachi Masala and Desai Foods, along with export-oriented suppliers such as G.A. Foods India, reflect the broader reality that many players compete not by national scale alone but by category focus, regional recipe strength, and channel-specific relationships. This mix creates a market where leadership is measured not just by volume but by the ability to maintain flavor authenticity, shelf availability, and trust across multiple geographic and channel contexts.
Several recent developments illustrate how competitive strategy is evolving. A partnership between Dabur India and Grace Foods for co-development and distribution of Indian curry pastes in North America and the Caribbean signals a growing preference for collaboration over standalone expansion when entering complex Western retail environments. Co-development can accelerate localization, improve format fit for regional taste expectations, and share the commercial risk of new market entry. At the same time, Kitchens of India's introduction of a premium chef-inspired curry paste range shows that there is still room for differentiation through higher-tier positioning, especially where consumers and operators are willing to pay for perceived culinary craftsmanship.
The market is also being shaped by quality and compliance events. A voluntary Class II recall involving Sukhi's Classic Curry Paste and related sauces, triggered by potential metal fragment contamination and affecting multiple lots distributed across numerous U.S. states, serves as a practical reminder that scale, availability, and flavor alone do not protect a brand if quality control fails. For competitors, this reinforces the value of transparent safety processes, robust lot control, and proactive retailer communication. For buyers, it highlights the importance of supplier due diligence that goes beyond price and extends into quality systems, testing frequency, and incident responsiveness.
Looking at market structure, the landscape appears to be moving toward selective consolidation at the top while remaining highly fragmented in specialty segments. Larger players are expanding portfolios, strengthening export logistics, and using partnerships to gain faster access to new channels. Smaller manufacturers continue to thrive by focusing on regional authenticity, niche flavor varieties, and strong relationships with ethnic grocers and diaspora communities. New entrants face a realistic challenge: they must either bring a clearly differentiated product story, such as clean-label positioning, chef-driven formulation, or innovative packaging, or secure distribution through acquisition, licensing, or partnership rather than attempting to compete broadly from launch.
Forward Outlook: Where the Market Is Heading
One clear direction for the next three to five years is the continued mainstreaming of Indian curry paste in non-ethnic retail and foodservice channels. As consumers become more familiar with Indian flavor profiles and operators seek efficient ways to expand global menu offerings, curry paste is likely to gain shelf space beyond specialty groceries. This broadening creates opportunities for brands that can translate authentic flavor into formats suited to mainstream packaging, labeling, and consumption habits while preserving taste credibility.
A second trend will be greater emphasis on formulation transparency and safety assurance as competitive levers. In the wake of recent recall activity and heightened consumer scrutiny, brands that can demonstrate disciplined quality control, traceable sourcing, and consistent production standards will be better positioned to secure retail listings, maintain import momentum, and build repeat usage. This is likely to elevate safety and documentation from operational hygiene to a visible brand asset.
A third trend is the growing importance of channel-specific product architecture. Retail consumers and professional kitchens increasingly demand different value propositions: convenience, portion size, and shelf visibility in retail; batch consistency, speed, and integration into prep workflows in foodservice. Companies that design separate go-to-market strategies for these segments, rather than treating the market as uniform, will be better able to capture value across both worlds.
These trends carry opportunity, but also risk. Raw-material price volatility may pressure margins if sourcing strategies remain rigid. Regulatory scrutiny may slow market entry for companies without mature compliance frameworks. And brand trust can erode quickly if quality incidents are not managed decisively. The most resilient strategies will treat flexibility, compliance readiness, and consumer trust as core strategic assets rather than operational afterthoughts.
Decision-Maker Actions for the Next Planning Cycle
For manufacturers and brand owners, the priority is to align product development with channel reality and sourcing resilience. That means building distinct retail and foodservice offerings, reinforcing quality and traceability systems, and creating procurement flexibility around key ingredients so that price swings do not force reactive pricing decisions. Partnerships should be evaluated not only for immediate distribution access but also for their ability to improve localization, compliance readiness, and long-term brand credibility in target markets.
For investors, due diligence should focus on the durability of a company's distribution relationships, the strength of its quality infrastructure, and its exposure to input-cost volatility. Market growth is attractive, but revenue expansion is most valuable when supported by repeatable quality, defensible channel access, and the ability to manage recall or compliance risk without major brand damage. Companies with clear differentiation and disciplined operational controls are better positioned to convert market growth into sustainable returns.
For procurement teams and retail or foodservice buyers, supplier selection should extend beyond unit price to include safety systems, lot traceability, recall responsiveness, and flexibility during raw-material volatility. A supplier that can demonstrate consistent quality and adaptive sourcing will likely create fewer downstream disruptions and support more stable cost planning over time. In a market where trust and consistency drive repeat usage, procurement decisions increasingly influence brand performance as much as product features do.
Copper Paste Market
For decision-makers who need a deeper, segment-level view of revenue splits, regional dynamics, distribution-channel behavior, and competitive positioning, the full PW Consulting market analysis provides more granular data and tailored scenario support. The detailed study is designed to help teams move from market awareness to specific planning decisions with clearer visibility into where volume, margin, and risk are most likely to concentrate in the years ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Indian Curry Paste Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


