



5 Forces Driving the Clinching Machines Market’s USD 2.23B 2032 Surge

Strategic Shifts and Commercial Opportunities in the Global Clinching Machines Market: A 2025 Outlook
Market Snapshot and Critical Inflection Points
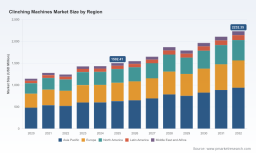
The global market for clinching machines has demonstrated robust momentum over the past half-decade, transitioning from a niche mechanical joining solution to a strategically relevant alternative in sheet metal assembly. Valued at approximately USD 1,145.2 million in 2020, the sector expanded to an estimated USD 1,502.41 million by 2025, reflecting sustained demand across heavy industrial and precision manufacturing verticals. Forward-looking projections indicate the revenue base will reach USD 2,232.35 million by 2032, supported by a compound annual growth rate of 5.82 percent through the forecast period. This trajectory underscores a market that is no longer defined solely by traditional fabricators but is increasingly embedded in high-volume, automation-driven production ecosystems.
Despite the positive growth narrative, operators and investors must navigate three structural challenges that are reshaping competitive dynamics. First, the shift toward lighter-weight materials and dissimilar material combinations—such as aluminum-to-steel or coated composite hybrids—places tighter tolerances on tool design and joint integrity, forcing manufacturers to balance cold-forming precision with cycle time efficiency. Second, capital expenditure sensitivity in cyclically exposed sectors like construction and general engineering creates demand volatility, compelling suppliers to offer more flexible fleet configurations, modular tooling, and service-oriented pricing models. Third, the growing expectation for seamless integration with automated work cells raises the technical barrier to entry; standalone manual or semi-automated units face margin pressure as end-users prioritize robotic compatibility, electrical efficiency, and consistent repeatability over simple equipment acquisition.
These inflection points are not deterrents but signals of market maturation. Companies that treat clinching as a standalone hardware transaction are losing ground to those positioning it as part of a broader process solution encompassing tooling management, integration architecture, and operational performance guarantees.
Core Demand Drivers Reshaping the Landscape
Several converging forces are accelerating adoption and redefining value creation within the clinching ecosystem. Technical innovation stands at the forefront, with servo-driven electric presses and precision-controlled punch-die geometries enabling cold-forming joints to be completed in milliseconds while maintaining fatigue resistance and airtight seals. The mechanical process eliminates the need for supplementary fasteners or adhesives, reducing material overhead and simplifying downstream disassembly or recycling workflows. Concurrently, electrical and hybrid press architectures are gaining traction as manufacturers seek to lower energy intensity relative to thermal joining alternatives, aligning equipment specifications with corporate sustainability mandates and total cost of ownership frameworks.
Regulatory and policy environments are exerting a quieter but equally powerful influence. Environmental compliance expectations around emissions, energy consumption, and circular material usage are pushing assembly lines toward low-heat, fastener-free joining methods. In sectors where structural safety standards intersect with material efficiency targets, clinching offers a viable pathway to join multi-layer sheets and dissimilar alloys without introducing thermal distortion or chemical residues. This regulatory tailwind is particularly visible in automotive lightweighting programs and appliance manufacturing, where weight reduction and component consistency are tied directly to performance certifications and consumer expectations.
Demand-side behavior is shifting as well. Original equipment manufacturers and tier suppliers are increasingly prioritizing process standardization and line simplification. The elimination of fastener inventory, reduced tooling changeover complexity, and the ability to maintain consistent joint quality across coated and galvanized substrates are driving procurement decisions toward integrated clinching solutions. Moreover, labor constraints in several industrial markets are accelerating interest in automated work cells, where robotic handling and servo-controlled actuation reduce dependency on skilled manual operators while improving throughput consistency.
Cold Heading Machine Market
On the supply side, cost structure dynamics are evolving. Tooling longevity, maintenance predictability, and modular machine configurations are becoming as commercially significant as base equipment pricing. Suppliers that provide clear lifecycle costing, standardized replacement tooling, and rapid service response are differentiating themselves in a competitive landscape where initial sticker price is no longer the decisive factor. Recent corporate communications from established players highlight this strategic emphasis: one veteran manufacturer refreshed its catalog and digital presence in late 2025 to reinforce its flagship machine families and underscore three decades of field validation for global sheet metal fabricators. Another automated assembly specialist announced preparations for a major industry exhibition in late 2025, signaling its intent to showcase integrated clinching modules within broader automation platforms. These moves reflect a broader industry pivot from equipment-only selling to solution-level engagement.
PW Consulting
Competitive Positioning and Evolving Dynamics
The competitive field is anchored by a mix of technology originators, specialized machine builders, and automation integrators. In Europe, firms with deep press and cold-forming heritage have built strong positions around proprietary joint geometries and modular press platforms, offering pneumatic, hydraulic, and electric variants tailored to steel, stainless, aluminum, and multi-layer assemblies. Their differentiation rests on process reliability, broad material compatibility, and extensive application engineering support across automotive, railway, energy, and appliance segments. In North America, a leading clinching technology provider has historically shaped the market through its patented sealed clinch system and comprehensive portfolio spanning manual, automated, and robotic equipment, positioning itself as a reference point for joint integrity and full-line integration. Canadian and U.S.-based specialists contribute niche strength in precision machines for HVAC, roofing, architectural, and pool applications, competing on ease of use, fast no-heat joining, and targeted industry fit.
In Asia and emerging industrial corridors, manufacturers are expanding capacity and targeting high-volume automotive, electronics, and appliance production with performance-oriented machines designed for throughput and material versatility. Meanwhile, system integrators and tooling specialists are increasingly partnering with press manufacturers to deliver turnkey assembly cells, combining clinching modules with robotic handling and line synchronization. This division of labor reflects a market that is stratifying along two axes: core press and tooling expertise on one side, and automated integration and application engineering on the other.
Several strategic patterns define the current landscape. First, differentiation is shifting from machine specifications alone to ecosystem value: joint consistency across material grades, compatibility with robotic work cells, energy-efficient actuation, and modular scalability. Second, concentration among top players remains moderate, with leading firms commanding a combined share that signals room for specialist entrants and regional champions, but also creates pressure on smaller assemblers to articulate clear technical or service advantages. Third, the market is experiencing both consolidation tendencies and fragmentation in niches. Larger groups pursue broader application coverage and integrated automation platforms, while focused manufacturers retain advantage in specialized industries or regional service networks. New entrants are most likely to succeed by targeting underserved material combinations, lightweighting requirements, or compact automation footprints rather than competing head-on in mature general-purpose segments.
For decision-makers evaluating suppliers, the practical implication is straightforward: assess not only the press family and tooling range but also the provider's integration track record, service response model, and ability to support material transitions without requalifying entire production lines. In a market where process reliability and line flexibility increasingly outweigh hardware novelty, the strongest positions belong to organizations that can demonstrate repeatable performance across diverse assemblies and adapt quickly to changing material and automation requirements.
Linear Friction Welding Machines Market
Forward Outlook: Trends and Commercial Implications (2026–2032)
Looking ahead, three trends are likely to shape commercial outcomes over the next three to five years. The first is the deepening integration of clinching into robotic and servo-controlled work cells. As assembly strategies prioritize precision, repeatability, and reduced energy intensity, electromechanical drives and automated cell architectures will become standard in high-volume automotive and appliance production. This trend expands the addressable market for robotic clinching systems and creates secondary demand for compatible end-of-arm tooling, cell synchronization software, and service agreements that maintain uptime and joint quality.
The second trend is material diversification and the rise of dissimilar and coated substrate joining. Lightweighting mandates, corrosion-resistant specifications, and multi-material component designs will require tools and press parameters that accommodate aluminum, galvanized, stainless, and coated steels without compromising joint integrity. Suppliers that invest in adaptive tooling, flexible punch-die configurations, and validated process windows for mixed-material assemblies will capture premium positioning and longer-term customer stickiness. This also creates an opportunity for application-led sales models, where joint qualification support and material testing become part of the commercial package rather than afterthoughts.
The third trend is the growing emphasis on total cost of ownership and lifecycle performance. As buyers compare clinching against alternative joining methods, the evaluation criteria are expanding beyond cycle time to include energy consumption, fastener and adhesive elimination, tooling replacement cadence, and maintenance predictability. Companies that can quantify operational savings, reduce consumable dependency, and offer modular upgrades will be better positioned to defend margins and compete against both thermal processes and lower-cost equipment imports. At the same time, uncertainty remains around macroeconomic cycles in construction and general engineering, potential volatility in coated and aluminum supply, and the risk that a subset of smaller fabricators may delay automation investments during periods of capital constraints. These factors suggest that growth will be durable but uneven, with leading positions accruing to organizations that can align product flexibility with customer financing and service models.
Strategic Recommendations for Decision-Makers
For manufacturers and production leaders, the priority is to align joining technology selection with long-term material and automation roadmaps rather than short-term equipment cost. Investing in clinching solutions that support dissimilar materials, robotic integration, and modular tooling can reduce line complexity and future-proof assembly processes against lightweighting and compliance shifts. Process validation, operator training, and service availability should be evaluated with the same rigor as press specifications.
For investors and corporate development teams, attention should focus on companies that combine press expertise with integration capability, application engineering, and service-driven revenue streams. The most resilient profiles are those that can expand across multiple end-use sectors, sustain differentiation through proprietary joint designs or electric actuation platforms, and capture value beyond hardware sales through tooling, upgrades, and maintenance contracts. Monitoring regional capacity additions, partnership activity with automation integrators, and movement into underserved material or application niches can provide early signals of competitive repositioning.
For procurement and supply chain leaders, the commercial case increasingly rests on total operating impact. Evaluations should incorporate energy efficiency, fastener and adhesive elimination, changeover simplicity, and lifecycle tooling economics, alongside conventional price comparisons. Supplier selection should weigh integration readiness and responsiveness, especially where production lines are transitioning toward higher automation or mixed-material assemblies. Detailed segmentation data, company-level capability assessments, and scenario-based volume projections can sharpen these decisions and reduce implementation risk. For teams seeking a deeper dive into regional dynamics, application-specific demand patterns, and competitive positioning across machine types, a comprehensive research report offers the structured detail needed to translate these strategic directions into actionable planning.
For detailed analysis of this topic, please visit the official page: Worldwide Clinching Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


