



Worldwide Auto-fill Humidification Chamber Market: The 6.45% CAGR and Hospital Demand Shift

Global Auto-fill Humidification Chamber Market: Strategic Trends and Commercial Opportunities (2025–2032)
Market Overview and Core Challenges
The global market for auto-fill humidification chambers has entered a phase of steady, structurally driven expansion. Valued at approximately 641.93 million USD in 2025, the sector has demonstrated consistent compounding since 2020, with a long-term compound annual growth rate projected at 6.45 percent through 2032. This trajectory reflects a transition from routine respiratory support accessories to precision-engineered components that directly impact clinical outcomes, ventilation efficiency, and infection control protocols. The market's scale underscores a fundamental shift in how respiratory therapies are delivered across acute care, outpatient, and residential environments, positioning humidification hardware as a critical node in the broader respiratory care ecosystem.
Despite the favorable growth trajectory, the industry faces several structural challenges that will shape competitive positioning in the coming years. First, regulatory standardization continues to evolve across major markets. Devices intended for continuous respiratory gas humidification are classified as Class II medical devices in the United States, requiring documented 510(k) clearance before commercialization. While established manufacturers navigate this pathway efficiently, the requirement creates barriers for new entrants and mandates continuous post-market compliance across regions with differing sterilization, labeling, and clinical validation requirements. This regulatory complexity increases time-to-market for novel designs and heightens the cost of maintaining global product portfolios.
Second, the single-patient-use paradigm fundamentally shapes both procurement economics and supply chain strategy. Auto-fill humidification chambers are typically manufactured from clear polycarbonate and supplied as disposable units, often with sterile packaging options to align with hospital infection control mandates. This disposable design eliminates cross-contamination risks and reduces reprocessing overhead, but it also ties revenue streams to continuous replacement cycles. Procurement teams increasingly scrutinize per-procedure cost, sterilization logistics, and waste management implications, forcing manufacturers to balance clinical safety with economic efficiency. The tension between infection control standards and cost containment will remain a persistent pressure point, particularly in public healthcare systems and high-volume critical care networks.
Third, supply chain resilience and material sourcing present ongoing operational considerations. Polycarbonate production, precision molding, and sterile packaging rely on specialized manufacturing capabilities and consistent raw material availability. Geopolitical shifts, logistics disruptions, and fluctuations in medical-grade polymer pricing can compress margins or delay product launches. Companies that have diversified supplier bases, localized critical manufacturing steps, or invested in standardized component architectures are better positioned to absorb these shocks. Conversely, firms dependent on single-source supply chains face elevated risk exposure. These overlapping challenges define the current inflection point: growth is robust, but capturing value requires disciplined navigation of regulatory pathways, cost structures, and supply chain volatility.
Key Growth Drivers
Technological Innovation and Clinical Performance Optimization
The most significant catalyst for market expansion lies in the continuous refinement of auto-fill mechanisms and their integration with modern ventilation workflows. Leading chamber designs now employ dual-float or multi-valve architectures that regulate automatic water replenishment while preventing overfilling. These mechanisms maintain consistent compressible volume, a critical parameter for patients undergoing high-frequency ventilation, non-invasive respiratory support, or conventional mechanical ventilation. By stabilizing humidity delivery without requiring clinician intervention, these designs reduce workflow interruptions and support more predictable therapeutic outcomes. The clinical benefit is clear: stable humidity levels minimize airway drying, reduce mucus viscosity complications, and support patient comfort during extended ventilation sessions.
Recent product clearances and submissions illustrate how manufacturers are translating these engineering advances into market-ready solutions. Regulatory documentation from mid-2023 highlighted submission activity for next-generation dual-chamber systems designed to improve thermal consistency and streamline compatibility with existing heated humidifier platforms. Earlier clearances had already established pathways for auto-fill chambers integrated into non-invasive ventilation and nasal high-flow circuit kits, signaling a deliberate push toward broader clinical applicability. These filings demonstrate an industry-wide focus on reducing setup complexity while expanding the range of ventilation modes that can be supported reliably. For manufacturers, the emphasis is shifting from basic humidification functionality toward integrated performance characteristics that align with modern respiratory care bundles.
Regulatory Pathways and Compliance as Market Filters
Regulatory frameworks are simultaneously constraining and shaping market dynamics. The classification of auto-fill humidification chambers as Class II devices under respiratory gas humidifier provisions means that manufacturers must demonstrate substantial equivalence to legally marketed predicates through structured 510(k) pathways. This requirement creates a natural filter: companies with established regulatory infrastructure, active quality management systems, and experience in respiratory device submissions gain a competitive advantage. The process also encourages iterative product improvement, as design modifications often require updated testing documentation or new clearance submissions when compatibility claims or performance parameters change.
Beyond the United States, variation in regional regulatory expectations adds complexity to global commercialization. Differences in sterilization validation requirements, labeling standards, and clinical documentation expectations mean that a single chamber design may require region-specific adaptations before launch. This fragmentation raises the operational bar for international expansion but also rewards manufacturers that invest in harmonized design architectures and proactive regulatory planning. The result is a market where compliance capability is itself a competitive asset, and where firms that treat regulatory engagement as a continuous engineering function rather than a periodic submission exercise are better equipped to scale across geographies.
Demand-Side Shifts in Respiratory Care Delivery
Clinical utilization patterns are evolving in ways that directly expand the addressable market for auto-fill humidification chambers. Critical care environments continue to represent the largest demand concentration, driven by sustained ICU admissions, the need for precise humidity control during invasive and non-invasive ventilation, and the integration of humidification into standardized airway management protocols. However, growth is increasingly distributed across additional care settings. Home healthcare utilization has expanded as patients require ongoing respiratory support outside acute facilities, and specialty clinics have adopted heated humidification for a broader range of procedures and therapy regimens. These shifts extend the product lifecycle beyond episodic acute care and create recurring demand in decentralized care environments.
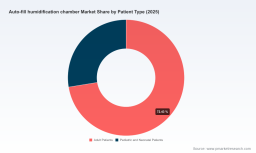
Patient demographic trends further reinforce this broadening demand base. Adult patient populations continue to account for the majority of utilization, reflecting higher prevalence of chronic respiratory conditions, post-surgical ventilation needs, and age-related pulmonary complications. At the same time, pediatric and neonatal applications sustain meaningful demand, particularly in units requiring precise compressible volume management and gentle humidity delivery for sensitive airways. The dual demand profile supports a diversified product strategy, where manufacturers can maintain broad-compatible platforms while offering configurations tailored to specific patient cohorts. This segmentation does not necessarily require entirely separate product lines, but it does demand engineering flexibility and clear clinical differentiation in marketing and distribution.
PW Consulting
Supply Chain Architecture and Cost Structure Dynamics
Cost structures in the auto-fill humidification chamber market are shaped by material selection, manufacturing precision, sterilization requirements, and distribution logistics. The prevailing disposable, single-patient-use model simplifies infection control but introduces continuous procurement cycles. Healthcare providers evaluate these products not only on clinical performance but also on total cost of ownership, which includes inventory management, waste handling, and compatibility with existing humidifier and breathing system ecosystems. Manufacturers that can offer reliable compatibility across major heated humidifier platforms reduce procurement friction and increase stickiness with institutional buyers.
Simultaneously, the cost of maintaining sterile packaging and meeting infection control specifications adds a layer of operational overhead. Sterile configurations require validated packaging processes, environmental controls, and cold-chain or controlled-storage considerations depending on regional distribution networks. These requirements elevate baseline costs but also create differentiation opportunities. Suppliers that can deliver sterile, ready-to-use chambers with consistent fill reliability and minimal setup time align closely with hospital priorities around workflow efficiency and patient safety. On the supply side, companies that standardize component designs, consolidate mold families, and regionalize manufacturing reduce exposure to logistics volatility and improve margin predictability. The companies that thrive will be those that treat supply chain design as an integral part of product strategy rather than a downstream execution concern.
Respiratory Humidifying Equipment Market
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a concentrated group of established manufacturers alongside regional and specialty suppliers that compete on compatibility, configuration breadth, and clinical support. The market exhibits notable concentration, with a small number of players capturing a substantial share of global demand. This structure reflects the importance of regulatory experience, existing humidifier ecosystem relationships, and manufacturing scale, all of which create meaningful barriers to rapid displacement. Yet the landscape is not static. Product differentiation, regional licensing strategies, and targeted portfolio expansions continue to reshape positioning within the leading cohort.
Fisher & Paykel Healthcare has built a strong position through a clearly defined product architecture centered on its MR290 series. The lineup includes multiple configurations designed to accommodate adult, pediatric, and high-frequency ventilation use while maintaining consistent compressible volume. The dual-float mechanism addresses two persistent clinical concerns: automatic refilling without flow interruption and overfill prevention. By aligning chamber design with the broader myAirvo and MR-series humidifier ecosystem, the company reinforces platform compatibility and simplifies procurement for facilities already standardized on its humidification infrastructure. Recent regulatory clearances for circuit kits incorporating these chambers further demonstrate a strategy of bundling chamber technology with integrated respiratory therapy solutions rather than selling components in isolation.
Intersurgical maintains a differentiated focus on dual-float auto-fill chambers offered in both standard and sterile configurations, with fill sets designed for compatibility with common heated humidifiers used across CPAP to full mechanical ventilation, including high-frequency oscillation. The emphasis on constant water level maintenance reflects a direct response to the clinical need for stable compressible volume across neonatal to adult populations. This positioning supports use in ICU environments where ventilation modes vary widely within a single unit, allowing a single chamber platform to serve multiple patient scenarios without compromising performance consistency.
Flexicare competes by expanding configuration options, including sterile versions and double-valve variants tailored for Bi-PAP applications. The use of primary and secondary floats for overfill protection, combined with designs optimized for reduced warm-up time through lower water volume, points to a strategy focused on operational efficiency and compatibility with heated wire breathing systems. By targeting specific ventilation modes and emphasizing setup speed, Flexicare addresses practical pain points in busy respiratory care environments where time-to-therapy and compatibility with existing airway circuits influence purchasing decisions.
In the Asia-Pacific region, GaleMed Corporation and Vadi Medical Technology illustrate a different competitive approach centered on sensitivity of the auto-filling mechanism and broad brand compatibility. GaleMed’s auto-feeding designs emphasize uninterrupted ventilation during sterile water refill, a feature particularly relevant for neonatal and adult applications where continuity of therapy is paramount. Vadi’s offering extends this logic with reusable and auto-feed versions designed to work across major humidifier brands, appealing to procurement teams seeking flexibility in mixed-equipment environments. These manufacturers demonstrate that regional players can compete effectively by prioritizing compatibility breadth and mechanism responsiveness rather than relying solely on global brand recognition.
Yaxin Medical adds another layer to the competitive mix with disposable auto-fill chambers engineered for compatibility with ICU ventilators and generic humidifiers, incorporating standardized connectors to simplify integration. This approach reflects a cost-conscious, compatibility-first strategy that targets high-throughput environments where standardization and ease of integration reduce training and setup burden. Vyaire Medical, through its AirLife product line, reinforces the importance of established respiratory care distribution channels and regulatory familiarity. Recent submission activity referencing prior autofill chamber technology indicates ongoing iteration within an existing platform framework, suggesting a strategy of incremental refinement rather than radical redesign.
The overall competitive trajectory points toward selective convergence around a few strategic themes. First, compatibility across major humidifier platforms remains a primary battleground, as institutions prefer fewer integration variables and simpler replacement workflows. Second, sterile single-use configurations are becoming a baseline expectation in hospital settings, making sterile packaging capability a table-stakes feature rather than a differentiator. Third, the market is experiencing incremental consolidation pressure as larger respiratory care suppliers seek to expand their humidification ecosystems, while smaller or regional manufacturers pursue niche positioning through specialized ventilation modes, regional distribution strength, or cost-optimized disposable formats. New entrants will likely need to navigate the regulatory pathway efficiently while offering a clear clinical or procurement advantage, whether through improved fill reliability, broader compatibility, faster warm-up, or streamlined supply arrangements.
Future Trends and Commercial Implications (2026–2032)
Over the next several years, the auto-fill humidification chamber market is likely to be shaped by three interlocking trends. The first is the continued expansion of heated humidification into decentralized care settings. As respiratory support increasingly extends beyond traditional ICU environments into home-based and ambulatory care pathways, demand for reliable, easy-to-deploy humidification components will grow. This trend favors products that combine clinical consistency with straightforward setup and clear patient-use guidance. Commercial opportunities will emerge for suppliers that can support both institutional and decentralized procurement models without compromising sterility, compatibility, or documentation standards.
The second trend is the gradual tightening of performance expectations around compressible volume stability and workflow integration. Clinicians and procurement teams are increasingly aware that humidification performance directly affects ventilation efficiency and patient comfort. Chambers that maintain stable water levels across varying ventilation modes, reduce warm-up time, and integrate cleanly with heated wire circuits will be preferred in competitive evaluations. This creates opportunities for manufacturers that invest in mechanism precision, standardized connector architectures, and compatibility validation across widely used humidifier platforms. The practical implication is that product leadership will be measured less by presence in the market and more by demonstrable consistency across real-world ventilation scenarios.
The third trend involves ongoing regulatory and reimbursement scrutiny that will influence purchasing behavior and product design. As healthcare systems continue to optimize cost structures, the classification and billing pathways for humidification supplies will remain relevant to procurement decisions. Devices that fit cleanly into existing reimbursement frameworks and demonstrate clear clinical utility are more likely to retain favorable purchasing status. However, regulatory expectations around single-patient-use labeling, sterilization validation, and post-market surveillance will continue to evolve, creating compliance overhead that rewards organizations with mature quality systems and proactive documentation practices. The principal risk lies in supply chain disruption, material cost volatility, and the potential for regional regulatory divergence to slow international rollouts. Additionally, any shift toward reprocessing debates or alternative materials could pressure the disposable model, though current infection control priorities strongly reinforce single-use adoption. Companies that monitor these dynamics early and build adaptable manufacturing and compliance frameworks will be better positioned to convert market growth into sustainable margin expansion.
Strategic Recommendations for Decision-Makers
Manufacturers should prioritize platform compatibility and configuration flexibility as core growth levers. Investing in chamber designs that maintain consistent performance across major humidifier ecosystems reduces procurement friction and strengthens retention in institutional accounts. Where possible, standardizing connector geometries, float mechanisms, and sterile packaging workflows will lower operational complexity while expanding addressable use cases across adult, pediatric, and neonatal settings. Regulatory planning should be treated as a continuous engineering function, with early alignment to submission pathways for new configurations or compatibility claims.
Investors evaluating exposure to this market should focus on companies that demonstrate durable regulatory capability, diversified supply chains, and clear positioning in high-utilization care settings. The market’s steady growth trajectory is attractive, but value capture depends on execution in manufacturing consistency, sterile packaging reliability, and global compliance management. Portfolio strength in ICU and respiratory care distribution channels, combined with evidence of iterative product refinement, is a meaningful indicator of resilience against competitive and supply chain disruption.
Walk In Humidity Chambers Market
Healthcare procurement and clinical operations leaders should prioritize total cost of ownership analyses that account for setup time, compatibility breadth, infection control compliance, and replacement cycle predictability. Standardizing on chambers that integrate cleanly with existing humidifier platforms can reduce training overhead and inventory complexity, while sterile single-use configurations help align with institutional infection control mandates. As utilization continues to expand across care settings, maintaining visibility into supplier reliability, regulatory status, and product iteration pipelines will support more informed sourcing decisions. For organizations seeking deeper segmentation data, regional demand patterns, and customized procurement or investment guidance, the full PW Consulting research report provides a more granular view of market dynamics and actionable next steps.
For detailed analysis of this topic, please visit the official page: Worldwide Auto-fill humidification chamber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


