



Mobile App Development Platform Market: Why 22.5% CAGR Redefines Growth by 2032

Global Mobile Application Development Platform Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The global market for mobile application development platforms has entered a period of rapid expansion. From a valuation of approximately $10.2 billion in 2020, the sector grew to around $28.5 billion by 2025, reflecting a compound annual growth rate of 22.5 percent over the historical period. Projections indicate that the market will continue its upward trajectory, reaching roughly $117.9 billion by 2032. This acceleration is not merely a byproduct of broader digital adoption; it reflects a fundamental shift in how organizations conceive, build, and deploy mobile experiences. The pace of growth suggests that development platforms are evolving from tactical tools into strategic infrastructure components that determine how quickly enterprises can respond to changing customer expectations and operational demands.
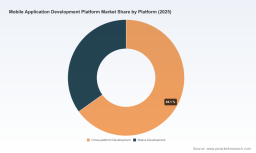
Geographically, the market demonstrates a broad but uneven distribution. North America continues to represent the largest single regional bloc, while Asia Pacific and Europe each command substantial shares of total revenue. Latin America and the Middle East and Africa, though smaller in absolute terms, are growing faster than mature markets as organizations in those regions modernize legacy systems and expand digital service offerings. Deployment models are similarly tilted toward cloud-based solutions, which now account for the majority of platform revenue, though on-premise deployments retain a meaningful presence among organizations with strict security, compliance, or latency requirements. In terms of development approach, cross-platform solutions lead in overall market share, reflecting the broad appeal of unified codebases and faster time-to-market, while native development maintains a solid position in sectors where performance, platform-specific features, and deep ecosystem integration remain decisive.
The market is moderately concentrated. The three largest players collectively hold roughly 41.8 percent of total revenue, and the top five account for approximately 56.4 percent. This concentration indicates that leading platforms have achieved scale advantages in distribution, ecosystem depth, and enterprise trust. Yet the presence of a long tail of specialized and emerging vendors suggests that differentiation is increasingly driven by vertical expertise, workflow-specific capabilities, and integration quality rather than by generic low-code features alone. For decision-makers, this means that platform selection is less about picking the largest name and more about aligning platform strengths with the organization's operating model, compliance posture, and speed-to-value requirements.
IoT Platforms Market
Several structural challenges and inflection points shape the current environment. First, platform Evaluation fatigue is rising as the number of viable options expands and feature overlap increases. Buyers face growing difficulty in assessing which platforms will genuinely accelerate delivery versus those that simply promise flexibility but create hidden integration and maintenance burdens. Second, the cost and reliability of underlying infrastructure are becoming more material. As AI-enabled development assistants, continuous integration pipelines, and cloud-hosted testing environments become standard, demand for compute and storage is intensifying, and organizations must factor rising infrastructure costs into total cost of ownership assessments. Third, regulatory complexity is accelerating. Data sovereignty requirements, consumer privacy laws, and the impending full implementation of the EU AI Act are redefining what constitutes a compliant mobile application, especially for platforms that embed AI-assisted generation, personalization, or automated decisioning. Together, these forces are turning platform procurement into a multi-dimensional decision that balances speed, governance, and long-term operational risk.
Key Drivers of Market Change
The expansion of mobile application development platforms is being propelled by a convergence of technological, regulatory, demand-side, and cost-structure forces. Each of these drivers is reshaping the value proposition of platforms and redefining what buyers expect from their development tooling.
Technological innovation remains the most visible driver. AI-assisted development, model-driven design, and low-code/no-code interfaces are compressing delivery timelines for both enterprise and mid-market teams. Platforms are increasingly embedding generative capabilities that help developers scaffold interfaces, generate business logic, and automate repetitive tasks, while still providing governance hooks for controlled deployment. A notable example is Appian Corporation's version 25.1 release in February 2025, which introduced an AI-powered data fabric that significantly improved document processing speed for enterprise applications. This kind of capability illustrates how platforms are moving beyond simple UI builders to become orchestration layers that handle complex data workflows, document intake, and process acceleration. For organizations, the implication is clear: platforms that combine rapid development with AI-enhanced productivity can shorten project cycles and reduce the reliance on scarce specialized engineering resources.
Regulatory and policy shifts are also reshaping platform design and procurement. As of January 2026, twenty U.S. states had comprehensive consumer privacy laws in effect, requiring mobile applications to address data collection, consent, and processing practices in a consistent and auditable manner. Meanwhile, data sovereignty and localization rules continue to tighten in the EU under GDPR, across parts of Asia-Pacific, and in the Middle East, mandating where user data must be stored and processed. These requirements are pushing platforms to offer stronger controls around data residency, consent management, and audit trails. They are also encouraging enterprises to favor platforms that provide transparent governance and the ability to configure regional data handling without sacrificing speed. For vendors, compliance is no longer a secondary feature; it is a competitive differentiator that can determine win rates in regulated industries and multinational deployments.
PW Consulting
On the demand side, enterprise behavior is shifting toward faster, more continuous delivery of mobile experiences. Companies are increasingly treating mobile applications as living touchpoints rather than static product releases, requiring platforms that support iterative updates, offline-first usage patterns, and tight integration with back-end systems such as CRM, ERP, and data clouds. Salesforce's completion of its Informatica acquisition in May 2025 highlights this trend: by strengthening data and AI capabilities across its Lightning Platform, the company signaled a broader industry move toward unifying application development with deeper data integration and AI-driven insights. For buyers, this convergence means that platform decisions increasingly affect not just development velocity but also the ability to derive actionable insights from the data that mobile applications generate.
Cost and supply-side dynamics are adding both pressure and opportunity. The infrastructure underpinning cloud-based development and deployment is experiencing significant demand growth. U.S. data centers' total electricity demand is projected to nearly double from roughly 80 GW in 2025 to about 150 GW in 2028, driven by AI and cloud workloads that support mobile application development and deployment. This infrastructure strain is likely to translate into higher compute and storage costs over time, particularly for platforms that rely heavily on AI-assisted services and continuous cloud-based testing. At the same time, the shift toward cloud-based deployment is helping many organizations reduce on-premise overhead and gain elasticity. The net effect is that cost optimization is becoming a more sophisticated exercise: enterprises must weigh the savings from cloud elasticity against the risk of rising infrastructure pricing and the need for resilient, well-governed architecture.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a handful of scaled platform providers, a strong presence of ecosystem-led players, and a persistent set of native tooling champions. Each cluster pursues a distinct strategic logic, and understanding these differences is essential for assessing where value is being created and how the landscape may evolve.
Microsoft Corporation has anchored its offering around Power Apps, a low-code mobile application development platform integrated with Microsoft 365, Azure, and Dataverse. Its strategy emphasizes rapid enterprise mobile and web app creation with strong governance and AI capabilities, positioning the platform as a natural fit for organizations already invested in the Microsoft ecosystem. OutSystems, Inc. takes a different approach, offering a full-stack low-code platform specialized in complex, mission-critical mobile and web applications. Its differentiation rests on AI-assisted development, one-click deployment, and enterprise-grade security and scalability, making it attractive to organizations that need to build sophisticated applications without sacrificing control or performance. Mendix, now part of Siemens, focuses on collaborative, model-driven development with strong support for offline-first mobile apps and industrial and enterprise use cases. Its positioning reflects an emphasis on teamwork, model-based design, and scenarios where mobile apps must operate reliably in environments with intermittent connectivity or in close integration with industrial systems.
Appian Corporation supplies a low-code automation platform that combines mobile application development with process management, case management, and AI-powered decision-making for complex enterprise workflows. Its strategic emphasis is on workflow orchestration and decision support, appealing to organizations that view mobile applications as part of broader operational processes rather than isolated digital products. Salesforce, Inc. offers the Lightning Platform and related tools for building custom mobile applications deeply integrated with CRM, data cloud, and AI capabilities. Its strength lies in extending the CRM ecosystem into custom mobile experiences, particularly for enterprise customers that want development to stay closely aligned with customer data and sales/service workflows. Google LLC provides AppSheet as a no-code/low-code platform for building mobile apps directly from data sources such as Google Sheets or databases, with strong integration into Google Workspace and cloud services. This approach targets rapid, data-driven app creation for teams that want to move quickly without heavy engineering investment.
Apple Inc. remains the primary native development anchor through Xcode and associated SDKs for iOS, iPadOS, and related ecosystems. While not a low-code player in the traditional sense, Apple's tooling defines the standard for platform-specific performance, user experience fidelity, and access to device capabilities, and it continues to influence how cross-platform and low-code tools must evolve to meet native expectations. IBM Corporation provides IBM Mobile Foundation as an enterprise mobile application development platform supporting secure mobile app management, backend integration, and hybrid development, which appeals to organizations that need a balance of mobile delivery and enterprise security. Oracle Corporation delivers APEX and related cloud tools as low-code platforms for building mobile-ready enterprise applications integrated with Oracle databases and cloud infrastructure, targeting environments where database-centric development and Oracle ecosystem alignment are strategic priorities. SAP SE offers SAP Mobile Services and low-code capabilities within its Business Technology Platform for developing mobile applications integrated with SAP ERP and enterprise systems, positioning mobile development as part of a broader enterprise transformation strategy.
Several strategic patterns emerge from this landscape. First, ecosystem integration is a powerful differentiator. Platforms that align closely with widely adopted productivity, CRM, ERP, or cloud ecosystems benefit from shorter adoption cycles, familiar governance models, and clearer value narratives for business buyers. Second, AI-assisted development is becoming a central battleground. As platforms embed AI for scaffolding, documentation, testing, and process automation, the winners are likely to be those that balance speed with governance, ensuring that AI-generated outputs remain auditable and controllable. Third, the market is showing signs of both consolidation and specialization. Large players are expanding through acquisitions and capability broadening, as seen with Salesforce's data and AI-focused moves, while specialized vendors compete on vertical depth, workflow complexity, and industrial or regulated-use scenarios. New entrants and niche providers continue to appear, often targeting underserved segments or specific development pain points. The net effect is a market in which scale confers advantages, but differentiation increasingly depends on the ability to solve specific workflow, compliance, and integration problems rather than on generic low-code promises.
Future Trends and Strategic Implications
Looking ahead to the next three to five years, several trends are likely to shape the market's trajectory and create distinct commercial opportunities. These trends are grounded in current data patterns and the regulatory, technological, and cost dynamics already in motion.
One major trend is the shift from generic low-code platforms toward workflow- and industry-aware development environments. As enterprises demand more than simple form builders and UI scaffolds, platforms that embed domain-specific templates, process orchestration, offline-first design, and AI-assisted decisioning will gain preference in complex environments such as healthcare, manufacturing, financial services, and field operations. This creates an opportunity for vendors that can combine rapid development with deep workflow intelligence, and for buyers who can reduce long-term maintenance burdens by choosing platforms aligned with their operational realities rather than generic development needs.
A second trend is the growing importance of governance, compliance, and data handling as core platform selection criteria. With the EU AI Act reaching full implementation in August 2026 and imposing requirements on high-risk AI systems used in mobile application development platforms, and with consumer privacy and data sovereignty rules continuing to tighten, platforms will need to offer transparent controls, auditable AI usage, and configurable data residency. For enterprises, this means that platform evaluations should increasingly include compliance stress-testing, especially for applications handling sensitive data or supporting automated decisions. Vendors that can demonstrate robust governance without sacrificing speed will be well positioned to win in regulated and multinational contexts.
Messaging Platform Market
A third trend is the rising influence of infrastructure economics on platform strategy. As AI workloads and cloud-based development pipelines intensify demand on data center capacity, costs associated with compute, storage, and AI services are likely to become more prominent in total cost of ownership calculations. This may encourage platforms to optimize resource usage, offer more efficient AI assistance modes, or provide hybrid deployment options for cost-sensitive scenarios. For buyers, it suggests that platform comparisons should extend beyond license or subscription pricing to include the likely trajectory of infrastructure and AI service costs over the planning horizon.
These trends carry both opportunity and uncertainty. The outlook is favorable for platforms that can deliver speed, governance, and ecosystem integration in a coherent package, and for enterprises that use development platforms to accelerate digital initiatives while maintaining control over compliance and cost. However, uncertainty remains around the pace of AI regulation, the trajectory of infrastructure pricing, and the degree to which cross-platform tools can continue to narrow the gap with native experiences in performance-critical scenarios. Organizations that monitor these variables closely will be better prepared to adapt their platform strategies as conditions evolve.
Recommendations for Decision-Makers
For platform vendors and product manufacturers, the priority is to reinforce differentiation through depth rather than breadth alone. Investing in workflow-specific capabilities, strong governance and compliance controls, and seamless integration with widely used enterprise systems can create defensibility even in a crowded market. Vendors should also consider how AI-assisted features are packaged and governed, since buyers are increasingly evaluating not just how fast a platform can build an app, but how safely and auditably it can do so.
For investors, the strategic value lies in distinguishing between platforms with genuine enterprise traction and those riding generic low-code narratives. Attention should be paid to governance capabilities, ecosystem integration, vertical specialization, and the ability to manage infrastructure cost pressures. Companies that can demonstrate measurable reductions in development cycle time while maintaining compliance and operational reliability are likely to command stronger positioning as the market matures.
For procurement and technology leadership teams, platform decisions should be approached as multi-year strategic choices rather than short-term productivity purchases. Evaluations should weigh development speed, integration complexity, data handling and compliance posture, offline and field-use requirements, and the likely evolution of AI-related infrastructure costs. Given the pace of change in regulation and platform capabilities, ongoing market intelligence is essential for keeping procurement criteria aligned with shifting risk and value drivers.
For readers seeking a more detailed breakdown of segmentation dynamics, regional nuances, competitive benchmarking, and customized strategic recommendations, the full PW Consulting research report provides a deeper evidence base and structured scenarios to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Mobile Application Development Platform Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


