



Smart Seam Tracking Laser Sensors: Why 7.5% CAGR Reshapes Market|2026-2032

The Strategic Evolution of the Smart Seam Tracking Laser Sensors Market
The global market for smart seam tracking laser sensors has entered a phase of structurally accelerating growth, expanding from approximately 490.2 million USD in 2020 to an estimated 685.0 million USD in 2025, with momentum carrying toward more than 1.13 billion USD by 2032. This trajectory translates to a compound annual growth rate of 7.5 percent across the 2026-2032 forecast window. The growth is neither cyclical nor narrowly tied to a single industrial cycle; rather, it reflects a foundational shift in how automated fabrication, assembly, and inspection workflows are engineered. Seam tracking has transitioned from a niche alignment aid to a core perception layer that enables closed-loop control in robotic welding, hybrid joining, brazing, and precision inspection. As tolerance stacks tighten and production volumes scale across mobility, marine, and advanced manufacturing sectors, the sensor layer has become the differentiating factor between basic automation and adaptive, high-yield processing.
Despite the clear growth path, manufacturers and system integrators are navigating three overlapping challenges that will define competitive outcomes over the next half decade. First, the industry must reconcile performance expectations with real-world variability. Workshop lighting, surface oxidation, gap deviations, and material heterogeneity consistently degrade the robustness of vision-based tracking if algorithms, optics, and illumination are not co-optimized for production environments rather than controlled lab conditions. Second, supply chain fragility has moved from a logistical nuisance to a strategic cost driver. Concentrated sourcing of high-power semiconductor components, laser optics, and specialty substrates introduces exposure to pricing shocks and lead-time elongation, forcing vendors to redesign bill-of-materials strategies and qualification pipelines. Third, integration complexity remains a persistent adoption barrier. While individual sensor specifications are increasingly impressive, the value is realized only when tracking data is fused seamlessly with robot kinematics, process controllers, and quality management systems, a requirement that demands ecosystem readiness rather than stand-alone hardware superiority. Addressing these friction points is no longer an engineering afterthought; it is the central commercial battleground.
Market Architecture and Concentration Dynamics
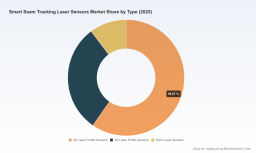
The revenue base is distributed across a mix of established sensor specialists and application-focused equipment players, with a meaningful share of total volume concentrated among a small group of incumbents. This concentration does not imply a static hierarchy. Instead, it reveals a market where differentiation is increasingly earned through software maturity, cross-platform compatibility, and lifecycle support rather than pure sensor resolution. The three dimensional profile segment commands the largest revenue share, reflecting the broader industry migration from simple line profiling to volumetric perception that can handle complex joint geometries and variable gaps. Two dimensional profile sensors retain strong adoption in high-speed, lower-complexity tasks where cost and cycle time dominate purchasing decisions, while point laser sensors serve targeted displacement and alignment uses. Geographically, demand is broadest across Asia Pacific, followed by Europe and North America, with Latin America and the Middle East and Africa representing smaller but strategically important footprints tied to localized capacity expansion and export-oriented fabrication. Across application domains, automotive manufacturing leads demand formation, reflecting the impact of electrification on joint designs, material mixes, and throughput requirements. Heavy machinery and infrastructure, shipbuilding, and aerospace and defense each contribute sizable demand blocks shaped by durability requirements, regulatory scrutiny, and the rising use of robotic processes in large-scale structures and precision assemblies.
Key Drivers Shaping the Next Growth Cycle
Technology Innovation and Sensor Intelligence
The most consequential driver is the maturation of sensor intelligence itself. Modern systems are no longer simply delivering better point clouds; they are increasingly capable of adaptive interpretation under imperfect conditions. Advances in image processing pipelines, real-time filtering, and edge-based inference have improved seam detection reliability in environments where joint preparation varies, weld spatter is present, or surface finish is inconsistent. The practical effect is a reduction in false rejects, fewer manual interventions, and higher first-pass yield, which directly improves the economics of automated joining. In parallel, hybrid approaches that combine laser profile data with displacement and groove detection are reducing the need for multiple stand-alone sensors on the end effector, simplifying payload management and lowering integration risk. Recent product refreshes that emphasize enhanced image processing for precise seam tracking in automated welding illustrate how vendors are shifting from hardware-centric specifications toward application-tuned performance. This shift matters commercially because it expands the addressable envelope from ideal applications into broader, less forgiving production settings where the return on automation is most contested.
Policy, Standards, and Strategic Industrial Directives
Regulatory and policy environments are quietly but decisively reshaping demand patterns. In shipbuilding and advanced marine fabrication, national guidelines promoting smart shipyard development have created explicit tailwinds for robotic welding precision and integrated laser seam tracking. These directives do not merely encourage automation in principle; they support procurement strategies, modernization programs, and supplier qualification paths that make sensor-enabled joining more bankable for yard operators and tier suppliers. Equally important, quality assurance expectations in aerospace, defense, and safety-critical mobility segments are tightening, which elevates the role of inspection-grade tracking as part of a unified process rather than a separate quality gate. When seam tracking becomes part of the process control logic rather than a post-process verification step, the sensor transitions from an optional accessory to a core process enabler. For decision-makers, the strategic implication is that adoption is increasingly influenced by compliance roadmaps, export requirements, and program-level quality targets as much as by unit cost or cycle time.
Demand-Side Transformation in Mobility and Heavy Fabrication
On the demand side, the most visible change is the structural shift in joining requirements across e-mobility, vehicle architecture evolution, and large-scale fabrication. Electric drivetrains, battery enclosures, lightweight structural elements, and mixed-material assemblies introduce new gaps, thicker coatings, and more varied joint geometries than legacy body-in-white production. Robotic laser welding and hybrid joining are responding to these requirements because they can achieve consistent results while preserving productivity, but they also demand higher robustness from the tracking layer. In shipbuilding and infrastructure-adjacent heavy fabrication, similar pressures exist: longer structural runs, complex edge conditions, and a need to reduce rework in high-value assemblies. The common thread is that tolerance control and process repeatability are becoming more valuable than raw speed alone. As a result, end users are more willing to invest in sensors that demonstrably reduce rework, support adaptive path correction, and provide inspection-grade confidence. This demand evolution favors suppliers that can articulate total process value rather than sensor-only performance metrics.
Supply Chain Realities and Cost Structure Pressures
Cost structures are undergoing a simultaneous push and pull. On one side, raw material and component pressures have intensified. Restrictions and export dynamics affecting gallium and germanium, alongside broader concentration in high-power semiconductor and optics supply, have driven notable price increases in critical inputs, with ripple effects across laser-based and optics-intensive sensor designs. On the other side, integration complexity and qualification cycles can inflate total cost of ownership if the sensor is treated as an isolated component rather than part of a coordinated system. The resulting dynamic favors vendors that can stabilize performance despite component volatility, offer modular designs, and deliver predictable field performance with minimal recalibration burden. For buyers, the cost conversation is shifting from sticker price to resilience: supply assurance, multi-source readiness, software support longevity, and integration compatibility now weigh heavily in evaluation. Suppliers that overlook these factors risk margin erosion even when their core technology is competitive.
Worldwide Security Laser Scanner Market
Competitive Landscape and Differentiation in Practice
The competitive field blends specialized sensor manufacturers, welding-equipment integrators, and emerging players with regional cost advantages and application-specific engineering depth. A defining feature of the leaders is that they do not compete solely on resolution or scan speed; they compete on how well the sensing capability is packaged into the target process. Some firms anchor their positioning in high-speed, high-accuracy vision systems explicitly engineered for laser welding, hybrid welding, and brazing, where real-time joint guidance must keep pace with rapid thermal cycles and moving workpieces. Others emphasize optical seam tracking tuned for automated arc and laser welding, with particular attention to e-mobility and automotive use cases where tolerances and material variability are elevated. A further group integrates laser seam tracking sensors directly with robotic welding torches and joint guidance systems, aiming to reduce end-effector complexity and shorten deployment cycles. This diversity in go-to-market posture reflects a market that is still maturing from component competition toward solution-level competition.
Several strategic differentiators are increasingly decisive. First, cross-platform compatibility is becoming a practical necessity. As customers standardize on major robot brands and seek to deploy tracking across multiple cell designs, sensors that demonstrate reliable interoperability with common controllers and robot ecosystems reduce integration friction and expand addressable reuse within a facility. Second, the ability to support both real-time tracking and downstream inspection functions is gaining commercial weight. Systems that can guide the weld and then contribute to bead profile inspection or displacement verification offer a more complete value proposition, especially where quality records and traceability are mandatory. Third, application specialization is creating defensible niches. Vendors with focus on zero-gap detection for sheet metal, aerospace-oriented sensor lines, or specialized weld bead profiling are building domain credibility that generic specifications cannot easily replicate. This does not mean broad platforms are losing relevance; rather, the most resilient players are pairing broad compatibility with application-specific tuning and support.
Laser Displacement Sensor Market
The competitive evolution is also being shaped by a mix of consolidation logic and new-entry pressure. On one hand, established players are likely to deepen vertical integration around software, service, and integration support, because those layers increasingly determine retention and expansion within existing accounts. On the other hand, regional manufacturers and sensor-focused entrants continue to expand, particularly where localized price-performance ratios, faster engineering responsiveness, and strong relationships with domestic robot integrators create a viable path to scale. A notable early signal is the emergence of sensor lines targeting high-stakes verticals such as aerospace, which reflects both demand maturation and the willingness of large customers to qualify specialized offerings for demanding tolerances. The net direction is not simply toward fewer competitors; it is toward clearer segmentation between general-purpose tracking platforms and application-hardened solutions, with the most competitive firms capable of bridging both through modular architectures and adaptable software stacks. For customers, this means the evaluation framework should weigh ecosystem fit and support capability as heavily as raw sensing performance.
Forward-Looking Trends and the Shape of Opportunity
Over the next three to five years, the market is likely to consolidate around three interrelated trends. The first is the expansion of perception from tracking to closed-loop process control. Seam tracking will increasingly feed adaptive path correction, dynamic parameter adjustment, and inspection feedback within a single workflow, reducing dependence on offline quality sampling and shortening response time to process drift. This creates commercial opportunities for vendors that can deliver reliable sensor data in a form that controllers and quality systems can consume without heavy middleware or custom integration work. The second trend is the continued migration from hardware differentiation toward software and algorithm differentiation. As baseline optical and scanning performance becomes more comparable across competent suppliers, the edge will increasingly belong to systems that perform better under variable joint gaps, surface conditions, and production noise, and that can be updated and tuned without extensive re-qualification. The third trend is a growing emphasis on supply resilience and modular design. Given ongoing component volatility, customers will reward suppliers that can articulate risk-mitigated sourcing, maintain performance continuity across revisions, and offer flexible configuration options aligned with different payload, cycle-time, and budget constraints.
These trends translate into concrete opportunity spaces. For system integrators and equipment builders, the opportunity lies in embedding sensor capability earlier in the design of welding cells and large-scale fabrication lines, so that tracking is planned as a process layer rather than retrofitted as an add-on. For end users, the opportunity is to use tracking data not simply to improve alignment but to unlock higher automation rates in applications that were previously considered too variable for unattended operation. At the same time, uncertainty remains. Pricing pressure on critical optical and semiconductor inputs could compress margins or slow product iteration in segments where cost sensitivity is high. Adoption may also fragment if integration standards and data interfaces remain inconsistent, forcing repeated customization across robot platforms and cell architectures. Finally, the competitive mix may shift quickly where regional players gain traction through strong local support and cost positioning. These dynamics do not threaten the broader growth path, but they do reward participants who can balance technological ambition with deployment practicality.
Strategic Actions for Decision-Makers
For manufacturers and equipment integrators, the priority is to treat seam tracking as part of the core process architecture rather than a peripheral feature. Selection criteria should emphasize robust performance under real production variability, compatibility with existing robot ecosystems, and the ability to support both guidance and inspection use cases within a manageable integration footprint. Suppliers that can demonstrate repeatable outcomes across joint variation and surface conditions will increasingly capture preference over those competing only on peak specifications or isolated lab results. This is also the moment to evaluate whether in-house tracking capability, partnership with a sensor specialist, or bundled equipment offerings best fit long-term process roadmaps.
For investors and corporate strategists, the key is to differentiate between sensor hardware exposure and solution-level exposure. Revenue tied to recurring software support, integration services, and application-specific qualification is likely to be more durable than revenue dependent solely on unit volume in commoditizing segments. Watching which companies expand across multiple verticals while maintaining integration simplicity and supply resilience will provide an early signal of which positions are likely to scale. Capital and partnership decisions should account for the possibility that value capture shifts toward players capable of combining perception hardware with the software, support, and ecosystem relationships needed to keep systems operating in demanding environments.
For procurement and operations leaders, the emphasis should move toward total cost of ownership and deployment reliability. Where possible, qualification should include tests that reflect actual gap variation, surface finish, and noise conditions rather than idealized setups. Multi-source readiness, lifecycle support expectations, and compatibility with the dominant robot and controller platforms in the facility should weigh heavily in purchasing decisions. Tracking investments will deliver the strongest returns when they are aligned with broader automation and quality objectives, allowing process teams to reduce rework, increase automation coverage, and build more consistent inspection evidence from the same data stream. For organizations seeking deeper segmentation data, competitive benchmarking, and customized adoption roadmaps, the full research report provides the detailed breakdowns and scenario analysis needed to translate these trends into precise procurement, investment, and product strategy decisions.
PW Consulting Information & Electronics Research Center
For detailed analysis of this topic, please visit the official page: Smart Seam Tracking Laser Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


