



Smart Waste Collection at 13.5% CAGR: The Real Drivers Behind $6.4B Growth

The Smart Waste Collection Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
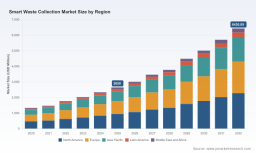
The smart waste collection market has transitioned from a niche urban experimentation space to a mainstream infrastructure priority over the past half-decade. Valued at approximately $2.65 billion in 2025, the sector has expanded from $1.34 billion in 2020, reflecting a compound annual growth rate of 13.5 percent through the forecast horizon ending in 2032. By the close of the projection period, revenue is expected to surpass $6.4 billion, signaling a structural shift rather than a cyclical uptick. This trajectory is anchored in the convergence of municipal budget pressures, regulatory mandates for transparent waste tracking, and the maturation of low-power connectivity ecosystems that make sensor-driven logistics economically viable at scale.
The market expansion, however, masks underlying friction points that decision-makers must navigate carefully. First, the cost of deployment remains a persistent barrier for mid-sized cities and commercial operators. Basic smart bin sensor deployments paired with SaaS platforms typically run between €30 and €60 per bin annually, including sensor amortization. While this figure has declined as hardware commoditizes, the total cost of ownership—encompassing installation, network provisioning, platform licensing, and ongoing maintenance—still constrains rapid adoption in budget-constrained environments. Second, data interoperability and integration complexity continue to fragment the value chain. Fleet management systems, route optimization engines, and municipal ERP platforms rarely share common data models, forcing operators to build custom middleware or accept siloed dashboards that limit cross-functional insight. Third, the regulatory landscape is accelerating faster than standardization. Frameworks such as the UK's mandatory Digital Waste Tracking scheme and updated EU Waste Framework Directive requirements are introducing stricter recycling mandates and purity accountability, but compliance pathways vary by jurisdiction, creating uncertainty for multinational operators and technology vendors alike.
These challenges are not deterrents so much as stress tests that will separate durable solutions from short-lived pilots. Organizations that treat smart waste collection as a data infrastructure play—rather than a hardware replacement project—will be better positioned to extract operational leverage and align with evolving compliance expectations.
Key Drivers Behind Market Acceleration
Several interlocking forces are propelling the smart waste collection market toward sustained double-digit growth. Understanding these drivers is essential for anticipating where capital, partnerships, and product development will converge in the coming years.
Technological Breakthroughs in Sensing and Connectivity
Ultrasonic fill-level sensors, solar-powered compaction units, and low-power wide-area network connectivity have matured into reliable, field-tested components. LoRaWAN networks, widely adopted for smart bin monitoring, are undergoing upgrades in 2026 to support hybrid multi-band connectivity, improving coverage in dense urban corridors and reducing reliance on single-network dependencies. This evolution lowers the risk of connectivity gaps that previously undermined route optimization accuracy. On the software side, predictive analytics and route optimization engines are moving beyond static fill-level thresholds toward dynamic models that incorporate historical collection patterns, traffic conditions, and seasonal waste generation profiles. The result is a measurable reduction in unnecessary collection trips, fuel consumption, and labor allocation.
Policy and Regulatory Momentum
Regulation is reshaping waste management from an operational afterthought into a compliance-critical function. The EU Waste Framework Directive updates introduced in early 2026 impose stricter recycling targets and accountability for waste purity, pushing municipalities and industrial operators to demonstrate traceability across collection, sorting, and disposal stages. In parallel, the UK's mandatory Digital Waste Tracking scheme, effective in 2026, is designed to combat waste crime and support circular economy compliance by requiring digital documentation across the waste chain. These mandates create a clear demand signal for platforms that can capture, validate, and report waste movement data with audit-grade reliability. Vendors that embed compliance workflows directly into their analytics and route optimization tools are gaining a structural advantage, as operators seek to avoid fragmented point solutions that increase administrative overhead.
Demand-Side Shifts in Municipal and Commercial Operations
City governments and commercial property managers are increasingly treating waste collection as a service optimization problem rather than a fixed-cost utility. Public space managers, for example, are deploying solar-powered smart waste and recycling stations with compaction and fill-level sensing to reduce collection frequency in high-traffic areas while maintaining cleanliness standards. The deployment of such stations at Emerald Park in partnership with Panda illustrates how public-private arrangements can share deployment risk and align operational incentives. On the commercial side, facility operators face pressure to reduce service disruptions, improve tenant experience, and demonstrate sustainability commitments. Smart collection platforms that provide real-time visibility into bin status and collection scheduling help operators move from reactive pickup schedules to condition-based service models, which in turn supports labor planning and fleet utilization.
Supply Chain and Cost Structure Evolution
The economics of smart waste collection are gradually improving as hardware components become more standardized and software platforms shift toward subscription-based models. Sensor modules and IoT gateways are benefiting from broader industrial IoT supply chain scale, which has helped moderate unit costs and shorten deployment timelines. Meanwhile, the industry context noise around per-bin annual costs of €30–€60 including sensor amortization reflects a broader trend toward unbundled pricing, where hardware, connectivity, and software are priced separately or packaged in tiered service models. This modularity gives operators flexibility to scale incrementally, but it also requires disciplined vendor evaluation to avoid hidden integration and maintenance expenses. Fleet upgrades are another notable shift. The launch of Cart Smart automated garbage and recycling collection using new smart-equipped trucks demonstrates how vehicle-side intelligence—such as onboard scanning, load verification, and route feedback—can complement bin-side sensors, creating a more complete data loop between collection points and hauling operations.
Competitive Landscape and Leading Strategies
The smart waste collection market remains relatively fragmented, with the top three players accounting for roughly 28.5 percent of revenue and the top five reaching approximately 36.2 percent. This concentration leaves substantial room for differentiation, consolidation, and targeted market entry. The competitive field spans solar-powered smart bins, sensor and IoT modules, and software platforms that span route optimization, fleet management, and citizen engagement. Companies are pursuing distinct strategic positions rather than competing on a single dimension.
- Bigbelly has built a recognizable presence in public-space waste management through solar-powered smart waste and recycling stations that combine compaction with fill-level sensing. Its deployments in municipal and commercial public areas emphasize reduced collection frequency and improved space utilization, positioning the brand around visible, self-contained hardware solutions that simplify procurement for parks, campuses, and downtown corridors.
- Ecube Labs operates from a dual hardware-and-platform angle with solar-powered compacting bins and a network management platform that incorporates ultrasonic fill-level sensing and route optimization. Its approach reflects a strategy of tying bin-level intelligence to centralized dispatch, which appeals to operators seeking a single vendor relationship for both field equipment and analytics.
- Sensoneo offers end-to-end smart waste management spanning ultrasonic sensors, data analytics, and route optimization, with a track record in large-scale municipal deployments and deposit return systems. Its recent involvement in Portugal's national Deposit Return System—powering voucher validation and waste tracking—illustrates a strategy of embedding technology into nationally significant compliance and circular economy programs, which can create durable public-sector relationships and reference deployments.
- Evreka focuses on AI-powered digital platforms for waste collection, fleet management, and citizen engagement, with IoT integration tailored to municipalities and operators. Its emphasis on citizen-facing engagement and operational digitization positions it at the intersection of service communication and field execution.
- Rubicon Technologies centers its offering on software for waste and recycling fleet optimization, route planning, and data analytics, serving cities and businesses with a platform-first model. This software-centric positioning allows the company to integrate with existing fleet and municipal systems without necessarily controlling the bin hardware layer.
- Enevo specializes in sensor-based waste monitoring, predictive analytics, and route optimization for haulers and property managers, targeting the operational efficiency layer where fill-level data translates directly into collection scheduling and cost reduction.
- AMCS Group provides an AI-enabled end-to-end waste management and recycling software platform that includes route optimization and smart collection tools, appealing to operators that want a broader enterprise software footprint across recycling, logistics, and customer management.
- Veolia leverages its global environmental services footprint to integrate smart collection technologies, IoT sensors, and data platforms into municipal and industrial operations. Its strategy is less about standalone product sales and more about embedding intelligence into large-scale service contracts, which can accelerate adoption where operators prefer integrated service delivery over fragmented technology procurement.
These companies illustrate a market that is simultaneously differentiating and converging. Hardware-led providers are expanding into software and network management to capture recurring revenue and deepen customer stickiness. Software-centric players are building integrations with sensors and fleet systems to improve data fidelity and route accuracy. Large environmental services firms are layering smart technologies into existing contracts, using scale and service relationships to deploy solutions across multiple sites. The net effect is a landscape where pure-play hardware vendors face pressure to demonstrate platform-level value, while software vendors must prove they can reliably ingest field data and translate it into operational savings.
Market evolution is also being shaped by the pace of standardization and the growing importance of compliance-ready data. As digital waste tracking and recycling accountability requirements tighten, vendors that can offer auditable data flows, transparent reporting, and configurable compliance workflows will likely command stronger positioning in municipal and industrial segments. At the same time, the presence of multiple viable approaches—solar compacting bins, ultrasonic sensors, route optimization platforms, and fleet-side intelligence—suggests continued fragmentation in the near term, with consolidation more likely around integrated data platforms and regional service partnerships than around any single hardware form factor.
Forward-Looking Trends and Commercial Implications
Looking ahead to the 2026–2032 window, several trends are likely to define where value is created and where risk accumulates.
From Bin-Level Sensing to End-to-End Data Loops
The next phase of market maturation will increasingly reward solutions that close the loop between bin status, collection execution, and downstream waste handling. Bin-side sensors and compaction units will remain important, but their strategic value will depend on how effectively they feed route optimization, fleet verification, and compliance reporting. Operators that can demonstrate measurable reductions in empty runs, improved container utilization, and traceable waste movement will have stronger grounds for contract renewals and expansion. Commercial opportunity lies in platforms that combine fill-level intelligence with vehicle-side confirmation and analytics that tie collection efficiency to cost and emissions metrics.
Garbage Truck Market
Compliance-Driven Procurement as a Growth Catalyst
Regulatory mandates for digital tracking, recycling purity, and circular economy accountability are converting compliance from a cost center into a procurement driver. Municipalities and industrial operators are more likely to prioritize solutions that can support mandated reporting and reduce the administrative burden of manual documentation. This creates openings for vendors that design data capture and reporting into everyday collection workflows rather than treating compliance as an add-on module. The risk is that divergent national and regional requirements could increase integration complexity, especially for operators running multi-jurisdiction fleets. Standardization efforts and interoperable data models will matter more as compliance scope expands.
Modular Pricing and Fleet-Side Intelligence Will Reshape Adoption Paths
The trend toward modular hardware, connectivity, and software pricing will likely continue, giving operators more flexibility to scale in stages. This modularity lowers initial barriers but also places a premium on disciplined evaluation of total cost of ownership, including network dependencies, data integration effort, and maintenance obligations. At the same time, fleet upgrades that bring intelligence onto collection vehicles—such as automated cart handling, onboard verification, and route feedback—are expected to complement bin-side sensing and improve the reliability of dynamic scheduling. Organizations that align bin-side and vehicle-side data streams will be better positioned to optimize labor, fuel, and container lifecycles. The uncertainty here lies in the pace of fleet renewal and the degree to which smaller operators can fund vehicle-side upgrades alongside sensor deployments.
Strategic Recommendations for Decision-Makers
For manufacturers and technology vendors, the priority is to move beyond standalone hardware specifications and articulate how a solution reduces total operational cost while supporting compliance workflows. Product roadmaps that integrate fill-level sensing, route optimization, and auditable reporting into a coherent data architecture will be easier to position in municipal and industrial procurement processes. Vendors should also anticipate interoperability demands by designing open integration points for fleet systems, municipal platforms, and regional connectivity options rather than locking customers into closed stacks.
For investors, the market's growth trajectory is attractive, but value capture will favor companies with durable recurring revenue, demonstrable operational savings, and exposure to compliance-driven procurement. Due diligence should focus on unit economics across hardware, connectivity, and software components, as well as the strength of municipal and industrial references that validate route optimization and cost reduction claims. Portfolio positioning should account for the likelihood of consolidation around integrated data platforms and regional service relationships, especially where regulatory momentum is strongest.
Worldwide Smart Solar Urban Equipment Market
For procurement teams and operational leaders, the most effective adoption strategy starts with a narrowly defined use case—such as high-traffic public spaces, commercial facilities with irregular waste generation, or municipal corridors with high collection costs—and expands only after measurable savings and data reliability are proven. Evaluation criteria should include total cost of ownership, integration effort with existing fleet and reporting systems, and the vendor's ability to support evolving digital tracking and recycling accountability requirements. Building internal capability to interpret collection data and translate it into scheduling and labor decisions will determine whether smart waste collection delivers its intended operational leverage.
Detailed segmentation data, regional deployment patterns, and customized scenario analysis can help stakeholders narrow where to commit resources and how to sequence investments. Comprehensive research on the smart waste collection market is available for teams that need deeper breakdowns across product types, application segments, and regional dynamics, along with tailored guidance for procurement, partnership, and investment decisions.
PW Consulting Information & Electronics Research Center
For detailed analysis of this topic, please visit the official page: Smart Waste Collection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


