



Worldwide Shaving Foam Market: What 4.12% CAGR and $771.88M Reveal by 2032

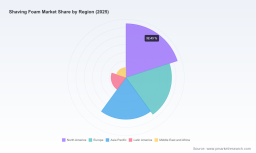
Navigating the Worldwide Shaving Foam Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The global shaving foam market sits at an inflection point. Valued at approximately $581.85 million in 2025, the sector has navigated a period of fluctuating demand since 2020, when baseline revenue hovered around $485.2 million. A contraction in 2021 to $472.08 million gave way to a resilient recovery, with annual revenue climbing to $522.76 million in 2022, $533.53 million in 2023, and $580.62 million in 2024. Projections indicate a steady expansion trajectory through 2032, with revenue expected to reach $771.88 million, supported by a compound annual growth rate of 4.12 percent across the 2026-2032 forecast window. This growth profile underscores a market that is neither collapsing under digital grooming alternatives nor exploding into hypergrowth, but rather maturing through incremental value creation, formulation upgrades, and channel realignment.
Despite this baseline stability, the industry faces structural headwinds that will define competitive outcomes over the next half-decade. First, regulatory scrutiny over chemical composition and aerosol propellants is intensifying. Notices issued in 2024 under California Proposition 65 highlighted the presence of listed substances such as Nitrous Oxide and Diethanolamine in select shaving foam products, prompting manufacturers to reassess formulation roadmaps and transparency standards. Simultaneously, the FDA and international cosmetic regulators continue to refine ingredient safety expectations, emphasizing good manufacturing practices and imposing tighter restrictions on certain preservatives and propellants. For brands built around aerosol convenience, compliance costs and reformulation timelines represent a non-trivial operational drag.
Second, the rise of sensitive-skin and moisturizing formulations is reshaping demand hierarchies. Consumers are increasingly treating shaving foam not as a disposable lubricant but as a skincare-adjacent product, prioritizing reduced irritation, hydration, and post-shave comfort. This shift pressures legacy mass-market lines to justify their positioning against premium, dermatologically informed alternatives, while also complicating inventory and production planning for suppliers that have historically optimized for high-volume, low-differentiation outputs. Third, distribution channel dynamics are fragmenting value capture. Hypermarkets and supermarkets continue to drive substantial volume, yet online retail and pharmacy channels are gaining share as consumers seek specialized formulations, subscription convenience, and expert recommendations. Brands that rely heavily on legacy retail shelf placement must contend with margin compression and channel conflict as digital and specialty routes mature.
Key Value Drivers
Three interlocking forces are reshaping the competitive and commercial landscape for shaving foam. The first is formulation technology and sustainability integration. Manufacturers are accelerating the transition toward plant-based surfactants and eco-friendly propellants, with adoption of recyclable packaging gaining momentum between 2023 and 2025. This is not merely a compliance exercise; it is a repositioning strategy. Brands that can deliver comparable glide, lather stability, and skin comfort while reducing irritants and environmental footprint are capturing credibility with increasingly informed buyers. The trend also intersects with cost optimization, as ingredient substitution programs are being paired with packaging redesign to control total landed cost while meeting retailer sustainability mandates.
The second driver is demand-side evolution in personal grooming behavior. Rising awareness of skin protection and grooming as part of broader self-care routines is expanding the addressable use case for shaving foam. Sensitive skin and moisturizing variants are leading this incremental demand, reflecting a consumer base that expects performance without compromise. For established players, this creates an opportunity to expand within existing customer bases by layering skincare benefits onto core shaving products. For newer entrants, it opens a pathway to differentiation through ingredient storytelling, dermatological endorsements, and targeted product architecture. The practical implication is that product portfolios must increasingly be evaluated through a dual lens: functional shaving performance and skin condition outcomes.
The third driver is regulatory and compliance pressure, which operates as both constraint and catalyst. Ingredient safety standards, aerosol propellant restrictions, and good manufacturing expectations are raising the bar for market entry and product iteration. While this burdens smaller players with formulation and documentation requirements, it also creates a moat for companies that have invested in regulatory competence, supply chain traceability, and quality systems. The regulatory environment is not uniform across regions, meaning that global brands must manage a patchwork of requirements while preserving brand cohesion. Companies that internalize compliance as a product development capability rather than a reactive function are better positioned to launch faster and with fewer regional friction points.
The fourth driver is strategic consolidation and channel leverage. Recent moves illustrate how incumbents are using acquisition, collaboration, and portfolio rationalization to sharpen positioning. Unilever's completion of its acquisition of Dr Squatch in mid-2025 expanded its premium men's grooming footprint and created potential synergies with shaving foam offerings. Procter & Gamble outlined a productivity-focused strategy in mid-2025 that emphasized grooming innovation alongside cost discipline, signaling a dual emphasis on value creation and operating efficiency. At the same time, Gillette's collaboration with the National Basketball Youth Mentorship Program in early 2024 highlighted how grooming education and product awareness can be embedded within community-focused initiatives. These developments reflect a broader pattern: incumbents are using scale, brand architecture, and purpose-led engagement to defend share and extend reach, while smaller brands pursue niche credibility and direct engagement.
Competitive Landscape and Leading Strategies
The market is characterized by a concentrated core and a long tail of specialized and regional players. The three-firm concentration ratio stands at 42.5 percent, while the five-firm concentration ratio reaches 58.8 percent, indicating that a relatively small group of multinationals controls a majority of revenue, but that considerable fragmentation remains outside the top tier. This structure shapes how strategy is executed: leading firms compete on portfolio breadth, formulation credibility, distribution leverage, and brand equity, while challengers compete on specificity, price-value positioning, and channel agility.
The Procter & Gamble Company occupies a central position through its Gillette shaving foam and gel portfolio, anchored in performance, skin protection, and innovation across aerosol and non-aerosol formats. Its scale enables sustained investment in product architecture for both sensitive and regular skin, while its grooming segment integration supports cross-product synergy and retail negotiation power. P&G's productivity-focused strategy underscores a discipline to fund innovation without sacrificing margin goals, a balance that is increasingly important as input costs and compliance demands rise.
Edgewell Personal Care competes through Schick, Wilkinson Sword, and Bulldog, emphasizing wet-shave comfort, sensitive skin formulations, and sustainable options. Its brand architecture spans mass and value segments, with Bulldog providing a differentiated personality lane that appeals to consumers seeking a less traditional grooming narrative. By balancing comfort claims with sustainability cues, Edgewell addresses both functional and emotional purchase drivers, an approach that helps defend share in a category where product perception often hinges on feel and after-effects.
Beiersdorf AG leverages NIVEA Men to connect shaving foam with moisturizing, cooling, and sensitive skin variants, drawing on dermatological expertise for global distribution. This positioning allows the brand to present shaving foam as part of a broader skin care logic, which is especially effective in markets where consumers respond to clinical credibility and familiar brand trust. Unilever PLC, through Axe and Dove Men+Care, targets younger consumers with grooming and skin care benefits in aerosol formats, using brand personality and lifestyle association to sustain relevance. L'Oréal Groupe contributes a skincare technology angle, integrating hydration and protection into men's grooming lines and benefiting from its broader cosmetics innovation pipeline.
Along the value and specialty edges, Colgate-Palmolive Company supplies shaving foams within its personal care portfolio, focusing on everyday grooming needs and channel reach. Perio, Inc. (Barbasol) positions Barbasol and Pure Silk as affordable, high-value aerosol products manufactured in the USA, a strategy that resonates with price-conscious consumers and retail buyers seeking reliable supply. Harry's Inc. combines modern formulations with a direct-to-consumer model, emphasizing quality and sustainability as differentiation levers. The Cremo Company has gained traction through premium shaving creams with natural ingredients, thick lather, and skin conditioning, illustrating how product sensory attributes can drive share in a category where perceived quality often translates into repeat usage. DORCO Co., Ltd. and VI-John Group extend the landscape into value-oriented grooming for domestic and export markets, with DORCO pairing foams with razors and VI-John targeting emerging markets through varied scent and skin-type formulations. Bombay Shaving Company and Kao Corporation round out the field with premium-plus and region-specific approaches, the former emphasizing natural positioning for Indian and select international markets, the latter aligning with local preferences for mild and effective formulations.
PW Consulting
The landscape is evolving along three trajectories. Consolidation is likely to continue as larger players acquire niche brands or grooming platforms to fill portfolio gaps and accelerate premiumization, as seen in recent acquisition activity. Differentiation is intensifying around skin sensitivity, sustainability, and sensory performance, which raises the stakes for formulation and claims substantiation. At the same time, new entrants and regional specialists are carving out defensible positions through direct engagement, localized product design, and channel strategies that bypass traditional shelf dependence. The net effect is a market where scale provides cost and distribution advantages, but where relevance increasingly depends on product credibility and consumer trust.
Foaming Creamer Market
Future Trajectory: 2026 to 2032 Outlook
Looking ahead, the market is poised to expand steadily toward the high-$700 million range by 2032, with the 4.12 percent CAGR reflecting incremental rather than disruptive growth. Several trends will shape value creation during this period. First, sensitive-skin and moisturizing formulations will continue to outpace generic mass variants in growth intensity, not because consumers are abandoning basic options, but because premiumization within core usage is becoming the primary growth engine. Brands that can deliver demonstrable comfort, reduced irritation, and post-shave skin benefits will capture disproportionate share of wallet.
Second, sustainability and compliance will converge as a product requirement rather than a marketing add-on. The shift toward plant-based surfactants, recyclable packaging, and reduced-irritant ingredient profiles is becoming embedded in retailer expectations and consumer preferences alike. Companies that integrate these attributes into core production processes will face fewer launch delays and fewer regional friction points, while laggards risk reputational and operational exposure. Third, channel reconfiguration will persist, with online retail and pharmacy channels gaining structural share as consumers seek specialized products and expert guidance. This will pressure traditional mass retail dependence and reward brands with strong digital commerce capabilities, clear product differentiation, and effective subscription or replenishment models.
The commercial opportunities are evident. Portfolio expansion into hybrid shaving-skincare products, targeted sensitive-skin lines, and refill or recycling programs can unlock incremental revenue while aligning with evolving consumer expectations. Strategic partnerships and selective acquisitions can accelerate premium positioning and geographic reach. For suppliers, formulation expertise and sustainable packaging capabilities are becoming differentiators in their own right, creating upstream value beyond brand marketing. The principal uncertainties are regulatory variability across markets, input cost volatility for surfactants and propellants, and the risk that premiumization stalls if economic pressures compress discretionary spending. Brands that manage these risks through flexible formulation pipelines, diversified sourcing, and disciplined pricing architecture will be better equipped to convert trend momentum into durable share gains.
Beard Shave Formula Market
Actionable Guidance for Decision-Makers
For manufacturers, the priority is to align product architecture with the sensitive-skin and sustainability trajectory while protecting operational discipline. That means investing in formulation pipelines that can satisfy both performance expectations and tightening regulatory standards, and designing packaging and propellant strategies that reduce long-term compliance and cost exposure. Portfolio reviews should prioritize variants with credible skin-care benefits and recyclable or reduced-impact packaging, and development cycles should anticipate regional ingredient rules rather than react to them.
For investors, the focus should be on differentiation durability and channel resilience. Companies with strong brand equity in premium or sensitive-skin segments, robust formulation capabilities, and the ability to operate across both physical retail and online channels are better positioned to defend margins in a market where concentration remains high but fragmentation persists at the edges. Acquisition and partnership activity will likely continue to reshape portfolios, so evaluating target brands for formulation credibility, direct-to-consumer traction, and sustainability readiness can reveal value that is not immediately visible in headline revenue figures.
For procurement and retail stakeholders, the strategic task is to ensure assortment clarity and supply reliability. As product differentiation increases, shelf and digital navigation become more complex, making it important to select partners with consistent quality, transparent ingredient positioning, and packaging that supports sustainability commitments. Suppliers that can demonstrate stable sourcing for surfactants and propellants, along with credible claims substantiation, will reduce assortment risk and improve consumer trust. In a market where growth is steady but competitive intensity is rising, timely access to detailed segmentation data, regional dynamics, and company-level strategy updates is essential for shaping investment, product, and channel decisions with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Shaving Foam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


