



Household Automatic Soap Dispenser Market: Why 8.84% CAGR Changes Everything

The Worldwide Household Automatic Soap Dispenser Market: Strategic Trends and Commercial Opportunities Through 2032
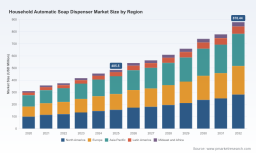
The global household automatic soap dispenser market has transitioned from a pandemic-driven novelty to a structural fixture in modern home hygiene infrastructure. With a base year valuation of 2025 establishing a robust revenue foundation and projections extending through 2032, the sector demonstrates sustained expansion momentum. Historical performance from 2020 through 2025 reflects a consistent upward trajectory, driven by accelerated adoption cycles and evolving consumer expectations around contactless sanitation. Forecasts indicate the market will continue scaling at a compound annual growth rate of 8.84%, translating into billions of dollars in cumulative revenue across the forecast horizon. This growth is not merely a rebound effect but rather the result of entrenched behavioral shifts, product maturation, and broader integration into residential design standards.
Despite the positive momentum, the industry navigates several structural inflection points. First, price sensitivity continues to pressure manufacturers as premium pricing strategies encounter resistance in cost-conscious segments, forcing companies to balance innovation investments with accessible tiered pricing models. Second, the category faces functional saturation in baseline sensor-driven dispensing, where incremental hardware improvements yield diminishing differentiation unless paired with meaningful user experience enhancements. Third, regulatory and classification frameworks are tightening around electronic consumer goods, influencing import procedures, material compliance, and end-of-life considerations. These dynamics create both friction and opportunity: firms that navigate compliance efficiently while embedding sustainable and convenient features into core product architecture are positioned to capture disproportionate share as the market expands. Understanding how these forces interact is essential for stakeholders evaluating entry points, expansion strategies, or portfolio reallocation within the broader home hygiene ecosystem.
Key Drivers Shaping Market Evolution
Technology Innovation and Product Refinement
The transition from basic infrared detection to refined sensing algorithms, improved battery management, and modular refill systems represents a meaningful shift in product value propositions. Recent product cycles reflect a clear emphasis on usability and durability, with multiple 2026 model upgrades introducing USB charging, adjustable dispensing levels, and enhanced waterproofing for both countertop and wall-mounted configurations. These improvements address long-standing consumer friction points around maintenance, battery replacement, and inconsistent flow control. Independent evaluations have further validated the importance of design integration, with rechargeable sensor pump dispensers ranking prominently in household use assessments based on aesthetic coherence, operational reliability, and battery efficiency. For manufacturers, the strategic implication is clear: hardware differentiation increasingly depends on subsystem performance and user experience refinement rather than stand-alone sensor presence. Companies that invest in feedback loops connecting consumer usage patterns with iterative design adjustments can reduce return rates, enhance satisfaction, and reinforce repeat purchase cycles across refill and accessory categories.
Policy, Regulatory Environment, and Classification Dynamics
Regulatory classification and trade policy continue to shape go-to-market pathways, particularly for electronically powered hygiene appliances. Customs rulings have classified battery-operated automatic soap dispensers under established mechanical appliance categories for liquid dispersion, a designation that influences tariff treatment, documentation requirements, and cross-border logistics planning. While classification clarity can streamline compliance, it also underscores the need for manufacturers and distributors to maintain accurate product specifications, material declarations, and technical documentation aligned with jurisdictional expectations. Beyond trade mechanics, sustainability expectations are increasingly embedded in procurement criteria and consumer preferences, prompting a shift toward recycled plastics and eco-friendly material inputs in dispenser construction. Firms that proactively align product architecture with environmental sourcing standards and transparent compliance practices reduce exposure to regulatory scrutiny while strengthening brand positioning in markets where sustainability has become a baseline purchase consideration rather than a peripheral feature.
Demand-Side Shifts in Household Hygiene Behavior
Demand patterns illustrate a durable preference for touchless hygiene solutions in bathroom and kitchen environments, where infrared sensors and adjustable volume controls have become expected rather than exceptional. This behavior is reinforced by heightened awareness of surface contact transmission and a broader cultural emphasis on convenience-oriented sanitation routines. Households increasingly view automatic dispensers as integrated components of vanity and kitchen organization, favoring products that combine discreet aesthetics with reliable operation. The demand environment also favors multi-use flexibility, with consumers evaluating dispensers based on compatibility with different soap formulations, ease of refilling, and suitability for family-scale usage. Manufacturers responding to these preferences are expanding product lines that balance tactile design with functional adaptability, recognizing that the purchase decision is increasingly influenced by how seamlessly the device integrates into daily routines rather than by standalone hygiene messaging. This evolving demand profile rewards product ecosystems that reduce friction across the ownership lifecycle.
Supply Chain and Cost Structure Pressures
Cost dynamics remain a central consideration as materials, electronics, and logistics inputs fluctuate across regions. Manufacturers are increasingly incorporating recycled plastics and alternative material blends to mitigate raw material volatility while aligning with sustainability expectations. At the same time, the proliferation of USB charging and enhanced waterproofing features introduces new component requirements that can affect bill-of-materials complexity. Supply chain resilience has therefore become a strategic differentiator: companies that diversify sourcing, standardize modular components, and optimize assembly workflows can maintain margin stability while adapting to regional demand shifts. Distribution pathways are also evolving, with online retail channels capturing a dominant share of household purchases and amplifying the importance of packaging efficiency, direct-to-consumer fulfillment, and reliable inventory turnover. In this environment, cost leadership alone is insufficient; sustained advantage depends on balancing input efficiency with product reliability and channel responsiveness.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a fragmented but increasingly specialized participant base, with firms pursuing distinct positioning strategies across design, durability, sustainability, and distribution. Stern Engineering Ltd. has built a reputation around premium touchless dispensers for residential and commercial settings, emphasizing sensor innovation and durable hands-free sanitary products. Hokwang Industries Co., Ltd. operates as an ISO-certified manufacturer offering automatic dispensers alongside complementary bathroom fixtures, with export reach across numerous countries and a focus on high-quality touchless models for household and commercial use. GOJO Industries, Inc. continues to leverage its hygiene brand equity through touch-free dispenser lines that highlight sustainable design elements for household and institutional applications, reinforcing a long-term sustainability narrative. Simplehuman, LLC occupies a high-end household niche with rechargeable sensor dispensers that emphasize aesthetics, battery efficiency, and touchless operation for kitchen and bathroom environments. Other participants, including Bradley Corporation, American Specialties, Inc., Bobrick Washroom Equipment, Inc., Sloan Valve Company, Ningbo Power (Joro), AIKE, and Hsumao Industrial Co., Ltd., extend the competitive field across commercial-grade durability, multi-feed systems, integrated plumbing compatibility, hospitality customization, and value-oriented household offerings.
PW Consulting
Several strategic patterns emerge across this landscape. First, premium design-oriented players are using independent validation and product testing visibility to reinforce credibility, as seen in recent rankings that highlight aesthetic and reliability performance for household models. Second, sustainability-oriented positioning is becoming a recurring theme, with manufacturers promoting enhanced eco-friendly design features and recycled material usage to differentiate beyond baseline functionality. Third, product cycle acceleration is evident, with multiple upgrades in early 2026 emphasizing USB charging, adjustable dispensing, and improved waterproofing, signaling a market that rewards rapid iteration and responsiveness to consumer feedback. These dynamics suggest a competitive environment where advantage is increasingly defined by the integration of design, compliance, and user experience rather than by category ownership alone.
The market structure is also showing signs of both consolidation pressure and segmental divergence. Larger hygiene and bathroom fixture players benefit from broader distribution, cross-selling opportunities, and institutional relationships, while specialized designers and regional manufacturers compete through targeted value propositions and customization flexibility. New entrants and private-label activity continue to intensify price competition in mainstream segments, yet they also expand total category availability and normalize touchless hygiene as a standard household expectation. Over time, this pattern is likely to encourage selective consolidation among mid-tier manufacturers while enabling niche leaders to maintain differentiation through design, sustainability, and service integration. For stakeholders, the strategic question is less about who leads today and more about which capability sets will determine resilience as the category matures.
Forward-Looking Trends and Strategic Implications
Looking ahead to the next three to five years, the household automatic soap dispenser market is likely to be shaped by three interlocking trends. First, product ecosystems will increasingly favor smart-adjacent features that enhance usability without overcomplicating the core experience. Adjustable dispensing, improved battery architectures, and better water resistance are early indicators of a trajectory in which users expect tighter control, longer service intervals, and more consistent performance across environments. Commercial opportunity lies in modular designs that allow incremental feature upgrades while preserving baseline reliability, enabling manufacturers to serve both entry-level and premium segments with shared platforms.
Second, sustainability and material transparency will move from differentiator to baseline expectation. As recycled plastics and eco-friendly construction become more prevalent, procurement decisions in both retail and institutional settings will increasingly weigh environmental sourcing alongside price and performance. This creates opportunities for brands that can substantiate material claims, streamline compliance documentation, and align product design with longer-term circular economy considerations. Firms that treat sustainability as an integrated design parameter rather than a surface-level feature will be better positioned to retain trust and defend margins.
Dispenser Pump Market
Third, channel dynamics will continue to reward manufacturers that can synchronize product availability with digital purchasing behavior while maintaining strong retail partnerships. Online channels already account for a substantial share of household purchases, and this distribution emphasis places a premium on packaging efficiency, predictable inventory flow, and clear product specifications that reduce return risk. At the same time, specialty stores and hypermarkets remain relevant for trial, comparison, and immediate availability in certain regions. The most resilient players will likely be those that can manage omnichannel consistency without overinvesting in redundant go-to-market structures. These trends carry inherent uncertainty, including potential shifts in material costs, regulatory classification updates, and varying regional adoption rates. Companies that monitor these variables closely and maintain flexible product roadmaps will be better equipped to adapt without sacrificing strategic focus.
Actionable Guidance for Decision-Makers
For manufacturers, the priority is to align product roadmaps with the capabilities that matter most in a maturing category: reliable sensor performance, improved battery and charging architectures, adjustable dispensing, and material choices that support sustainability claims without compromising durability. Developing modular platforms can reduce time-to-market for incremental upgrades while preserving margin discipline. Emphasizing clear documentation for classification and material compliance will also strengthen supply chain predictability and reduce friction in cross-border distribution.
For investors, the most relevant signals are not simply top-line growth but the underlying drivers of share shifts: design credibility, sustainability positioning, channel execution, and the ability to iterate quickly without eroding quality. Companies that demonstrate consistent product validation, disciplined cost management, and coherent brand differentiation are better positioned to capture value as the market broadens. Portfolio evaluation should account for segmentation nuance, since countertop and wall-mounted formats, as well as foaming, liquid, and spray variants, serve distinct usage contexts and purchasing motivations.
For procurement and retail stakeholders, selection criteria should extend beyond unit price to include refill compatibility, maintenance burden, waterproofing and battery reliability, and alignment with consumer preferences for touchless hygiene in kitchen and bathroom settings. Structured evaluation frameworks that weigh total cost of ownership and user satisfaction can reduce downstream returns and strengthen category trust. As the market continues to evolve, timely access to detailed segmentation data, competitive tracking, and customized scenario planning becomes increasingly valuable for converting category momentum into measurable business outcomes.
Automatic Hand Dryers Market
For detailed analysis of this topic, please visit the official page: Worldwide Household Automatic Soap Dispenser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


