



Markets Beyond CAC 728.31: Strategic Shifts Driving 5.15% Emamectin Benzoate Growth

Strategic Trends and Commercial Opportunities in the Global Emamectin Benzoate Market
Market Overview and Core Challenges
The global market for emamectin benzoate has demonstrated consistent expansion over the past half-decade, establishing itself as a critical component within the broader crop protection landscape. From a base valuation of approximately 395.2 million USD in 2020, the market has progressed through a period of accelerated growth, reaching 481.93 million USD by 2023. Although 2024 saw a temporary contraction to 454.47 million USD, the trajectory rebounded strongly, with 2025 valuations climbing to 512.45 million USD. This pattern indicates a market that is resilient despite short-term volatility, driven by fundamental agricultural needs. Looking ahead, the forecast period from 2026 to 2032 suggests a steady upward path, with valuations projected to move from 533.7 million USD in 2026 to 728.31 million USD by 2032. This growth trajectory implies a compound annual growth rate of 5.15 percent, signaling a mature yet expanding market phase where incremental gains are driven by efficiency and regional demand rather than purely novel adoption.
Despite the positive revenue outlook, the industry stands at a critical juncture defined by environmental scrutiny and supply chain volatility. One of the most significant challenges is the tightening regulatory framework surrounding environmental safety, particularly in aquaculture-intensive regions. Recent implementations of Environmental Quality Standards (EQS) in sediment, such as those introduced in Scotland, highlight a growing regulatory focus on protecting benthic populations from agricultural discharges. This shift forces manufacturers and formulators to reconsider application methods and runoff management, potentially increasing compliance costs and limiting certain use cases in sensitive areas.
A second major challenge involves price instability linked to upstream raw material availability and inventory levels. The technical grade material, synthesized primarily from abamectin B1a/B1b, has experienced notable price fluctuations. For instance, domestic prices in China saw a significant recovery in 2024, rising by over 24 percent among top insecticides, driven by reduced inventories against ongoing demand. However, retail prices monitored in early 2026 showed a decrease from higher peaks, indicating a market sensitive to inventory corrections and regional supply dynamics. This volatility complicates budgeting for agricultural distributors and farmers, creating uncertainty in procurement planning.
The third key challenge is the concentration of market power among a limited number of key players. With a CR3 concentration ratio of 42.5 percent and a CR5 of 61.8 percent, the market is moderately consolidated. While this suggests stability among leading incumbents, it also raises barriers to entry for new manufacturers and places pressure on smaller formulating companies to differentiate through niche applications or specific regional partnerships. Navigating this concentration requires strategic alignment with either major integrated players or specialized technical producers to secure reliable supply chains.
Key Drivers of Market Change
Technological Innovation and Formulation Advancements
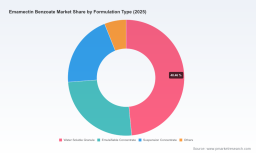
Innovation in formulation technology remains a primary driver for market value retention and growth. The shift towards user-friendly and environmentally safer delivery systems is evident in the market mix. Water soluble granules currently represent the largest share of formulation types, capturing significant value due to their ease of handling and reduced exposure risks compared to older solvent-based formats. However, emulsifiable concentrates and suspension concentrates continue to hold substantial market share, catering to specific application equipment and crop requirements. The development of dual-action products that combine rapid knockdown with residual control is a notable technological leap. Companies are increasingly focusing on integrating emamectin benzoate into broader portfolios that address resistance management, ensuring that the active ingredient remains effective against lepidopteran pests over time. This focus on performance longevity extends the commercial lifecycle of products containing the active ingredient.
Policy and Regulatory Environment
The regulatory landscape is acting as both a constraint and a driver for differentiation. While environmental standards in regions like Scotland and Norway are tightening regarding sediment quality and aquaculture discharges, other regions are focusing on registration efficiency and residue limits for food crops. In major agricultural economies across Asia Pacific and Latin America, regulatory frameworks often support the continued use of effective biologicals and chemistries against resistant pest populations. The divergence in regulatory strictness creates a complex compliance map. For global manufacturers, this means that regulatory expertise is a competitive advantage. Companies that can navigate varying environmental quality standards while maintaining efficacy are better positioned to capture value in high-growth regions. Furthermore, regulations pushing for lower application rates due to higher potency formulations can drive demand for premium-priced, high-purity technical materials.
PW Consulting
Demand-Side Shifts in Agriculture
On the demand side, the pressure to secure global food supplies against pest infestation continues to underpin volume requirements. Vegetables and field crops remain the primary application areas, reflecting the need for robust protection in high-value edible crops. Fruit cultivation also represents a significant demand node, where quality standards for export dictate strict pest control measures. Consumer behavior is indirectly influencing this sector; as demand for residue-free produce grows, there is a corresponding need for chemistries that offer high efficacy at low dosage rates, reducing the chemical load on the final product. Emamectin benzoate fits this profile when used according to integrated pest management protocols. Additionally, the ornamental plant sector, while smaller in volume, drives demand for aesthetic quality, sustaining usage in niche markets where visible pest damage is unacceptable.
Supply Chain and Cost Structure Dynamics
Supply chain resilience has become a critical differentiator following recent global disruptions. The synthesis of emamectin benzoate relies on specific upstream starting materials, and any bottleneck in the production of abamectin derivatives can ripple through the entire value chain. Recent data points indicate that China remains a pivotal hub for technical material production, with domestic pricing serving as a bellwether for global cost structures. The recovery of technical prices in 2024 due to reduced inventories suggests that supply tightness can quickly reverse cost advantages. For downstream formulators, securing long-term supply agreements or diversifying sourcing from multiple technical manufacturers is becoming a standard risk mitigation strategy. Cost structures are further influenced by logistics and raw material energy costs, making operational efficiency in manufacturing a key determinant of margin preservation.
Worldwide Insect Growth Regulators Market
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of large multinational corporations and specialized chemical manufacturers. Major global players such as Syngenta AG and FMC Corporation maintain strong positions through integrated agricultural solutions portfolios. Syngenta, headquartered in Basel, leverages its global registration network and integrated formulation offerings to control lepidopteran pests across diverse crop systems. FMC Corporation, based in Philadelphia, competes by emphasizing dual-action products that provide both rapid knockdown and residual control, appealing to farmers seeking immediate and lasting protection. BASF SE contributes to the landscape by supplying technical material and formulated insecticides focused on broad-spectrum control, utilizing its extensive R&D infrastructure to optimize product performance.
On the other side of the landscape, Chinese manufacturers play a crucial role in the supply of technical concentrate and formulations. Companies like Hebei Veyong Bio-Chemical, Zhejiang Hisun Chemical, and Hailir Pesticides and Chemicals Group are active producers with capacities supporting global distribution. Shandong Qilu King-Phar Pharmaceutical and Awiner Biotech also contribute to the technical material pool, often focusing on quality certifications required for international supply. POMAIS, operating as Shanghai AgroRiver Chemical Co., Ltd., distinguishes itself by offering specific formulations like 5% WDG with ISO 9001 certification and customized packaging for export. ADAMA Agricultural Solutions Ltd., based in Israel, rounds out the competitive field by offering emamectin benzoate-containing products tailored for tough pests, leveraging its regional expertise in agricultural solutions.
The strategic positioning of leaders varies significantly. Multinationals tend to focus on brand equity, comprehensive pest management solutions, and regulatory stewardship in regulated markets. In contrast, technical manufacturers often compete on cost efficiency, production capacity, and the ability to customize formulations for specific regional needs. This bifurcation creates a dynamic where value capture is split between those controlling the end-product market and those controlling the technical supply. Recent developments highlight this dynamic; for example, industry data from early 2025 noted a price recovery in China driven by inventory reductions, benefiting technical suppliers. Simultaneously, ADAMA highlighted product performance in full-year results, emphasizing the value of efficacy in maintaining market share for formulators.
Market evolution suggests a trend towards further consolidation among formulators who need to secure supply, while technical manufacturers may face pressure to differentiate through purity and consistency rather than price alone. New entrants face high barriers due to regulatory registration costs and the established relationships between key suppliers and global distributors. However, opportunities exist for companies that can bridge the gap between technical production and specific regional formulation needs, particularly in high-growth areas where local registration support is valuable. The concentration ratios indicate that while the top five players hold a majority share, there is enough fragmentation in the remaining market to allow for strategic niche positioning by agile manufacturers.
Future Trends and Predictions
Looking toward the 2027 to 2031 window, several key trends are likely to shape the commercial landscape. First, environmental compliance will increasingly dictate market access. As sediment quality standards and aquaculture discharge regulations mature in Europe and potentially influence standards in other regions, products and formulations that minimize environmental runoff will gain preference. This could drive innovation in formulation types that reduce leaching, potentially shifting value towards suspension concentrates or specialized granules in regulated zones. Companies that proactively adapt to these standards will secure a competitive advantage in premium markets.
Second, price volatility is expected to remain a feature of the market, driven by the cyclical nature of technical material inventories and raw material availability. The observed swing from technical price recoveries to retail price adjustments suggests that market participants must remain agile. Forecasting models indicate continued growth in market size, but the path will not be linear. Suppliers who can offer stability through long-term contracts or stock buffering will be valued highly by downstream customers facing their own margin pressures. The divergence between technical costs and retail pricing offers opportunities for arbitrage and strategic inventory management.
Third, the demand structure will likely continue to favor high-value crops. While field crops provide volume, vegetables and fruits offer higher margin potential for pesticide suppliers. The growth in these segments will be supported by the need for quality assurance in global food trade. However, uncertainty remains regarding the pace of regulatory tightening in key export markets. If residue limits become stricter or specific environmental restrictions expand, certain applications could face headwinds. Nevertheless, the fundamental need for lepidopteran control in major staple and cash crops provides a solid floor for demand, ensuring that the market continues to expand even as the mix of applications evolves.
Strategic Recommendations for Decision Makers
For manufacturers and suppliers, the priority should be securing supply chain resilience while investing in formulation differentiation. Given the concentration of key players and the volatility in technical pricing, diversifying sourcing options and maintaining strategic inventory levels can mitigate risk. Manufacturers should also evaluate opportunities to align with regulatory trends, such as developing formulations that meet emerging environmental standards in aquaculture and sensitive ecological zones. This proactive stance can open doors to markets where competitors are slowed by compliance hurdles.
Investors assessing this sector should focus on companies with strong technical production capabilities in key regions like China, as well as formulators with robust distribution networks in high-growth areas such as Asia Pacific and Latin America. The moderate market concentration suggests that while leaders are secure, there is room for value creation in specialized segments. Monitoring price trends and inventory levels in the upstream technical market will provide early signals of margin shifts for downstream entities. Understanding the regulatory trajectory in regions like Europe and North America is also essential for evaluating long-term risk exposure.
For procurement teams and agricultural buyers, the focus should be on total cost of ownership rather than just unit price. With price fluctuations observed in both technical and retail markets, locking in supply through partnerships or contracts during stable periods can protect against volatility. Evaluating products based on efficacy, resistance management profiles, and environmental compliance will ensure sustainable operations. Accessing detailed market intelligence on regional pricing, regulatory changes, and competitor activity is crucial for making informed procurement decisions. Comprehensive data sets and customized analysis allow stakeholders to navigate these complexities with greater confidence.
Deltamethrin Market
For detailed analysis of this topic, please visit the official page: Worldwide Emamectin Benzoate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


