



Worldwide Femtosecond OPA Market: Why 6.91% CAGR Reshapes Growth Beyond 2032

Strategic Trends and Commercial Opportunities in the Worldwide Femtosecond OPA Market
Market Overview and Core Challenges
The global femtosecond optical parametric amplifier (OPA) market has established itself as a critical enabler for advanced photonic applications, bridging the gap between fixed-wavelength laser sources and the broad tunability required for cutting-edge research and industrial processes. Based on current valuation metrics, the market reached approximately 242.45 million USD in 2025, reflecting a compound annual growth rate of 6.91 percent projected through 2032. This trajectory suggests a steady expansion from the 172.85 million USD baseline observed in 2020, indicating sustained demand despite macroeconomic fluctuations. The forecast period extending to 2032 points toward a valuation approaching 386.78 million USD, signaling a mature yet growing ecosystem where technological capability increasingly dictates market share.
Despite this positive revenue outlook, the industry stands at a critical juncture defined by several structural challenges. One primary hurdle is the dependency on specific nonlinear crystal materials. The performance, tuning range, and efficiency of femtosecond OPA systems rely heavily on the availability and quality of crystals such as BBO, LBO, KTA, or emerging materials like BaGa4Se7. Supply chain volatility in these specialized components can directly impact production timelines and system performance specifications, creating vulnerabilities for manufacturers who lack diversified sourcing strategies.
Another significant challenge lies in the pump laser infrastructure. The primary hardware bottleneck for high-power femtosecond OPAs is the availability of stable, high-average-power Yb-based femtosecond pump lasers, often requiring power levels between 50 and 300 W with excellent beam quality and synchronization capabilities. As applications demand higher repetition rates and average powers, the integration complexity between the pump source and the OPA stage increases, requiring tighter engineering tolerances and more sophisticated thermal management solutions.
Worldwide Solid State Mode-Locked Picosecond Lasers Market
Furthermore, the regulatory landscape introduces an element of uncertainty. Export controls on advanced laser technologies, including certain high-power ultrafast systems, may apply under international frameworks for dual-use items. These controls affect global supply chains for research-grade femtosecond OPAs, potentially limiting market access in certain regions or complicating cross-border collaborations. While femtosecond OPA systems are primarily used in controlled laboratory and research environments under general laser safety standards such as IEC 60825-1, the lack of a specific industry-wide ISO standard unique to femtosecond OPAs means manufacturers must navigate a patchwork of regional safety and compliance requirements.
Key Drivers of Market Growth
The expansion of the femtosecond OPA market is propelled by a convergence of technological innovation, evolving application demands, and shifts in the supply chain dynamics. Understanding these drivers is essential for stakeholders looking to position themselves advantageously within the value chain.
Technological Innovation and Performance Frontiers
The quest for broader tunability and higher pulse energies continues to drive product development. Recent advancements demonstrate a clear trend toward compact, high-repetition-rate systems that maintain sub-50 fs pulse durations. For instance, the launch of the FemtoTune series femtosecond OPA in July 2025 highlighted the industry's push toward integrating high-repetition rates up to 100 kHz with broad tunability ranges extending from visible to gapless mid-IR. Similarly, updates to existing platforms in early 2026 have emphasized supporting high pump powers and automated operation, reflecting a maturity in design that prioritizes stability and ease of integration. These innovations are not merely incremental; they expand the accessible parameter space for users, enabling experiments and processes that were previously constrained by source limitations.
Demand-Side Shifts in Research and Industry
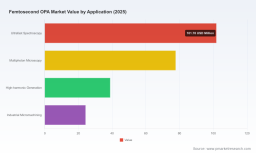
Demand is being reshaped by the specific needs of ultrafast spectroscopy, multiphoton microscopy, and high-harmonic generation. In spectroscopy, the ability to tune across wide spectral ranges allows researchers to probe specific molecular transitions with greater precision. In microscopy, particularly multiphoton and three-photon imaging, the spectral flexibility of OPAs enables deeper tissue penetration and reduced phototoxicity. The industrial micromachining sector also contributes to demand, albeit from a smaller base, as manufacturers seek precise ablation capabilities that rely on specific wavelengths achievable through OPA technology. The shift from purely academic research to applied industrial settings is broadening the customer base beyond traditional laser physics laboratories.
Supply Chain and Component Specialization
The supply side is characterized by a high degree of specialization, particularly regarding nonlinear optics and pump laser synchronization. The critical role of nonlinear crystals means that companies capable of securing high-quality materials or developing proprietary crystal solutions gain a competitive edge. Additionally, the reliance on stable Yb-based femtosecond pump lasers creates a symbiotic relationship between OPA manufacturers and pump laser vendors. This interdependency encourages integrated solutions where the OPA is designed to work seamlessly with specific laser platforms, reducing integration friction for the end user. However, it also means that bottlenecks in pump laser production can cascade through the OPA market.
Regulatory and Safety Environment
While not a direct growth driver in the traditional sense, the regulatory environment shapes market behavior. The absence of a unique ISO standard for femtosecond OPAs means manufacturers must adhere to general laser safety standards, which influences product design regarding enclosure, interlocks, and beam delivery. Moreover, export controls on dual-use items require companies to maintain rigorous compliance protocols. For global players, navigating these regulations without stifling innovation is a delicate balance that can affect market entry strategies and partnership formation.
Competitive Landscape and Leading Strategies
The market exhibits a moderate level of concentration, with a significant portion of revenue captured by a handful of established players. This concentration suggests that barriers to entry remain high, primarily due to the technical complexity of designing stable, tunable systems and the established relationships required to penetrate key customer segments.
PW Consulting
Leading companies have adopted distinct strategic positions to differentiate themselves. Light Conversion, based in Vilnius, Lithuania, has positioned itself as a dominant provider through its ORPHEUS series, offering tunable UV to MIR coverage with high repetition rates up to 2 MHz. Their strategy emphasizes high stability for Yb-pumped systems and the ability to attach compactly to CARBIDE/PHAROS lasers, targeting spectroscopy, microscopy, and micromachining applications. This integration-focused approach reduces system complexity for the user.
APE Angewandte Physik und Elektronik GmbH, located in Berlin, Germany, focuses on robustness and automation. Their AVUS femtosecond OPA supports up to 50 W pump power with versions for varying pulse durations, tunable across broad ranges such as 650 nm to 2.5 μm or 210 nm to 11 μm. The use of an air-cooled monolithic design targets thermal stability and automation, appealing to users who prioritize long-term reliability and minimal maintenance in high-power scenarios.
Coherent, headquartered in Santa Clara, California, leverages its extensive portfolio with integrated solutions like the OPerA Solo. This one-box, computer-controlled system tunes from 240 nm to 20 μm for kHz amplifiers, extending tuning for spectroscopy and microscopy. Their strategy involves integrating OPAs into broader ultrafast laser ecosystems, such as pairing with Monaco or Astrella systems, to offer a turnkey experience for high-end research facilities.
EKSPLA, also from Vilnius, competes through specialized series like FemtoTune, offering sub-50 fs pulses at up to 100 kHz. Their focus on tunable ranges including extensions to UV-VIS and gapless mid-IR up to 10,000 nm, pumped by industrial FemtoLux lasers, targets users needing specific spectral coverage for ultrafast spectroscopy and imaging.
Spectra-Physics (MKS Instruments) maintains a strong presence in the microscopy and optogenetics sectors with Spirit-NOPA tunable non-collinear optical parametric amplifiers. Optimized for Spirit HE/One ultrafast lasers, they deliver pulses from less than 30 fs to less than 100 fs tunable in VIS-IR, catering to applications like multiphoton microscopy where pulse duration and stability are critical.
Amplitude, based in Bordeaux, France, differentiates with the Mango optical parametric amplifier platform, offering tuning from 210 nm to 11,000 nm from a single port with consistent polarization. Supporting up to 2 MHz and featuring dispersion management, this platform targets complex imaging applications like 3P imaging and time-resolved spectroscopy, emphasizing versatility and polarization control.
Class 5 Photonics, headquartered in Hamburg, Germany, specializes in OPCPA systems incorporating OPA stages. Their White Dwarf series provides tunable femtosecond pulses, including high-power few-cycle options pumped by industrial Yb lasers. This positions them at the intersection of high-power physics and application-driven needs such as attosecond science and high-harmonic generation.
Ultrafast Lasers Market
The market landscape is evolving through both consolidation and specialization. While established players strengthen their positions by expanding spectral ranges and pulse repetition rates, there is room for new entrants who can solve specific bottlenecks, such as reducing size, weight, and power consumption for field-deployable systems or improving efficiency in specific mid-IR regions. The trend suggests a move toward more integrated, turnkey solutions where the distinction between the pump laser and the OPA blurs, offering customers greater ease of use.
Future Trends and Predictions
Looking ahead to the next three to five years, several key trends are likely to shape the trajectory of the femtosecond OPA market. These trends present both opportunities for growth and risks that require strategic mitigation.
Trend 1: Convergence of High Power and High Repetition Rates
As applications in microscopy and industrial processing demand more signal or faster processing, the pressure to increase both average power and repetition rates will intensify. Systems that can deliver high pulse energies at multi-kHz or MHz repetition rates without compromising beam quality or tunability will capture significant market share. This trend creates opportunities for manufacturers who can solve thermal management issues in nonlinear crystals and optimize pump laser synchronization. However, it also raises the risk of component failure or degradation if thermal loads are not adequately managed.
Trend 2: Expansion into New Spectral Regimes
While visible and near-IR tunability is well-established, there is growing interest in the mid-IR and deep-UV regions for specific molecular fingerprinting and high-harmonic generation applications. Technologies that enable gapless coverage or efficient conversion into these harder-to-reach spectral ranges will find niche but high-value markets. Emerging crystal materials like BaGa4Se7 may play a crucial role here. The risk lies in the cost and availability of exotic crystals, which could limit scalability if supply chains are not secured.
Trend 3: Automation and User Accessibility
The democratization of advanced laser techniques is driving demand for systems that require less specialized knowledge to operate. Future OPAs are likely to feature more automated alignment, tuning, and monitoring capabilities, reducing the barrier to entry for non-expert users. This shift expands the potential customer base to smaller laboratories or industrial quality control teams. The uncertainty involves balancing automation with the flexibility required by expert researchers who may need manual override or custom configurations.
Actionable Insights for Decision Makers
For manufacturers, the priority should be on securing supply chains for critical nonlinear crystals and developing partnerships with pump laser vendors to ensure compatibility. Investing in thermal management solutions and automation features will differentiate products in a crowded field. Companies should also monitor regulatory changes regarding dual-use items to ensure uninterrupted global distribution.
Investors should look for companies that demonstrate strong integration capabilities with existing laser platforms, as turn-key solutions are increasingly preferred over modular components. Firms that show innovation in high-repetition-rate, high-power regimes or those accessing underserved spectral regions may offer attractive growth potential. Due diligence should include an assessment of the company's ability to navigate export controls and supply chain vulnerabilities.
Procurement leaders and research heads should focus on specifying systems that offer flexibility for future applications rather than optimizing solely for current needs. Evaluating the vendor's support ecosystem, including software integration and automation features, is as important as the technical specifications of the OPA itself. Ensuring compatibility with existing infrastructure will reduce total cost of ownership and downtime.
For those requiring granular data on regional splits, specific application revenue breakdowns, and detailed competitor benchmarking, accessing the full market intelligence report is recommended. The complete research provides the necessary depth to support investment decisions, product roadmap planning, and strategic positioning in this evolving high-tech sector.
For detailed analysis of this topic, please visit the official page: Worldwide Femtosecond OPA Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


