



Beyond the 9.24% CAGR Story: The Real Drivers Reshaping the Worldwide Intermediate Bus Converter Market

Strategic Shifts and Commercial Opportunities in the Worldwide Intermediate Bus Converter Market
Market Overview and Core Challenges
The global intermediate bus converter (IBC) market has established itself as a critical component within distributed power architectures, serving as the bridge between high-voltage input buses and low-voltage point-of-load regulators. Valued at approximately $640.0 million in 2025, the market has demonstrated consistent expansion over the past five years, recovering steadily from the volatility experienced during the early 2020s. Projections indicate that the sector will continue its upward trajectory, reaching an estimated $1.19 billion by 2032. This growth reflects a compound annual growth rate of 9.24 percent, signaling strong underlying demand drivers that extend beyond cyclical recovery.
Geographically, the market spans a diverse footprint. Asia Pacific represents the largest revenue contributor, followed by North America and Europe. Latin America and the Middle East & Africa, while smaller in absolute terms, offer emerging opportunities as infrastructure modernization accelerates in these regions. In terms of technology segmentation, isolated IBC solutions currently command a larger share of revenue compared to non-isolated variants, reflecting the stringent safety and noise-immunity requirements in telecommunications and industrial infrastructure. However, non-isolated designs are gaining traction in applications where size, cost, and efficiency take precedence over galvanic isolation.
Interface Bridge ICs Market
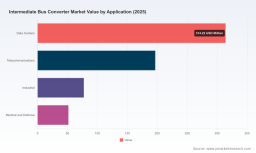
Application-wise, data centers dominate consumption, fueled by the relentless expansion of cloud computing and hyperscale facilities. Telecommunications infrastructure remains a substantial consumer base, particularly as legacy networks transition to 5G and edge computing deployments. Industrial automation and medical/defense systems contribute to steady baseline demand, though these segments typically exhibit longer product lifecycles and more conservative adoption curves.
Despite the favorable growth trajectory, the IBC market faces several structural challenges that will shape competitive dynamics in the coming years.
- Architecture disruption from direct conversion trends. Emerging high-voltage DC distribution schemes and advanced wide-bandgap devices are enabling topologies that bypass or minimize the traditional intermediate bus stage. Some initiatives target 800V DC delivery directly to downstream converters, which could compress the addressable market for conventional IBC modules in certain AI server configurations.
- Thermal and power density limits. As rack densities climb, the ability to dissipate heat within standard form factors becomes a binding constraint. Manufacturers must balance efficiency gains against thermal management complexity, particularly in confined cabinet spaces where airflow is limited.
- Supply chain friction and component availability. High-performance IBC designs depend on specialized magnetics, high-voltage capacitors, and advanced semiconductor processes. Fluctuations in raw material costs, lead times for critical passive components, and geopolitical sourcing risks can create margin pressure and inventory volatility for both suppliers and end-users.
Key Drivers of Market Change
The expansion of the IBC market is being propelled by a convergence of technological, regulatory, and demand-side forces. Understanding these drivers is essential for assessing where value will accumulate and which product strategies will prove durable.
Technological Innovation and High-Voltage Architecture Shift
The most transformative driver is the push toward higher-voltage distribution and increased power density. Traditional 48V intermediate bus architectures have served the industry well, but the extreme power requirements of modern AI workloads are prompting a reevaluation of the power delivery chain. New reference designs are emerging that operate at ±400V or 800V DC levels, supported by wide-bandgap semiconductors such as gallium nitride. These developments enable higher efficiency and more compact conversion stages, but they also challenge the conventional role of the IBC. In parallel, non-isolated quarter-brick IBC modules are being optimized for hyperscale computing, with peak power capabilities reaching several kilowatts and efficiency levels approaching 98 percent in select designs. This dual path—higher voltage direct architectures on one hand, and ultra-high-performance intermediate bus modules on the other—creates a rich environment for engineering differentiation.
Regulatory and Safety Standards Shaping Design Choices
Safety and compliance requirements continue to influence product roadmaps and procurement decisions. Commercial IBC modules generally adhere to IEC/EN/UL 62368-1 safety standards applicable to information and communication technology equipment. As data centers and telecom operators consolidate infrastructure, the ability to demonstrate compliance with globally recognized safety frameworks becomes a competitive differentiator, especially in multi-vendor deployments where risk mitigation and interoperability matter. Additionally, trends toward centralized power distribution and higher voltage DC architectures are intersecting with evolving electrical codes and data center safety guidelines, creating a need for converters that can operate reliably in more electrically stressful environments.
PW Consulting
Demand-Side Shifts Driven by AI and Compute Intensity
The demand profile for power conversion hardware is being reshaped by the computational intensity of AI training and inference workloads. Hyperscale data centers are deploying denser racks with higher per-rack power budgets, and this directly increases the need for efficient intermediate conversion stages that can handle transient loads and deliver stable lower-voltage rails to downstream regulators. While some initiatives aim to eliminate the traditional IBC stage in specific AI server platforms, many deployments still rely on intermediate bus conversion to manage distribution losses, noise isolation, and modular scalability. Beyond data centers, telecommunications networks continue to expand edge and baseband processing units, and industrial automation systems are integrating more power-dense control electronics. These application trends sustain demand across a diversified end-use base.
Supply Chain and Cost Structure Dynamics
Cost structures in the IBC market are influenced by both material economics and engineering intensity. Designs that incorporate advanced magnetics, high-voltage isolation, and precision control circuitry tend to carry higher bill-of-material costs, which can pressure margins in price-sensitive segments. At the same time, the emergence of highly integrated modules and digital control architectures can reduce system-level complexity and improve overall total cost of ownership, even if the converter unit itself is more expensive. Supply chain resilience is increasingly a strategic consideration; companies that can secure reliable access to critical components and maintain design flexibility in the face of component shortages are better positioned to capture share when demand accelerates.
Competitive Landscape and Leading Strategies
The IBC market features a mix of specialist power semiconductor and converter manufacturers as well as broader industrial power electronics players. Concentration is moderately high, with the top three firms accounting for roughly 41.5 percent of revenue and the top five representing about 56.8 percent. This concentration suggests that scale, technology leadership, and established customer relationships matter, but there remains meaningful room for differentiated offerings in niche form factors, digital control, and high-voltage architectures.
Strategic Positioning Among Leading Players
Several incumbents have carved out distinct value propositions aligned with their technological strengths and target verticals:
Bus Validator Market
- Vicor Corporation has built a reputation around fixed-ratio isolated IBC products designed for distributed power architectures. Its focus on enterprise, telecom, and high-efficiency systems positions it well in applications where galvanic isolation and predictable conversion ratios simplify downstream design.
- Flex Power Modules has emphasized compact, high-performance IBC solutions optimized for AI and data center environments. Its product lines include non-isolated and digitally controllable designs with strong peak power capability, targeting hyperscale computing where density and efficiency are paramount.
- Infineon Technologies AG supplies high-density IBC modules and leverages wide-bandgap technology through CoolGaN-based reference designs. Its recent push into high-voltage architectures for 48V and 800V DC systems reflects a strategy aimed at leading the transition toward more electrically demanding power distribution topologies in AI server platforms.
- Analog Devices, Inc. focuses on discrete quarter-brick reference designs that prioritize efficiency and thermal performance, particularly for data center applications. By emphasizing detailed performance characterization and advanced control, it addresses engineering teams seeking proven building blocks with clear performance trade-offs.
- Delta Electronics, Murata Manufacturing, Bel Power Solutions, Artesyn Embedded Power, CUI Inc., and Reed Semiconductor collectively round out a competitive field that spans broad power conversion portfolios, embedded computing applications, telecom and networking use cases, and distributed power architectures for servers. Their strategies often emphasize portfolio breadth, compliance, cost positioning, and regional service capabilities.
Recent Developments and Strategic Signals
Recent product and reference design activity highlights where competitive attention is concentrating:
- In March 2026, Infineon Technologies AG introduced two new CoolGaN-based high-voltage IBC reference designs supporting ±400V and 800V DC architectures for AI server power systems. This move signals a strategic bet on high-voltage distribution becoming mainstream in next-generation AI infrastructure.
- Also in March 2026, Navitas Semiconductor demonstrated an 800V–6V DC-DC power delivery board using GaNFast technology designed to eliminate the traditional 48V intermediate bus converter stage for NVIDIA AI infrastructure. While this approach may reduce IBC unit demand in specific configurations, it underscores the broader competitive tension between modular intermediate conversion and direct high-voltage delivery.
- In September 2025, Flex Power Modules unveiled the BMR313 ultra-small, high-performance IBC engineered for AI and data center applications. The launch reinforces the push toward miniaturization and performance optimization in compute-heavy environments.
- In July 2025, Analog Devices, Inc. published detailed performance data on a discrete quarter-brick IBC reference design for data center power architectures, emphasizing efficiency and thermal management. This type of transparent engineering documentation helps establish credibility and accelerates adoption among design teams.
Market Evolution: Consolidation, Differentiation, and New Entrants
The competitive landscape is likely to evolve along three axes. First, consolidation may continue as larger portfolios and broader service networks become valuable to large-scale data center and telecom buyers seeking supply chain simplicity. Second, differentiation will intensify around high-voltage capability, digital control features, thermal performance, and compliance assurance, particularly as AI workloads push the boundaries of power density. Third, new entrants and adjacent semiconductor players may introduce disruptive topologies that challenge conventional IBC architectures, especially where wide-bandgap devices enable more direct power delivery. Companies that combine strong reference design support, ecosystem compatibility, and the ability to adapt to evolving architecture preferences will be best positioned to retain and expand their footprint.
Future Trends and Outlook
Looking ahead across a three-to-five-year horizon, several trends are likely to define the IBC market’s trajectory and where commercial opportunities will emerge.
Coexistence of Intermediate Conversion and Direct High-Voltage Delivery
Rather than a clean replacement of IBCs by direct conversion, the market is more likely to see architectural bifurcation. In many hyperscale and edge deployments, intermediate bus conversion will remain valuable for isolation, noise reduction, modularity, and system-level flexibility. At the same time, certain AI server platforms will adopt high-voltage direct delivery to maximize efficiency and compute density. The commercial opportunity lies in delivering IBC solutions that are adaptable to multiple architectures, with clearly defined efficiency and thermal profiles, while also monitoring where direct-conversion adoption could reshape volume expectations in specific subsegments.
Higher Power Density and Digital Intelligence in Conversion Stages
Power density requirements will continue to rise, driven by rack-scale compute growth and the need to optimize footprint and cooling costs. Modules that combine high continuous and peak power capability with advanced thermal paths and digital control interfaces will gain preference in data center and telecom applications. Digitalization can enable better monitoring, adaptive control, and predictive maintenance, which aligns with operational priorities in large-scale infrastructure. Suppliers that integrate intelligence at the converter level, while maintaining safety and reliability, can create differentiated value beyond raw conversion performance.
Regional Diversification and Segment-Specific Demand Patterns
While data centers will remain the dominant demand pool, regional dynamics and segment-specific adoption cycles will influence growth patterns. Asia Pacific’s scale advantage may be complemented by incremental modernization in other regions as telecom, industrial, and defense programs refresh their power architectures. Segment-wise, telecommunications and industrial applications are likely to provide steadier, less cyclical demand, whereas data center volumes may be more sensitive to capex cycles and architectural changes. Companies that can balance a strong data center proposition with resilient demand from other verticals will enjoy more stable revenue streams.
Risks and Uncertainties
Several uncertainties could moderate the outlook. Architecture shifts that reduce reliance on intermediate bus stages in certain AI platforms may compress volume growth in specific form factors. Macroeconomic pressures on data center capex, changes in telecom investment timing, and component supply disruptions could create intermittent demand volatility. Additionally, safety and compliance requirements may evolve as high-voltage DC distribution becomes more prevalent, potentially influencing qualification timelines and design costs. Stakeholders should monitor these factors closely and adjust product roadmaps and inventory strategies accordingly.
Guidance for Decision Makers
Different stakeholder groups can extract actionable direction from the current market signals.
For Power Converter and Component Manufacturers
Prioritize engineering investments that address the two most consequential questions: how to maintain relevance in high-voltage and direct-conversion scenarios, and how to differentiate through power density, thermal performance, and digital control. Develop reference designs and application support that make it easy for customers to evaluate trade-offs between isolated and non-isolated IBC options, and between intermediate conversion and alternative architectures. Strengthen supply chain resilience for critical magnetics, capacitors, and semiconductor processes to reduce exposure to component shortages and cost swings.
For Investors and Corporate Development Teams
Focus due diligence on companies that demonstrate clear positioning around high-voltage readiness, AI and data center demand, and compliance assurance. Assess whether product portfolios are broad enough to benefit from steady demand in telecom and industrial segments while capturing upside from data center growth. Pay attention to firms that are actively shaping ecosystem compatibility and reference design quality, as these attributes often correlate with adoption velocity in complex power system designs.
For Procurement, Engineering, and Infrastructure Planning Teams
Evaluate IBC suppliers not only on unit cost but on total system impact, including efficiency, thermal behavior, qualification timelines, and compatibility with target architectures. Where possible, design for flexibility so that intermediate bus conversion can be retained or bypassed depending on final platform decisions. Maintain visibility into upcoming reference designs and architecture shifts, since these can materially affect qualification lead times and interoperability planning.
The intermediate bus converter market is at an inflection point where technology evolution, architecture debates, and demand concentration in AI-driven data centers are reshaping where value is created. Decision-makers who secure timely, granular intelligence on segment dynamics, competitive moves, and architecture transitions will be better equipped to align product strategies, investment priorities, and procurement plans with the market’s trajectory. For stakeholders seeking deeper segmentation details, regional breakdowns, and tailored guidance aligned to specific operational goals, accessing the full research report provides the granular evidence base needed to move from directional insight to precise execution.
For detailed analysis of this topic, please visit the official page: Worldwide Intermediate Bus Converter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


