



Metal Mesh Sleeve Composite Compensator Market: Why 5.38% CAGR Redefines 2032

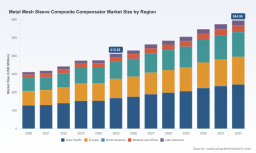
Global Metal Mesh Sleeve Composite Compensator Market: Strategic Trends and Commercial Opportunities (2026–2032)
The worldwide market for metal mesh sleeve composite compensators has entered a phase of steady, structurally driven expansion. Valued at 412.28 million USD in 2025, the sector is projected to reach 594.96 million USD by 2032, reflecting a compound annual growth rate of 5.38 percent over the forecast horizon. This trajectory follows a measured recovery from the 2020 baseline of 311.45 million USD, with particularly notable acceleration between 2022 and 2025 as industrial operators prioritized thermal management solutions amid volatile energy environments and infrastructure modernization programs. The growth is not merely cyclical; it reflects a fundamental shift in how high-temperature fluid systems, combustion exhaust networks, and precision piping assemblies are engineered to accommodate expansion, vibration, and alignment tolerances.
Despite the positive trajectory, the industry faces several structural friction points that will define competitive outcomes over the next cycle. First, standardization and certification complexity continue to fragment procurement cycles across jurisdictions. Pressure equipment directives, mechanical engineering associations, and regional safety frameworks impose divergent testing, documentation, and material traceability requirements, lengthening qualification timelines and increasing non-recurring engineering costs for suppliers seeking multi-market footprints. Second, the raw material backbone of metal mesh sleeves and bellows remains tightly coupled to stainless steel pricing dynamics and specialty alloy availability. Grades such as 304, 316, and 321 are routinely specified for corrosion resistance and high-temperature flexibility, yet their cost volatility introduces margin uncertainty, particularly for manufacturers operating on fixed-price contracts or long-lead procurement agreements. Third, the market exhibits a moderate concentration profile, with the top three players accounting for roughly 18 percent of revenue and the top five reaching just over 28 percent. This leaves substantial room for regional specialists and new entrants, but also means that incumbents must continuously defend position through engineering differentiation rather than scale alone. The transition from commoditized sleeve assemblies to integrated, application-engineered compensator systems is reshaping how value is captured and how customers evaluate total cost of ownership.
PW Consulting
Key Drivers Reshaping the Market
Technological Innovation and Material Engineering
Advancements in composite architecture and metallic reinforcement are redefining performance envelopes for expansion compensation. Multi-layer fabric composites and PTFE-lined configurations have become baseline expectations in corrosive and high-cycle environments, while elastomer-integrated designs are gaining traction where dynamic vibration damping and rapid thermal response are critical. Engineers are increasingly specifying compensators that combine metal mesh sleeves with precision-wound bellows, internal sliding sleeves, and reinforced gasket interfaces to manage axial, lateral, and angular movements without compromising sealing integrity. The ability to tailor layer composition, mesh density, and liner thickness to specific pressure-temperature regimes allows suppliers to move up the value chain, offering application-specific solutions rather than catalog components. This engineering granularity is particularly valuable in sectors where unplanned downtime carries heavy economic consequences, pushing procurement teams to prioritize reliability and lifecycle performance over unit price.
Worldwide Braided Sleeving Market
Regulatory and Standards Environment
Compliance frameworks are acting as both a barrier to entry and a catalyst for professionalization. Expansion joints and composite compensators must align with pressure equipment directives, ASME guidance, and EJMA conventions for design, fabrication, and inspection. These standards are not static; they evolve as operators and regulators place greater emphasis on documented material traceability, weld integrity, fatigue testing, and installation verification. Suppliers that invest early in standardized qualification protocols, digital documentation trails, and third-party validation tend to shorten customer approval cycles and reduce project risk for engineering contractors. Conversely, manufacturers that rely on regional homologation alone face lengthening sales cycles when bidding on cross-border infrastructure programs. The regulatory environment is also pushing consolidation of technical support functions, as end users increasingly expect a single point of accountability for design review, field installation guidance, and ongoing maintenance advisories.
Demand-Side Shifts Across Industrial Sectors
Demand is being pulled by several overlapping operational priorities. Power generation facilities are expanding and upgrading turbomachinery and heat recovery networks, where precise thermal expansion management and vibration isolation directly affect asset reliability. Chemical and petrochemical operators are extending service life in corrosive fluid handling and high-temperature reactor piping, favoring compensators that combine metal reinforcement with chemically resistant liners. Marine and shipbuilding programs, including LNG-capable vessel construction and retrofit campaigns, require flexible connections that withstand cyclic loading, saline exposure, and compact spatial constraints. Aerospace and defense applications add another layer of specificity, demanding lightweight, high-integrity compensators for engine test rigs, ground support piping, and specialized fluid systems. HVAC and construction segments contribute steady, distributed demand, particularly in large commercial and industrial building networks where thermal movement must be absorbed without compromising pressure stability.
Supply Chain and Cost Structure Dynamics
The cost architecture of composite compensators is increasingly shaped by material sourcing strategies, manufacturing localization, and production efficiency. Stainless steel grades form the structural core of metal mesh sleeves and bellows, making input cost management a strategic priority. Manufacturers are responding by diversifying alloy suppliers, securing long-term mill agreements, and optimizing cut-and-form cycles to reduce scrap and labor intensity. At the same time, regionalization of production is accelerating as customers seek shorter lead times, lower freight exposure, and closer engineering collaboration. This does not necessarily mean full decentralization; rather, it favors a hybrid model where core metallurgical and testing capabilities remain concentrated, while finishing, assembly, and technical support are positioned closer to key demand clusters. The net effect is a supply base that is more responsive but also more complex to coordinate, rewarding companies with robust quality systems and integrated design-to-delivery workflows.
Competitive Landscape and Strategic Positioning
The competitive field is defined by a mix of established European specialists, globally operating engineering groups, and regionally anchored manufacturers with expanding footprints. Witzenmann GmbH occupies a prominent position in flexible metal elements, offering a broad portfolio of metal expansion joints and bellows with internal sleeves designed for pipeline compensation across industrial, energy, and plant engineering applications. Its differentiation rests on system-level engineering depth, broad configuration flexibility, and long-standing relationships with engineers who specify compensators as part of integrated piping designs rather than isolated components. EagleBurgmann similarly competes on application breadth, supplying axial, tied, and clamshell expansion joint designs with bellows and protective sleeves for power generation, petrochemical, and heavy industry piping systems. Its strategic emphasis on ruggedized designs and field-proven configurations aligns with operators prioritizing reliability in demanding thermal and pressure environments.
Teadit Group has reinforced its market presence through application-focused knowledge sharing, including guidance on maintenance programs for metallic and non-metallic expansion joints and technical articles on using expansion joints to elevate heat exchanger performance under thermal cycling. This content-driven approach supports a positioning strategy centered on lifecycle value, customization, and engineering partnership rather than price competition. The company's EJMA membership and focus on refining, petrochemical, power, and mining applications further anchor its credibility in sectors where documentation and standardized design practices carry significant weight. BOA Group complements the landscape with stainless steel expansion joints across standard, industrial, and special series, serving engine, shipbuilding, rail, and industrial piping compensation needs. Its ability to scale up to large nominal diameters while maintaining structured product families gives it relevance in infrastructure and mobile equipment programs where spatial and load constraints vary widely.
On the materials- and application-specific side, Mersen contributes Armylor PTFE bellows and compensators, often reinforced with metal elements, targeting highly corrosive chemical and pharmaceutical piping systems where chemical resistance and sealing stability are paramount. This specialization illustrates how material science can create defensible niches even within a broadly engineered product category. A cohort of manufacturers based in China, including Sunny Steel Enterprise, TongYong Bellows, Haoyin Bellows, and Wenda Metal Hose, has expanded the supply base for sleeve compensators, metal compensators, and metal mesh sleeve assemblies used in hot fluid pipelines, vibration reduction, and specialized flexible connections including LNG-related applications. These producers typically compete on configuration availability, lead-time responsiveness, and cost efficiency, while increasingly investing in stainless steel construction quality and application documentation to meet the expectations of more discerning buyers.
Recent operational and knowledge-development activity underscores how competition is evolving. In late 2025, Teadit published maintenance guidance and heat exchanger performance expertise, signaling a broader industry shift toward educational engagement and lifecycle support as differentiators. In early 2026, Comdiflex highlighted ongoing production of compensators incorporating metal rings or wire for structural strength in gaskets and expansion components, reflecting continuous refinement in reinforcement design. These developments point to a market where competitive advantage is increasingly derived from engineering credibility, documentation maturity, and the ability to reduce installation and maintenance risk for end users. The landscape is neither fully consolidated nor fragmented beyond recovery; it is stratified, with premium engineering players competing on performance and total cost of ownership, while regional manufacturers compete on responsiveness, configuration breadth, and price. New entrants can gain traction by targeting underserved application niches, modularizing complex designs for faster configuration, or offering hybrid material solutions that bridge corrosion resistance and structural durability.
Worldwide Micro Perforated Sleeves Market
Future Trends and Strategic Implications
Over the next three to five years, the market is likely to be shaped by three interlinked trends. First, application-engineered customization will become the default expectation in higher-value segments. As power, chemical, marine, and aerospace programs demand tighter control over thermal movement, vibration damping, and corrosion performance, suppliers that can rapidly map operating conditions to compensator architecture will capture disproportionate share. This shifts commercial negotiations from unit pricing toward specification alignment, testing evidence, and lifecycle support. Second, regulatory and standards harmonization efforts, even if incremental, will compress qualification timelines for suppliers that already operate with mature documentation and testing practices. Companies that treat compliance as a design input rather than a post-production checkbox will secure faster market access and stronger position in cross-border tenders. Third, supply chain resilience will increasingly influence procurement decisions. Buyers will favor suppliers that can demonstrate stable alloy sourcing, predictable lead times, and localized technical support, especially for projects where installation windows are tight and rework is costly. This favors organizations that balance centralized engineering mastery with regionally distributed assembly and service capability.
These trends create clear commercial opportunities. Manufacturers can expand margins by moving toward specification-led selling, bundling design review, installation guidance, and maintenance advisories with core compensator sales. Investors can look for companies that combine material expertise with modular production platforms, since such setups allow faster response to specification changes without sacrificing quality. Procurement teams can reduce project risk by prioritizing suppliers with documented fatigue and corrosion performance data, clear standards alignment, and established field support, rather than selecting solely on initial price. At the same time, uncertainty persists. Raw material price swings, divergent regional certification requirements, and shifting end-user project pipelines can compress margins or delay adoption. Over-engineering for one application class while neglecting others may also leave suppliers exposed if demand rotates toward different sectors more quickly than anticipated.
Actionable Guidance for Decision-Makers
Manufacturers should treat metal mesh sleeve composite compensators as a platform for engineering differentiation rather than a commodity output. Investing in modular design libraries, material-grade flexibility, and documented testing protocols will shorten configuration cycles and improve win rates in specification-driven bids. Strengthening technical content and maintenance guidance also builds trust with engineering teams who increasingly evaluate total cost of ownership across the asset life. Investors should prioritize organizations that demonstrate scalable production without sacrificing metallurgical control, alongside a clear route to higher-margin segments such as chemical processing, power generation, and specialized marine or aerospace piping. Procurement and engineering leaders should standardize evaluation criteria around standards alignment, fatigue and corrosion evidence, installation support, and supply continuity, ensuring that specification choices reduce downstream operational risk rather than simply minimizing upfront cost.
For those seeking a deeper view of segment dynamics, regional breakdowns, material-grade trends, and company-level positioning, a detailed research study can provide the granularity needed to convert these high-level insights into procurement plans, capacity decisions, and investment theses. The full report extends the analysis with structured segmentation data, competitive benchmarking, and tailored guidance for manufacturers, investors, and buyers navigating this evolving market.
For detailed analysis of this topic, please visit the official page: Worldwide Metal Mesh Sleeve Composite Compensator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


