



Mazindol Tablet Market: Why 4.12% CAGR and Asia Pacific Weight Drive 2032 Billion>

Navigating the Global Mazindol Tablet Market: Strategic Trends and Commercial Opportunities (2025–2032)
1. Market Context and Core Challenges
The worldwide Mazindol tablet market has entered a phase of measured expansion, anchored by steady demand in niche therapeutic areas and a recognized role for appetite suppression in obesity management. Market size data across recent years reflects a trajectory that moved from approximately $191 million in 2020 to a base of $235 million in 2025, with forward estimates projecting growth toward $312 million by 2032. This path corresponds to a compound annual growth rate of 4.12% over the 2026–2032 forecast window, indicating that while expansion is not explosive, it is structurally durable. The valuation reached in 2025 establishes a starting point for planning, and the incremental growth curve suggests that value creation will depend less on volume surges and more on formulation differentiation, indication extension, and regional availability improvements.
Kamstrup et al. (2017) noted the sizeable drop in bioavailability of oral mazindol 2 mg relative to the reference standard, highlighting pharmacokinetic considerations that continue to inform formulation choices.
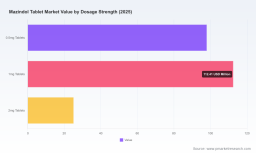
The size of the market is underpinned by multiple application streams, with obesity management representing the dominant share of revenue, followed by more specialized use cases in narcolepsy treatment and clinical research. Dosage strength distribution shows that mid-strength and higher-strength presentations account for a meaningful portion of sales, reflecting formulation strategies that balance efficacy, tolerability, and dosing convenience. In regional terms, Asia Pacific and Latin America together constitute a substantial share of the market, while Europe, North America, and the Middle East and Africa provide smaller but strategically important contributions. This geographic pattern reflects the intersection of authorized manufacturing footprints, local availability, and clinical practice norms.
PW Consulting
Concentration is pronounced. The market structure is dominated by a limited number of authorized manufacturers and specialized developers, with top players holding a meaningful share of total revenue. The market concentration profile—characterized by a high share held by the leading manufacturers and a robust share captured by the top five—underscores the importance of manufacturing authorization, regulatory standing, and formulation IP in shaping commercial outcomes.
Key Challenges and Inflection Points
One central challenge lies in the regulatory classification of mazindol as a controlled substance. In the United States, mazindol is categorized as a Schedule IV controlled substance, which shapes how formulations can be developed, marketed, and distributed. This classification introduces procedural complexity and influences the pace at which new entrants can scale, while also affecting reimbursement pathways and prescriber behavior in certain territories.
A second inflection point concerns availability and the legacy status of the original branded product. The original branded mazindol (Sanorex, Mazanor) was discontinued in the United States and European markets around the late 1990s to early 2000s for commercial reasons, and limited availability has persisted in select markets such as Mexico, Central America, Japan, and Argentina. At the same time, the FDA has determined that mazindol tablets (1 mg and 2 mg) were not withdrawn from sale for reasons of safety or effectiveness, a determination that supports the possibility of generic approvals under appropriate regulatory pathways. This combination of historical discontinuation and a permissive regulatory stance creates both an opening for reformulation and a need to navigate fragmented availability.
Finally, there is a supply chain concentration risk that warrants attention. Certain developers rely on single third-party manufacturing arrangements for drug substance and drug product, which can affect continuity, quality oversight, and time-to-market. As the market expands and more stakeholders evaluate mazindol-based programs, resilience in sourcing and manufacturing relationships becomes a strategic differentiator rather than a back-office concern.
2. Key Drivers of Market Change
Technological Innovation and Formulation Breakthroughs
Formulation technology is a primary engine of value creation in this market. Extended-release and modified-release approaches are reshaping the therapeutic proposition by smoothing plasma exposure, improving tolerability, and enabling once-daily dosing regimens. Patent-protected multilayer tablet architectures for immediate-release and sustained-release combinations illustrate how intellectual property can be aligned with clinical differentiation rather than serving only as a defensive moat. In parallel, peer-reviewed scientific contributions continue to broaden understanding of mazindol’s multifaceted mechanisms, reinforcing the case for broader therapeutic exploration beyond historical appetite-suppression uses. These scientific advances support formulation programs that are designed for specific indications and patient profiles, rather than treating the molecule as a commodity.
Policy and Regulatory Environment
Regulatory clarity and controlled-substance policy are shaping how the market can grow. The determination that branded mazindol tablets were not withdrawn for safety or effectiveness reasons creates an enabling backdrop for abbreviated new drug applications and potential generic entry over time. At the same time, the Schedule IV classification means that any scale-up in availability must account for handling, prescribing, and distribution requirements that vary by jurisdiction. Government authorization for manufacture as a psychotropic substance in select countries adds another layer: in those markets, the ability to produce and supply depends on regulatory standing and compliance, which can become a competitive advantage for established, authorized manufacturers.
Demand-Side Shifts
Demand is influenced by evolving clinical and patient perspectives on weight management and sleep disorders. In obesity management, the broader therapeutic landscape is moving toward multi-modal and sustained approaches, which elevates interest in molecules with established appetite-modulating profiles, especially when paired with formulations that support adherence. In narcolepsy and related hypersomnolence conditions, there is growing attention to agents that can address daytime sleepiness while fitting into long-term management plans. For clinical research, mazindol continues to serve as a reference molecule in studies of appetite regulation, stimulant mechanisms, and related pharmacology, sustaining a smaller but consistent demand stream. Together, these demand patterns favor stakeholders who can present credible clinical narratives, appropriate dosing options, and reliable supply.
Supply Chain and Cost Structure Dynamics
Cost structure dynamics are increasingly tied to manufacturing authorization, formulation complexity, and supply resilience. Where manufacturers hold GMP capabilities and authorized status, they can capture value through both branded and generic pathways, particularly in markets where availability has historically been limited. Conversely, reliance on single-source manufacturing arrangements can compress flexibility and elevate risk, especially when programs advance toward later-stage clinical use or commercialization. Over the forecast period, stakeholders are likely to place greater emphasis on dual-sourcing strategies, quality systems, and regional manufacturing footprints that reduce lead-time and continuity risk. For investors and commercial teams, the cost equation is not solely about API price; it also includes the expense of regulatory navigation in controlled-substance markets and the operational cost of maintaining consistent availability in fragmented territories.
Worldwide Armodafinil Market
These drivers connect to recent market developments that illustrate how strategy and execution are converging. Patent protection extending beyond September 2038 for certain mazindol ER formulations and their uses in ADHD, sleep disorders, and opioid dependence signals a long-duration IP strategy aimed at securing exclusivity for differentiated products. In parallel, planning activity around late-stage clinical programs for mazindol ER in narcolepsy indicates that developers are preparing for potential indication expansion into sleep medicine. Complementary scientific publication activity further supports the narrative that mazindol’s mechanism and therapeutic potential are being revisited with contemporary rigor. For authorized manufacturers in Latin America, maintaining compliant production of mazindol and related substances provides continuity in markets where availability is valued, while historical originator experience remains relevant as a reference point for regulatory determinations and generic pathway discussions.
3. Competitive Landscape and Leading Strategies
The competitive landscape is defined by a small set of authorized manufacturers and specialized developers, each pursuing a distinct strategic position. One group comprises Argentine manufacturers with authorized production status for mazindol as listed in UNODC reports on narcotic and psychotropic substances. Their positioning is anchored in regulatory authorization and regional manufacturing capability, which supports continuity of supply in markets where authorized production and local availability matter. A second group is represented by a Brazilian manufacturer with mazindol API production and GMP capabilities, offering an upstream value position that can support both domestic and export-oriented supply chains. A third group includes a Swiss-based developer focused on extended-release formulations and indication expansion, with platforms targeting narcolepsy/idiopathic hypersomnia and ADHD, as well as internal-release and sustained-release multilayer tablet architectures and potential applications in opioid dependence. The historical originator, based in Switzerland, remains relevant as a reference point even though its branded product was discontinued in major markets, with its legacy influencing regulatory determinations and the broader commercial conversation.
Strategic Positioning and Differentiation
Differentiation is emerging along several axes. Formulation IP is one of the clearest levers. Patent protection for extended-release formulations and their uses provides a long-duration competitive advantage, particularly when paired with late-stage development planning in narcolepsy. This positions developers to build defensible franchises around specific dosing regimens and indications, rather than competing solely on molecule-level equivalence. A second axis is regulatory standing. Authorized manufacturers that are explicitly listed for mazindol or related psychotropic substance manufacture have an advantage in markets where authorization is a prerequisite for lawful production and distribution. A third axis is scientific credibility. Peer-reviewed publication activity that revisits mechanism and therapeutic potential can strengthen the basis for indication expansion and support dialogue with clinicians, regulators, and partners. Finally, manufacturing and quality capability—GMP compliance for API production and controlled manufacturing arrangements for drug substance and product—underpins both reliability and the ability to support later-stage programs.
Evolving Market Structure: Consolidation, Fragmentation, and New Entry
The market is likely to evolve through a combination of consolidation around authorized players and selective fragmentation driven by formulation and indication strategy. Because the molecule is a controlled substance and availability has historically been uneven, the number of entities that can credibly enter is naturally constrained. This favors incumbents that already hold authorization, IP, or clinical data. At the same time, the FDA’s determination that branded tablets were not withdrawn for safety or effectiveness reasons preserves a potential pathway for generic competition in certain markets where appropriate approvals can be secured. That pathway introduces fragmentation risk over the longer term, particularly if multiple generic sponsors pursue authorized generics or regionally targeted launches. New entry will most likely come from players that can combine regulatory navigation, formulation differentiation, and supply resilience, rather than from undifferentiated volume plays. For investors, this suggests that value will accrue to companies that can articulate a clear clinical and commercial rationale, protect it with IP where available, and execute reliably in a controlled-substance environment.
Within this landscape, one practical implication is that competitive advantage is less about raw market share and more about optionality. The companies that can sustain authorized production, advance differentiated formulations, and keep multiple indication and market pathways open are better positioned to capture growth as availability improves and clinical uses broaden. Conversely, stakeholders that depend on a single manufacturing relationship or lack clear regulatory positioning face more constrained upside and higher continuity risk.
4. Future Outlook: Trends and Opportunities (2026–2032)
Trend 1: Gradual Value Growth Through Formulation and Indication Expansion
Over the next several years, the market is expected to grow at a measured pace consistent with the 4.12% CAGR projected across the 2026–2032 period. Rather than dramatic acceleration, the more likely path is steady value accumulation driven by differentiated formulations, expanded clinical narratives, and improved availability in select markets. For commercial teams, this implies that growth will be won through product design and clinical positioning as much as through reach. Opportunities will emerge for stakeholders who can align extended-release or modified-release designs with adherence and tolerability expectations, and who can support indication exploration in sleep disorders and related areas.
Trend 2: Regional Availability and Authorized Manufacturing as strategic Moats
Authorized manufacturing status and regional availability are likely to remain powerful differentiators. In markets where mazindol has maintained limited availability or where authorized production is a prerequisite, manufacturers with the right regulatory standing can secure durable demand. Opportunities may also arise as generic pathways become more accessible in jurisdictions where the regulatory backdrop allows, particularly if new entrants can demonstrate bioequivalence or therapeutic equivalence under the appropriate frameworks. At the same time, regional regulatory variation will continue to shape where and how products can be made available, making local compliance and distribution expertise a critical enabler.
Trend 3: Controlled-Substance Management as a Strategic Capability
As activity increases around formulation development, clinical programs, and potential generic entry, the ability to manage controlled-substance requirements will become more central to commercial execution. This includes handling, prescribing, and distribution considerations that differ by jurisdiction, as well as the operational discipline needed to maintain continuity when supply chains are concentrated. Stakeholders that treat controlled-substance compliance as a strategic capability—rather than a regulatory overhead—are better positioned to reduce interruption risk and build trust with prescribers, payers, and partners. Opportunities here include dual-sourcing strategies, quality system investment, and clear documentation of manufacturing authority and compliance.
Potential uncertainties should be acknowledged. Clinical outcomes from late-stage programs, regulatory decisions regarding indications and generic pathways, and shifts in controlled-substance policy could influence the pace and shape of growth. In addition, supply concentration and regional availability constraints could affect continuity if not actively managed. These factors do not change the structural outlook, but they highlight the importance of scenario planning and flexible execution.
Worldwide Danazol Market
5. Strategic Recommendations for Decision Makers
For Manufacturers and Developers
Prioritize formulation differentiation backed by durable IP where possible, especially in extended-release and multilayer architectures that support indication-specific use. Align development programs with clinical areas where medical need is clear and where adherence and tolerability can be meaningfully improved. Invest in manufacturing resilience by diversifying sourcing where feasible and strengthening quality systems, since continuity will increasingly differentiate credible programs from fragile ones. Maintain regulatory positioning that reflects authorized manufacturing status and controlled-substance obligations, as these will influence market access in important territories.
For Investors
Focus on companies with clear optionality across formulations and indications, supported by IP, clinical data, or authorized manufacturing standing. Assess supply chain concentration and regulatory positioning as core risk factors, not peripheral issues. Favor business models that can sustain value through a controlled-substance environment and that have credible pathways to indication expansion or regional availability improvements. In a market growing at a moderate CAGR, returns are likely to come from differentiated execution rather than broad volume assumptions.
For Procurement and Supply Chain Leaders
Evaluate supplier authorization status, GMP capability, and manufacturing resilience before committing to long-term supply arrangements. Where possible, build redundancy into sourcing for drug substance and drug product, and confirm documentation that supports compliance in controlled-substance markets. Consider regional availability constraints when planning inventory and demand forecasting, especially in markets where access has been historically limited. Proactive supplier qualification can reduce interruption risk and support more stable planning.
For stakeholders seeking to move from high-level trend awareness to detailed, segment-level planning, granular data on regional performance, dosage strength splits, application-specific dynamics, competitive positioning, and scenario-based forecasts can materially sharpen strategy. Access to a full structured research set enables more precise prioritization of markets, formulations, and partner options, and helps align commercial plans with the regulatory and supply realities that shape this market.
For detailed analysis of this topic, please visit the official page: Worldwide Mazindol Tablet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


