



Worldwide Container Vans Market: Why 4.35% CAGR and Asia Pacific Growth Redefine Future Returns

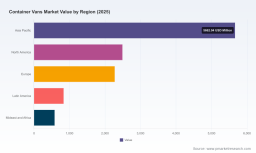
The Worldwide Container Vans Market: Navigating Growth, Geopolitics, and Industrial Transformation Through 2032
The global container vans market has evolved from a cyclical, commodity-driven sector into a strategically critical component of international trade and logistics infrastructure. Over the past five years, the market has demonstrated resilience amid shifting trade patterns, supply chain reconfiguration, and tightening environmental standards. Measured in USD across the baseline year of 2025 and extending through the forecast horizon to 2032, the industry reflects a steady, structurally anchored trajectory. Revenue figures spanning the historical period from 2020 through 2025 reveal a market that absorbed the turbulence of pandemic-era disruptions, rebound in global freight volumes, and gradually stabilized into a more predictable growth environment. Entering the forecast window, the market is expanding at a compound annual growth rate of approximately 4.35 percent, with total revenue values projected to cross the mid-point of the next decade at a scale that underscores the enduring role of standardized containerized transport in global commerce.
This expansion is not merely a function of increased freight tonnage. It reflects deeper structural shifts in how goods move across maritime routes, inland corridors, and multimodal gateways. The container van has become the foundational unit of intermodal efficiency, enabling seamless transfers between ocean carriers, rail networks, and trucking fleets. Yet, beneath the headline growth trajectory, the industry is navigating a period of pronounced transition. Capacity utilization patterns, regional trade realignments, and the economics of manufacturing consolidation are reshaping competitive dynamics. Stakeholders across the value chain are confronting a landscape where scale, cost discipline, and specification differentiation increasingly determine long-term positioning.
Several interrelated challenges define the current inflection point. First, the sector operates under intense cost pressure tied to the volatility of core input materials. The economics of container production remain tightly coupled to steel pricing, and fluctuations in metallurgical markets transmit directly into manufacturing margins, pricing strategies, and order book planning. Second, the industry must reconcile sustained demand growth with evolving compliance and safety requirements that govern structural performance, load ratings, and international approval standards. Containers that fail to meet recognized testing protocols or safety certifications face exclusion from global service networks, making regulatory alignment a non-negotiable operational baseline. Third, the market is experiencing a gradual divergence in demand profiles across application areas. The core volume driver remains firmly anchored in maritime shipping, where standardized units enable high-throughput port operations and dense vessel utilization. At the same time, land transport corridors are generating incremental demand for durable, road-compliant units that support inland distribution and cross-border logistics, while storage and modular construction applications create niche but meaningful utilization pathways for surplus and repurposed inventory. These overlapping pressures require operators to balance volume ambitions with cost control, compliance rigor, and application-specific engineering.
Key Forces Propelling Market Evolution
The trajectory of the container vans market is being shaped by a set of reinforcing drivers that extend well beyond simple freight volume growth. Understanding these forces is essential for decision-makers seeking to align capacity planning, procurement strategy, and investment priorities with where the market is actually heading.
Technological innovation and manufacturing precision have become central to competitive differentiation. While the fundamental design of the container van remains anchored in ISO-compliant geometry, advances in fabrication workflows, material utilization, and quality assurance are reshaping cost structures and product consistency. High-volume producers have progressively integrated more controlled welding processes, automated inspection routines, and tighter tolerance management to reduce structural variability and improve durability under repeated loading cycles. These improvements matter because container vans are subject to harsh operational environments, including salt exposure, stacking pressure, and repeated handling across congested terminal operations. Manufacturers that can deliver more consistent structural performance while containing unit costs are better positioned to secure long-term supply agreements with shipping lines and freight forwarders that prioritize reliability and reduced maintenance downtime.
Policy and regulatory frameworks continue to impose discipline on the market, but they also function as a filter that rewards operational maturity. International standards governing testing, structural integrity, and load ratings establish a common technical language for container performance, enabling interoperability across global shipping networks. Safety approval regimes administered through national authorities reinforce this baseline by ensuring that units in international service meet defined structural and handling requirements. For manufacturers and operators alike, compliance is not a peripheral activity; it is an integral part of market access. The implication is that regulatory alignment increasingly rewards scale producers with established certification pipelines and repeatable quality systems, while raising the barrier for entrants that lack the institutional capacity to manage documentation, testing, and audit traceability efficiently.
Demand-side behavior is shifting in ways that extend beyond headline trade growth. The continued expansion of e-commerce and complex multinational supply chains has reinforced the need for standardized, rugged, and easily transferable container units that support rapid modal switching. Buyers are increasingly attentive not only to acquisition cost but also to lifecycle performance, including resistance to corrosion, structural fatigue, and handling wear. At the same time, shipping lines and logistics providers are evaluating container fleets through a broader operational lens, weighing factors such as stackability, space optimization on vessel cells, and the ability to maintain service reliability under variable port conditions. These preferences gradually elevate the importance of specification quality and consistency over pure price competition, particularly in segments where operational downtime or cargo integrity carries high financial risk.
Supply chain and cost structure dynamics represent the most immediate pressure point. Steel remains the dominant raw material in container van production, and the economics of manufacturing are closely linked to steel price behavior and regional availability. In the recent operating environment, steel pricing in major industrial markets has reflected the combined influence of infrastructure demand, energy input costs, and trade flow patterns, sustaining moderate volatility into the near term. Because new production costs track these material inputs closely, manufacturers face a continuous challenge in managing margin stability while preserving competitive pricing for volume customers. This dynamic is magnified by the concentration of manufacturing capacity in key production regions, which can amplify the impact of localized demand swings, logistics bottlenecks, or input scarcity. The resulting environment favors operators with disciplined procurement strategies, diversified sourcing options, and the ability to pass through or absorb cost fluctuations without disrupting order fulfillment.
Competitive Landscape and Strategic Positioning
The competitive architecture of the container vans market is characterized by a high degree of concentration among established manufacturers with broad production scale, global distribution reach, and strong integration with shipping and logistics networks. This concentration is not accidental; it reflects the capital intensity of container manufacturing, the importance of certification and compliance infrastructure, and the value that large buyers place on dependable supply and uniform specification quality.
Several major producers illustrate the dominant strategic models in the market. Large-scale manufacturers headquartered in China have built global leadership by emphasizing high-volume output of ISO-compliant dry van and specialized units, supported by multiple production facilities designed to serve international intermodal demand. Their advantage lies in the ability to combine scale, breadth of product range, and efficient cost structures while maintaining close links to port infrastructure and shipping line procurement cycles. Other significant players have pursued similar strategies with varying degrees of specialization, expanding their offerings across dry freight, special-purpose, and container van products to capture demand across both standard and differentiated applications. Meanwhile, select European-linked producers have positioned around higher-specification and refrigerated container vans, emphasizing quality, durability, and integration with broader logistics operations. This specialization matters because reefer and high-performance units typically command different procurement logic, with greater emphasis on thermal performance, equipment reliability, and lifecycle service support.
PW Consulting
Differentiation in this market is increasingly defined by three overlapping dimensions. The first is scale and supply reliability. Large buyers prioritize manufacturers who can meet sustained order volumes without disruption, particularly when fleet replacement cycles and network expansion plans require predictable delivery schedules. The second is specification performance and compliance maturity. Operators that can demonstrate consistent structural integrity, standardized testing alignment, and robust safety approval processes gain an advantage in segments where service continuity and cargo protection are critical. The third is application-specific engineering and product breadth. As demand evolves across maritime shipping, land transport, and storage or modular construction use cases, manufacturers with the ability to tailor unit configurations while preserving core standardization can capture value beyond undifferentiated volume competition.
The market structure also shows signs of gradual evolution. Consolidation pressures remain relevant where scale economies, certification overhead, and global distribution requirements favor larger, well-capitalized producers. At the same time, segmentation continues to create space for focused players that serve specific application niches or regional demand pockets. New entry remains challenging due to the combination of material cost exposure, compliance burden, and the importance of entrenched buyer relationships, but it is not impossible for producers that bring clear cost advantages, specialized engineering capabilities, or strategic alignment with emerging logistics corridors. The overall direction points toward a landscape where competitive advantage is less about isolated unit pricing and more about the integration of manufacturing discipline, product reliability, and customer-specific service model alignment.
Forward Outlook: Three Trends Shaping the Next Era
The next three to five years are likely to be shaped by a combination of demand momentum, cost discipline, and operational specialization. Several trends stand out as particularly consequential for strategic planning.
Steady growth anchored in intermodal standardization. Global trade activity and e-commerce-driven logistics complexity are expected to continue supporting demand for standardized container vans that enable efficient movement across sea, rail, and road. The market’s projected compound growth trajectory reflects this foundational role rather than speculative expansion. The opportunity here lies not simply in volume but in capturing demand from corridors and customer segments where reliability, turnaround speed, and fleet consistency deliver measurable operating advantages.
Cost volatility as a permanent management challenge. Because production economics remain closely linked to steel pricing and manufacturing concentration patterns, material cost volatility is likely to persist as a central operational concern. The strategic response will increasingly involve procurement diversification, inventory and order timing optimization, and pricing frameworks that protect margin without eroding customer relationships. Companies that treat input cost management as a core capability rather than a periodic reaction will be better positioned to navigate fluctuations without sacrificing competitiveness.
Specification and application differentiation gaining relative importance. As maritime shipping continues to anchor the largest share of demand, growth opportunities will also emerge from land transport intensifications and storage or modular construction utilization. These segments create incremental value for units with specific durability characteristics, handling resilience, or configuration flexibility. Over time, the market is likely to reward manufacturers and buyers who can match product attributes to application requirements rather than relying on uniform, lowest-common-denominator procurement. This shift creates opportunities for targeted product development, more precise fleet planning, and stronger supplier-customer alignment around operational objectives.
Worldwide Container Dumper Market
These trends carry embedded uncertainty. Trade policy shifts, port congestion dynamics, energy and input cost shocks, and the pace of logistics network modernization can all alter regional demand patterns and procurement timing. Similarly, any acceleration in regulatory expectations around safety, testing, or lifecycle performance would raise the operational bar for market participation. Decision-makers should therefore treat the medium-term outlook as directional rather than deterministic, using scenario planning to evaluate how shifts in trade flows, material costs, and compliance requirements might affect capacity deployment and sourcing choices.
Container Leasing Market
Strategic Implications for Key Stakeholders
For manufacturers and producers, the priority is to reinforce the strategic value of scale, compliance maturity, and specification consistency. Investing in process control, quality traceability, and application-aligned product breadth can strengthen positioning with buyers who increasingly assess total operational value rather than unit price alone. Proactive management of material cost exposure and delivery reliability should be treated as central competitive capabilities, especially in an environment where input volatility and concentration amplify margin risk.
For investors and capital allocators, the market presents a profile of steady structural demand combined with concentration and cost sensitivity. Opportunities are most compelling where operators demonstrate durable manufacturing efficiency, broad product capability, and the ability to serve high-value segments such as refrigerated or higher-specification container vans. At the same time, exposure to raw material volatility and regional demand cyclicality warrants disciplined due diligence on cost management, customer concentration, and the resilience of order pipelines across different trade environments.
For procurement leaders and logistics operators, the strategic emphasis should shift from transactional price comparison toward fleet performance, service continuity, and specification fit. Aligning container procurement with actual operational requirements across maritime, land, and storage or modular use cases can reduce downstream risk and improve total cost outcomes. Building stronger visibility into supplier production capacity, certification standing, and material sourcing strategy can also improve resilience when demand spikes or input markets become unsettled.
For executives seeking to act on these dynamics with precision, detailed segmentation data, pricing context, regional demand patterns, and company-level benchmarks provide the kind of granular intelligence that supports targeted capital allocation, sourcing strategy, and product planning. A comprehensive market report can help translate the broad structural trends outlined here into decision-ready detail tailored to specific segments and operational priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Container Vans Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


