



Soft Tissue Repair Mesh Market: 5 Strategic Shifts Reshaping Growth to $6.68B by 2032

Strategic Trends and Commercial Opportunities in the Global Soft Tissue Repair Mesh Market
Market Landscape and Core Challenges
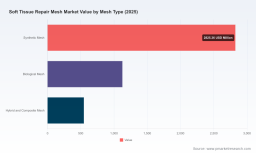
The global soft tissue repair mesh market has demonstrated resilient expansion over the past five years, establishing itself as a critical component within the broader surgical devices sector. Valued at approximately 4.5 billion USD in 2025, the market has recovered from a period of stagnation and litigation-driven caution that characterized the early 2020s. Historical trajectories indicate a steady climb from roughly 3.37 billion USD in 2020, reflecting an industry that has successfully navigated regulatory headwinds to return to a growth trajectory. Looking ahead, the market is projected to expand at a compound annual growth rate of 5.81 percent through 2032, suggesting a mature yet evolving landscape where value creation depends on innovation rather than volume alone.
Despite this positive outlook, the industry stands at a significant inflection point defined by heightened scrutiny and shifting clinical preferences. One of the primary challenges involves the complex regulatory environment surrounding product safety and transparency. While mesh products for hernia repair generally maintain Class II classification, specific applications such as transvaginal pelvic organ prolapse have faced severe restrictions due to long-term safety concerns. This dichotomy creates a fragmented market where manufacturers must differentiate rigorously between product categories to avoid reputational spill-over effects. The increased demand for transparency is reshaping how products are labeled and marketed, forcing companies to provide more clinically relevant mechanical data on packaging to facilitate safe use.
Furthermore, the market concentration remains high, with the top few players commanding a significant share of total revenue. This consolidation poses barriers to entry for smaller innovators while simultaneously pressuring incumbent leaders to maintain portfolios that satisfy diverse surgical needs. A second critical challenge lies in the reimbursement landscape. Payment rates for procedures involving mesh implantation vary widely based on complexity and setting, creating economic pressure on healthcare providers. These reimbursement constraints influence procurement decisions, often favoring cost-effective synthetic options over premium biological alternatives unless clinical outcomes clearly justify the added expense. Consequently, manufacturers face the dual challenge of proving superior clinical efficacy while navigating tight hospital budgets.
Finally, the supply chain for raw materials and manufacturing capacity remains a point of vulnerability. As demand shifts toward specialized composite and hybrid meshes, the ability to scale production without compromising quality becomes a strategic differentiator. These challenges collectively suggest that future growth will not be uniform across all segments but will instead favor companies that can balance regulatory compliance, clinical evidence, and economic efficiency.
Key Drivers of Market Change
Several fundamental factors are propelling the soft tissue repair mesh market forward, transforming it from a commodity-driven space into one defined by technological differentiation. The most prominent driver is technological innovation in material science. There is a marked shift away from traditional heavyweight synthetics toward lightweight, composite, and bioresorbable options. Manufacturers are increasingly developing meshes that integrate with host tissue more effectively, reducing foreign body responses and chronic pain. For instance, the recent regulatory clearance for electrospun fiber matrices highlights the industry's movement toward advanced structures that mimic natural tissue properties. This innovation is not merely about material composition but also about structural design, such as macroporous configurations that allow for better tissue ingrowth while maintaining mechanical strength.
Regulatory dynamics are simultaneously acting as both a constraint and a catalyst. While the FDA has tightened oversight on specific high-risk applications, the pathway for hernia repair meshes remains well-defined under the 510(k) clearance process. However, the recent draft guidance recommending standardized package labeling indicates a push toward greater transparency. This regulatory evolution forces companies to invest more heavily in clinical data generation and labeling compliance. Rather than hindering growth, this environment tends to favor larger, well-resourced organizations that can absorb the costs of compliance and clinical trials. It effectively raises the barrier to entry, consolidating the market around players who can demonstrate robust safety profiles and provide clear usage guidelines.
On the demand side, the aging global population and the rising prevalence of conditions requiring soft tissue reconstruction are driving volume. Hernia repair remains the dominant application, supported by consistent surgical rates across developed and developing regions. However, there is growing interest in pelvic organ prolapse and breast reconstruction, provided safety concerns are adequately addressed through improved product design. Surgeons are increasingly seeking solutions that reduce recurrence rates and minimize complications, which drives demand for higher-performance meshes. This shift in surgeon preference influences procurement policies, pushing hospitals to adopt products that offer long-term cost savings through reduced revision surgeries, even if the upfront device cost is higher.
Supply chain and cost structures also play a pivotal role. The pressure to reduce healthcare costs globally encourages the adoption of efficient manufacturing processes and cost-effective synthetic materials. Yet, the rise of biological and hybrid meshes suggests a premium segment is emerging for complex cases where synthetic options are contraindicated. Companies are responding by optimizing their supply chains to support diverse product lines, ranging from mass-market synthetics to specialized biologics. This dual approach allows manufacturers to capture volume in standard procedures while maintaining margins in specialized applications. The interplay between reimbursement rates and device pricing continues to shape adoption patterns, with economic factors often determining the speed at which new technologies penetrate the market.
Worldwide Hernia Mesh Devices Market
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of large diversified medical device conglomerates and specialized niche players. The market concentration is significant, with the top three companies holding a substantial portion of total revenue. This structure implies that competitive advantage is often derived from portfolio breadth and global distribution networks rather than single-product superiority. Leading players such as Johnson & Johnson and Medtronic leverage their extensive surgical portfolios to offer comprehensive solutions, integrating meshes with fixation devices and surgical tools. Their strategy focuses on maintaining market leadership through continuous product iteration and strong relationships with surgical communities. For these giants, the ability to offer a range of options—from synthetic to composite—allows them to address various clinical scenarios while mitigating risk associated with any single product line.
Specialized manufacturers employ different strategic maneuvers. Companies like BD, formerly associated with Bard, focus on expanding portfolios that include bioresorbable options like Phasix, catering to surgeons seeking long-term safety without permanent implantation. Recent commercial launches of absorbable hernia patches highlight a strategy centered on innovation in material absorption rates and handling characteristics. Similarly, companies like TELA Bio and Organogenesis focus on regenerative medicine and reinforced tissue matrices. Their value proposition lies in providing alternatives for patients where synthetic meshes pose higher risks, thereby capturing a premium segment willing to pay for biologic properties. These players often invest heavily in clinical evidence to support reimbursement claims and differentiate themselves from standard synthetic offerings.
The landscape is also evolving through strategic partnerships and acquisitions. Larger entities often acquire innovative smaller firms to gain access to novel technologies or specific market segments without developing them internally. This trend accelerates the integration of new materials like electrospun fibers into established product lines. Meanwhile, the regulatory environment acts as a filter. Recent FDA actions regarding pelvic organ prolapse meshes have reshaped the competitive field, removing certain products from the market and redirecting demand toward safer alternatives. This dynamic benefits companies with strong compliance records and diversified portfolios that are not overly exposed to high-risk applications. The result is a market where stability and trust are becoming as valuable as technological features.
PW Consulting
New entrants face a challenging path. While the 510(k) pathway provides a mechanism for market access, the reputational risks associated with mesh products require careful positioning. Success for new players often depends on identifying underserved niches, such as specific anatomical repairs or regions with growing surgical volumes. The presence of established global players means that pricing pressure is inevitable, pushing innovators to demonstrate clear clinical advantages that command premium pricing. Overall, the competitive dynamics suggest a market moving toward consolidation among top players while allowing room for specialized innovators who can navigate regulatory complexity and prove distinct clinical value.
Future Trends and Commercial Implications
Looking toward the next three to five years, several trends are likely to define the trajectory of the soft tissue repair mesh market. First, the differentiation between synthetic and biological meshes will become more nuanced. Rather than a binary choice, hybrid and composite meshes are expected to gain prominence, offering a balance of mechanical strength and biocompatibility. This trend creates opportunities for manufacturers who can successfully engineer materials that degrade at controlled rates while providing sufficient support during the healing phase. The commercial implication is a shift in R&D focus toward material science that can justify premium pricing through reduced long-term complications.
Second, regulatory transparency will continue to intensify. The move toward standardized labeling and clearer communication of mechanical properties suggests that future market access will depend heavily on how well a product's performance is documented and communicated. Companies that proactively align with these regulatory shifts will gain trust among surgeons and procurement teams. This environment may slow the adoption of unproven innovations but will strengthen the position of established products with robust data packs. For investors, this signals a preference for assets with clear regulatory pathways and strong intellectual property protection around material composition and labeling data.
Third, regional dynamics will play an increasingly important role. While mature markets drive revenue through high-value products, emerging regions offer volume growth driven by increasing surgical access. However, reimbursement constraints in developed markets may push cost-sensitive innovations toward emerging economies. A potential risk lies in the variability of regulatory standards across regions, which can complicate global launches. Companies must balance the need for standardized products with the flexibility to adapt to local reimbursement and clinical preferences. The uncertainty surrounding long-term safety data for certain applications remains a persistent risk, potentially impacting adoption rates if new safety signals emerge. Success in this environment requires agility in product positioning and a deep understanding of local market nuances.
Worldwide Inguinal Hernia Repair Mesh Market
Strategic Actions for Decision Makers
For manufacturers, the priority should be to strengthen clinical evidence packages that support both safety and cost-effectiveness. Investing in data that demonstrates reduced revision rates or faster recovery times can justify premium positioning and align with value-based care initiatives. Companies should also monitor regulatory guidance closely to ensure labeling and marketing materials meet evolving transparency standards, reducing the risk of compliance issues.
Investors evaluating opportunities in this sector should focus on companies with diversified portfolios that are not overly reliant on high-risk applications. Technologies that offer unique material properties or clear pathways to reimbursement are more likely to sustain growth. Due diligence should include a thorough assessment of regulatory clearance status and the strength of intellectual property surrounding material innovations.
Procurement leaders and healthcare providers need to balance cost considerations with long-term patient outcomes. Selecting meshes that offer proven safety profiles and align with reimbursement structures can optimize procedure costs over time. Engaging with suppliers who provide comprehensive training and data support can also improve surgical consistency and outcomes. Access to detailed segmentation data and customized market intelligence is essential for navigating these complex decisions effectively.
For detailed analysis of this topic, please visit the official page: Worldwide Soft Tissue Repair Mesh Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


