



Bio-based Ethylene Glycol Market: Why 8.25% CAGR and Asia Pacific Leadership Change Everything

The Strategic Inflection Point: Worldwide Bio-based Ethylene Glycol Market Trends and Commercial Opportunities
1. Market Reality: Navigating Scale, Sustainability Mandates, and Feedstock Complexity
The global market for bio-based ethylene glycol has crossed a structural threshold. In 2025, worldwide revenue reached approximately USD 1,250 million, reflecting a compound annual growth rate of 8.25 percent projected through 2032. The trajectory since 2020 reveals a market that has matured beyond early experimentation into a phase of disciplined scaling, with values moving from USD 890.5 million in 2020 to USD 1,194.92 million in 2024 before stabilizing at the current baseline. This growth pattern is not linear; it reflects the interplay of capacity ramp-ups, feedstock availability, and the pace at which downstream customers are willing to integrate renewable building blocks into established supply chains.
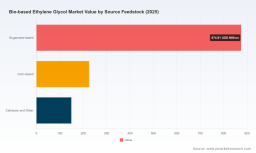
Three structural tensions define the current operating environment. First, feedstock economics remain the primary variable in cost competitiveness. Sugarcane ethanol, molasses-derived bio-ethanol, and corn-based dextrose each carry distinct agricultural, logistical, and carbon-intensity profiles, creating regional asymmetries in both supply reliability and margin structure. Producers must navigate commodity volatility while maintaining sustainability credentials that downstream buyers increasingly demand.
Second, certification and traceability have shifted from optional compliance to commercial prerequisites. The adoption of frameworks such as ISCC Plus in European markets underscores a broader reality: sustainability claims now require verifiable chain-of-custody documentation. This raises the operational bar for producers and introduces administrative complexity that smaller or regionally confined players must absorb to remain viable in premium channels.
Third, the market exhibits a moderate degree of concentration, with the top three players holding approximately 42.5 percent of revenue and the top five capturing 61.2 percent. This concentration signals that scale, feedstock integration, and established commercial relationships still confer meaningful advantages. At the same time, it leaves room for specialized entrants and joint ventures that can bring differentiated technology or regional feedstock access, particularly as lignocellulosic pathways move from pilot validation toward commercial deployment.
2. Core Drivers Reshaping the Market Trajectory
Technological Innovation and Feedstock Diversification
The most consequential shift in the bio-based ethylene glycol landscape is the parallel advancement of first-generation and second-generation feedstock pathways. Sugarcane ethanol remains the commercially mature and cost-competitive anchor, particularly in regions with established agricultural ethanol infrastructure. Corn-based dextrose has gained traction where corn processing capacity and dextrose economics align with industrial-scale conversion. Meanwhile, second-generation lignocellulosic feedstocks, including corn stover, wheat straw, and bagasse, are increasingly viewed as a strategic lever to reduce reliance on food-grade sugars and lower feedstock costs by an estimated 25 to 35 percent over the medium term.
PW Consulting
This diversification is not merely an academic improvement; it directly affects capacity planning and geographic positioning. Recent developments illustrate the trend: UPM has progressed toward introducing wood-sourced bio-based monoethylene glycol at its Leuna biorefinery in Germany, targeting around 220,000 tons of lignocellulosic-based output. In parallel, a Chinese pilot plant technology using corn stalks and straw sugars has achieved approximately 1,000 metric tonnes of annual capacity, supported by over 40 patents that point to potential scale-up. These signals suggest that feedstock flexibility will increasingly determine where production can be economically located and which customer segments can be reached without compromising carbon or cost targets.
Policy, Regulation, and Certification Dynamics
Regulatory and certification frameworks are acting as both a catalyst and a gatekeeper. European markets, in particular, are reinforcing traceability expectations through mechanisms such as ISCC Plus certification, which enables documented sustainability claims for bio-based and bio-circular hydrocarbons. This dynamic raises the bar for market entry in premium segments, but it also rewards producers who can embed verification into their operating model rather than treating it as an afterthought.
The implication is twofold. For established players, certification-ready supply chains can become a commercial moat, enabling access to customers who need defensible sustainability narratives. For new entrants, the cost and complexity of certification increase the importance of early alignment with recognized standards, especially when targeting European packaging and textile customers. Policy expectations are also accelerating the value of bio-based content in applications where brands are under pressure to reduce fossil-derived inputs, which in turn strengthens demand-side pull for renewable glycol feedstocks.
Demand-Side Shifts Across Packaging, Textiles, and Industrial Applications
Demand is being reshaped by downstream customer priorities more than by any single regulatory mandate. Packaging and bottles represent the largest application segment, driven by brand-level commitments to renewable content, recyclable packaging systems, and consumer-facing sustainability messaging. Textiles and fibers form a second major demand base, where polyester producers and fiber manufacturers are increasingly seeking bio-based building blocks to differentiate in highly competitive markets. Industrial and coolant applications, while smaller in scale, provide steady demand that can help stabilize utilization rates during periods of feedstock or pricing volatility.
The commercial pattern emerging here is one of selective adoption rather than blanket replacement. Downstream customers are not uniformly switching to bio-based ethylene glycol; they are prioritizing applications where the sustainability narrative translates into tangible brand value or regulatory alignment. This creates a premium corridor for producers who can deliver consistent quality, traceability, and reliable volume, while also leaving room for conventional or blended solutions in cost-sensitive segments.
Supply Chain Configuration and Cost Structure Evolution
Cost structures are being redefined by geography, feedstock logistics, and the economics of scale. Brazil’s access to sugarcane ethanol, India’s molasses-based bio-ethanol ecosystem, and North America’s corn-based dextrose infrastructure create distinct cost baselines that influence where bio-based ethylene glycol can be produced most efficiently. At the same time, second-generation feedstocks are broadening the opportunity set by enabling utilization of agricultural residues that may offer lower input costs and reduced exposure to food-commodity volatility.
Recent commercial activity reflects this reconfiguration. Braskem continues to evaluate a joint venture for biobased ethylene glycol production from corn dextrose in Indiana as part of its renewable chemicals portfolio, while its Sustainea joint venture with Sojitz is advancing a planned USD 400 million facility in Lafayette, Indiana to convert corn-based dextrose into monoethylene glycol at commercial scale, with startup targeted from 2028. These moves indicate that North America is becoming an increasingly relevant arena for corn-based renewable glycol, complementing established sugarcane and molasses routes elsewhere.
3. Competitive Landscape and Leadership Strategies
Established Leaders and Differentiated Positioning
The competitive field includes players with distinct feedstock access, technology routes, and geographic advantages. India Glycols Limited operates as one of the largest commercial producers of bio-based monoethylene glycol from molasses-based bio-ethanol, with long-standing industrial-scale production supplying PET, polyester, and related applications. Its scale and established customer relationships provide a durable base in segments where reliability and volume matter. Braskem and the Sustainea joint venture are strengthening the corn-based and sugarcane-ethanol pathways, leveraging existing bio-ethanol platforms and partnerships to advance renewable monoethylene glycol for packaging and textiles.
Avantium is pursuing a technology-led differentiation through its PlantMEG offering, developed via proprietary Ray Technology from renewable sugars, with an emphasis on plant-based monoethylene glycol for sustainable PET and polyester applications. UPM is positioning around lignocellulosic feedstock, using wood-sourced material at its Leuna biorefinery to target packaging and fiber markets with a lower food-grade-sugar dependency. Together, these players illustrate a market that is not converging on a single winning route, but rather segmenting by feedstock, technology, and end-use positioning.
Bio Methanol Market
Strategic Themes Among Leaders
Several patterns stand out in how leading participants are positioning themselves:
- Feedstock integration as a strategic asset. Companies with access to sugarcane ethanol, molasses-based bio-ethanol, or corn-based dextrose can better manage input risk and anchor cost structures, especially where agricultural-platform synergies exist.
- Commercial readiness over pilot novelty. Scale-up decisions are increasingly driven by the ability to deliver consistent volume and certification-ready supply, not simply by technical feasibility. The planned Sustainea facility and UPM’s Leuna preparation reflect a focus on commercial execution timelines.
- Application-aligned messaging. Successful positioning tends to connect bio-based glycol to specific downstream value, whether in packaging sustainability, polyester differentiation, or industrial reliability, rather than presenting the product as a generic renewable substitute.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The landscape is evolving along multiple axes. Concentration at the top suggests that scale and established distribution relationships remain important, particularly for large-volume contracts. At the same time, technology differentiation and regional feedstock opportunities are enabling specialized entrants to compete in defined niches. The rise of lignocellulosic pathways and regional corn-based dextrose projects adds further fragmentation potential, especially if cost and carbon-intensity advantages translate into commercial advantage at scale.
A plausible trajectory is selective consolidation in volume-driven segments paired with continued differentiation in technology-led or application-focused segments. New entrants will need either a credible feedstock advantage, a defensible conversion technology, or strong downstream partnerships to avoid being squeezed between established scale players and premium sustainability positioning.
4. Forward Outlook: Where the Market Is Heading
Over the next three to five years, the market is likely to be shaped by three interlocking trends. First, lignocellulosic and residue-based feedstocks will move from proof-of-concept toward early commercial relevance. If cost reduction targets in the 25 to 35 percent range are realized at scale, these pathways could broaden geographic options and reduce exposure to food-grade sugar volatility. This would create opportunities for producers and partners who can secure reliable residue supply and operate conversion assets efficiently.
Second, certification and traceability will increasingly function as commercial infrastructure rather than a compliance layer. Customers in Europe and other regulated or brand-sensitive markets will continue to reward documented sustainability claims, which means the ability to provide chain-of-custody assurance may become as important as price and volume. This favors organizations that build traceability into procurement, production, and logistics from the outset.
Third, regional supply chains will become more distinct. Sugarcane-linked routes will remain strong where ethanol infrastructure is mature, corn-based dextrose routes will expand in North America, and lignocellulosic projects will test the viability of non-food feedstocks in new locations. The result will be a more geographically diversified market, with regional cost and carbon profiles influencing where bio-based ethylene glycol is produced and purchased.
These trends create commercial opportunity, but also uncertainty. Feedstock availability can shift with agricultural cycles and competing demand from fuels and other bio-based chemicals. Scale-up risk remains real, particularly for second-generation pathways that must prove reliability at commercial volumes. Pricing dynamics may also pressure margins if conventional glycol costs move favorably or if multiple capacity additions converge faster than downstream adoption. The strategic response is to treat these uncertainties as variables to be actively managed through feedstock diversification, certification readiness, and application-targeted commercial strategy.
5. Decision-Maker Playbook: Actionable Priorities
For Manufacturers and Producers
Prioritize feedstock flexibility and certification readiness as core operational capabilities, not peripheral initiatives. Evaluate whether existing or planned capacity aligns with the most defensible feedstock route in your target geography, and build traceability into production and logistics early so sustainability claims can support commercial positioning. Where possible, structure partnerships or joint ventures that reduce scale-up risk while securing access to either established feedstocks or emerging lignocellulosic supply.
For Investors
Focus on the intersection of feedstock economics, technology readiness, and downstream demand quality. The most attractive opportunities are likely to combine credible feedstock access, a clear path to commercial-scale conversion, and customers who can absorb a sustainability premium or achieve regulatory alignment. Monitor capacity announcements, pilot-to-commercial transitions, and certification developments as indicators of which pathways are moving from potential to execution.
Polyethylene Glycol (PEG) Market
For Procurement and Supply Chain Leaders
Align bio-based ethylene glycol sourcing with application value rather than treating it as a blanket substitution. Identify segments where renewable content strengthens brand positioning, regulatory compliance, or customer relationships, and secure supply from partners who can provide verifiable traceability and consistent quality. Diversify feedstock exposure where feasible to reduce vulnerability to regional commodity swings or certification gaps.
For organizations seeking a deeper, segment-level view of regional dynamics, feedstock pathways, application mixes, and company-level strategic positioning, the full research report provides more granular data and tailored recommendations to support planning across these rapidly evolving market conditions.
For detailed analysis of this topic, please visit the official page: Worldwide Bio-based Ethylene Glycol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


