



Worldwide LED Tube Covers Market: What 5.5% CAGR Reveals About Commercial Lighting Dynamics

Strategic Trends and Commercial Opportunities in the Global LED Tube Covers Market
Market Overview and Core Challenges
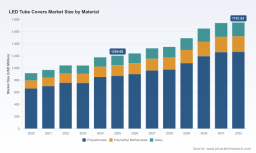
The global market for LED tube covers has demonstrated consistent expansion over the past half-decade, evolving from a niche component segment into a critical element of the broader linear lighting supply chain. Valued at approximately 915.2 million USD in 2020, the market reached 1204.08 million USD by 2025, reflecting a compound annual growth rate of 5.5 percent through the forecast period extending to 2032. This trajectory underscores a structural shift in how lighting manufacturers approach tube assembly, where protective and diffusive covers are no longer treated as commodity afterthoughts but as engineered components that directly influence light quality, thermal management, and regulatory compliance.
Despite the positive growth signals, the industry currently navigates several interconnected challenges that will define competitive dynamics in the near term. The first challenge revolves around material cost volatility and geographic price dispersion. Polycarbonate, which dominates the material mix for LED tube covers, has experienced notable price fluctuations across major production hubs. In early 2026, polycarbonate prices in Northeast Asia were recorded at 1.92 USD per kilogram, while European buyers faced rates of 3.38 USD per kilogram, with Southeast Asia and North America positioned at intermediate levels. These regional discrepancies create uneven input cost structures for manufacturers operating across multiple supply chains, forcing difficult decisions around sourcing localization, inventory buffering, and final pricing strategies.
A second challenge lies in the accelerating regulatory push toward phasing out legacy fluorescent technologies. The European Union's RoHS Directive restrictions on mercury have effectively driven bans on common linear fluorescent tubes, creating a rapid conversion cycle toward LED alternatives that rely heavily on polycarbonate or compatible housing solutions. Simultaneously, several U.S. states, including California, Colorado, and Maryland, have implemented or scheduled bans on linear fluorescent lamps between 2024 and 2026, further compressing the remaining replacement market and shifting procurement cycles toward full LED system adoption. While this regulatory momentum fuels demand, it also compresses the timeline for manufacturers to scale compliant designs, source certified materials, and align distribution channels with accelerated retrofit schedules.
The third challenge emerges from shifting trade policies and their ripple effects on component assembly costs. Recent increases in U.S. tariffs on steel and aluminum imports during 2025 have directly impacted the cost structure of aluminum bases paired with polycarbonate covers in LED tube assemblies. For manufacturers that rely on integrated metal-and-polymer designs, this tariff environment introduces margin pressure and complicates regional sourcing strategies, particularly for companies balancing domestic production against imported component dependencies. Collectively, these challenges signal a market that is growing but increasingly stratified, where cost discipline, regulatory foresight, and supply chain agility will separate resilient players from those reliant on legacy pricing models.
Key Growth Drivers
The momentum behind LED tube covers is anchored in a convergence of technological, regulatory, and demand-side forces that are reshaping both product design priorities and procurement behaviors across commercial, industrial, and residential applications.
Technological Innovation and Material Performance
Advancements in polycarbonate extrusion and surface treatment technologies have elevated the functional role of LED tube covers beyond simple optical diffusion. Modern covers are increasingly engineered to balance light uniformity, impact resistance, and thermal dissipation, enabling manufacturers to offer retrofit solutions that closely match or exceed the performance characteristics of legacy fluorescent fixtures. The availability of fire-retardant polycarbonate extrusions tailored for high-voltage markets has become particularly relevant for North American applications, where compliance with UL standards and safe operation across 110V-120V systems are non-negotiable requirements. Guidance released by leading component suppliers in late 2025 and early 2026 has emphasized the importance of matching cover material specifications with aluminum profile designs to ensure structural integrity, thermal stability, and regulatory alignment. This growing emphasis on engineered compatibility reflects a broader industry shift toward integrated component thinking, where covers, housings, and bases are co-optimized rather than sourced as independent commodities.
PW Consulting
Surface finish innovation also continues to drive differentiation. Frosted and diffused finishes remain the most widely adopted option for general lighting applications, offering predictable light distribution and glare reduction across broad installation footprints. Clear and transparent variants serve niche requirements where maximum light output or visual inspection of internal components is prioritized, while prismatic and striated designs are gaining traction in settings that demand controlled beam patterns or architectural lighting effects. The ability to offer a spectrum of surface finishes from a single production line has become a competitive lever for manufacturers aiming to serve multiple end-use segments without fragmenting operational efficiency.
Policy and Regulatory Catalysts
Regulatory pressure on mercury-containing fluorescent lighting has emerged as one of the most powerful accelerators for LED tube cover demand. At the European level, RoHS-driven restrictions have effectively curtailed the availability of common linear fluorescent tubes, forcing facility managers and electrical contractors to transition toward LED retrofit assemblies that incorporate durable polycarbonate or compatible housing solutions. The same dynamic is unfolding across multiple U.S. states, where legislative actions and scheduled phase-out dates have created a fragmented but accelerating compliance landscape. These regulatory shifts do more than simply replace one light source with another; they fundamentally alter procurement cycles, technical specification requirements, and the speed at which distributors and installers must adapt their inventory and skill sets.
For manufacturers and suppliers, the regulatory environment presents both a demand tailwind and a compliance burden. Products destined for regulated markets must meet increasingly stringent performance, safety, and environmental criteria, which in turn raises the value of covers and housings that contribute to overall system certification. Companies that proactively align their material sourcing, testing protocols, and documentation with regional requirements are better positioned to capture conversion-driven demand, while those that treat regulatory compliance as a reactive exercise risk delays, rework, and margin erosion.
Demand-Side Shifts and Retrofit Economics
On the demand side, the economic case for LED tube retrofits continues to strengthen as energy prices fluctuate and sustainability targets become embedded in corporate and municipal procurement policies. Commercial lighting remains the largest application segment for LED tube covers, driven by offices, warehouses, retail spaces, and institutional facilities that prioritize long-term operating cost reduction and minimal disruption during fixture upgrades. Industrial facilities represent a rapidly growing demand pool, particularly in environments where robust cover materials must withstand dust, moderate impact, and thermal stress while maintaining consistent illumination quality. Residential adoption, while smaller in absolute terms, is expanding as homeowners and multifamily property managers replace aging fluorescent fixtures with LED solutions that offer improved aesthetics, lower maintenance, and compatibility with smart lighting ecosystems.
A notable behavioral shift is the growing preference for integrated LED tube solutions that bundle covers, housings, and bases into cohesive product packages. Electrical contractors and facility managers increasingly favor supply chains that reduce assembly complexity, minimize compatibility risk, and provide clear warranty and support pathways. This preference rewards manufacturers that design covers as part of a complete system rather than as standalone components, while challenging suppliers that rely on fragmented, multi-vendor procurement models.
Supply Chain and Cost Structure Dynamics
The cost structure of LED tube covers is being reshaped by regional material pricing, trade policy adjustments, and evolving manufacturing footprints. Polycarbonate pricing divergence across Asia, Europe, and North America requires manufacturers to make strategic choices about where to source raw materials, how much inventory buffer to maintain, and whether to localize production to reduce exposure to freight volatility and tariff barriers. The 2025 increase in U.S. tariffs on steel and aluminum imports has added a layer of complexity for assemblies that combine aluminum bases with polycarbonate covers, prompting some manufacturers to reevaluate bill-of-materials composition, explore alternative metal sourcing, or adjust finished product pricing to preserve margins.
At the same time, economies of scale in polycarbonate extrusion and surface finishing are gradually improving cost predictability for high-volume producers, particularly those that have invested in dedicated lines for LED tube cover profiles. The combination of scale benefits, material innovation, and more disciplined procurement practices is enabling a subset of manufacturers to offer competitive pricing without sacrificing compliance or performance quality. This dynamic is likely to intensify as the market matures and buyers become more sophisticated in comparing total cost of ownership rather than unit price alone.
Competitive Landscape and Leading Strategies
The competitive environment for LED tube covers is characterized by a wide spectrum of participants, from specialized component manufacturers focused on polycarbonate extrusions and aluminum profiles to integrated lighting brands that offer complete T8 and T5 tube systems with compatible covers and housings. Market concentration remains relatively moderate, with the top three players accounting for approximately 18.5 percent of total revenue and the top five representing around 28.35 percent, indicating ample room for specializedplayers and regional specialists to compete on performance, compliance, and service differentiation rather than scale alone.
Several strategic positioning patterns have emerged among the leading participants. Companies such as JE Led Profile, Dachang Plastic Hardware Processing Factory, Shenzhen AOD Plastic Products, TOPPO LED Lighting, Farwise Technology, Shenzhen Syhdee, and Xiamen PVTECH illustrate the depth of China-based manufacturing capability in polycarbonate covers, aluminum-based assemblies, and custom extrusion profiles. These manufacturers often compete by offering a broad range of finish options, flexible customization for tube dimensions and surface treatments, and close alignment with domestic LED tube factories as well as international distributors. Their value proposition typically centers on production agility, material availability, and the ability to match cover specifications with aluminum profiles or integrated tube designs across multiple voltage and compliance requirements.
On the integrated lighting side, companies such as TCP Lighting, LEDVANCE, and Signify demonstrate a different strategic orientation. These firms position LED tube covers and compatible housings as part of broader professional lighting portfolios, emphasizing system-level performance, regulatory certification, and application-specific design guidance. Signify's professional trade lighting catalogues, for example, have highlighted LEDtube ranges with PC housing and cover options tailored to diverse installation contexts, while TCP's Select Series has incorporated glass and PC-compatible housings for commercial retrofit scenarios. LEDVANCE has similarly emphasized high-performance tube designs suitable for various covers and external systems. This integrated approach allows these companies to capture value not only from component sales but also from the specification, branding, and service relationships that accompany complete lighting solutions.
Recent industry developments underscore the growing importance of intellectual property, technical guidance, and compliance alignment as competitive differentiators. In early 2026, PVTECH filed a patent infringement lawsuit against Super Lighting concerning ten U.S. patents related to T8 LED tube designs, spanning housing and cover technologies. This legal action signals a broader trend in which component and system designs are becoming more heavily protected, and where the boundaries between cover extrusion, housing engineering, and tube assembly are increasingly subject to proprietary claims. Simultaneously, JE Led Profile's release of guidance on selecting PC covers and aluminum profiles for 2026 emphasized fire-retardant polycarbonate extrusions for U.S. 110V-120V markets meeting UL standards, highlighting how technical specification support is becoming a strategic tool for capturing compliance-driven demand. Signify's publication of its professional trade lighting catalogue further illustrates how leading brands are using documented product ranges and application guidance to shape procurement decisions in commercial and industrial segments.
Looking ahead, the competitive landscape is likely to evolve along two parallel tracks. The first involves consolidation and partnership activity as larger integrated lighting brands seek to secure reliable cover and housing supply, potentially through long-term contracts, joint development agreements, or selective acquisitions of specialized extrusion and assembly capabilities. The second involves continued fragmentation at the component level, where regional manufacturers differentiate through surface finish expertise, material certification, voltage-specific design support, and rapid response to local retrofit demand spikes. New entrants will find opportunities in niche finish technologies, application-specific cover designs, and supply chain models that reduce compliance risk for distributors and installers, while generic commodity players will face increasing pressure from both material cost volatility and the growing premium attached to certified, system-compatible cover solutions.
Future Trends and Commercial Implications
Over the next three to five years, several interconnected trends are likely to shape the LED tube covers market and create actionable commercial opportunities for manufacturers, distributors, and investors who align their strategies with evolving demand patterns and compliance requirements.
The first trend is the deepening integration of cover design with system-level performance and certification. As regulatory bans on fluorescent tubes continue to expand and facility managers accelerate retrofit programs, buyers will increasingly evaluate covers and housings as part of a certified, warranty-backed lighting system rather than as interchangeable parts. This shift will reward manufacturers that can document material specifications, demonstrate compliance with regional safety and environmental standards, and provide clear guidance on compatibility with aluminum bases, driver configurations, and installation conditions. Companies that invest in application-specific cover designs and maintain robust testing and documentation practices will be well positioned to capture premium segments of the retrofit market.
The second trend is the continued regional divergence in material costs and trade conditions, which will drive more localized sourcing and assembly strategies. Polycarbonate price dispersion across Northeast Asia, Europe, Southeast Asia, and North America, combined with evolving tariff structures on metals and related inputs, will encourage manufacturers to align production footprints with end-market demand clusters. This localization trend will create opportunities for regional suppliers that can offer consistent material availability, predictable pricing, and faster response times, while also challenging companies that rely on highly centralized sourcing models to absorb logistics and tariff exposure. Investors and strategic buyers should anticipate a market in which supply chain resilience and regional compliance capability become as important as unit cost competitiveness.
The third trend is the gradual expansion of cover functionality beyond diffusion and protection into areas such as enhanced thermal management, improved impact resistance, and tighter integration with smart lighting ecosystems. As LED tube installations become more common in environments that demand durable, low-maintenance solutions, covers that contribute to longer system life, reduced failure rates, and easier integration with sensors or connected controls will gain incremental value. This creates opportunities for product development teams to explore material formulations and surface architectures that support these broader performance goals, particularly in commercial and industrial segments where total cost of ownership considerations drive procurement decisions.
Potential risks and uncertainties include the pace and geographic fragmentation of regulatory implementation, which could accelerate demand in some markets while delaying it in others. Material price volatility remains a persistent threat, especially if supply disruptions or demand spikes in adjacent industries affect polycarbonate availability. Tariff and trade policy uncertainty could also reshape cost structures unexpectedly, particularly for assemblies that depend on cross-border metal and polymer components. Companies that treat these variables as static will face margin and planning challenges, while those that build flexible sourcing, pricing, and compliance strategies will be better equipped to navigate an evolving landscape.
Actionable Guidance for Decision Makers
For manufacturers, the immediate priority is to strengthen the alignment between cover material specifications, housing designs, and regional compliance requirements. Investing in fire-retardant polycarbonate options, voltage-specific guidance, and clear documentation of compatibility with aluminum bases and existing tube formats can help capture compliance-driven retrofit demand while reducing the risk of rejected specifications or delayed installations. Manufacturers should also evaluate whether to deepen relationships with regional distributors and integrated lighting brands that can accelerate market access, particularly in territories where fluorescent phase-outs are advancing most rapidly.
LED Glass Market
For investors, the opportunity lies in identifying companies that combine material supply reliability with system-level design capability and demonstrated regulatory readiness. Businesses that have developed proprietary extrusion lines, secured consistent polycarbonate sourcing, or built application-specific cover portfolios for commercial and industrial segments are better positioned to benefit from sustained retrofit momentum. Conversely, exposure to purely commodity-oriented models without clear differentiation in finish technology, certification support, or regional sourcing resilience may face margin compression as the market matures and buyers prioritize total cost of ownership over initial price.
For procurement teams and facility operators, the focus should be on reducing integration risk and long-term operating cost rather than selecting covers on unit price alone. Specifying covers and housings that are designed for compatibility with chosen LED tube formats, that meet relevant safety and environmental standards, and that are supported by clear warranty and technical guidance can simplify installation, reduce failure rates, and improve lifecycle economics. As regulatory deadlines tighten and retrofit timelines accelerate, securing reliable supply of compliant cover solutions will become a critical component of project planning and asset management.
Tonneau Covers Market
Given the pace of regulatory change, material price movement, and competitive differentiation across regions and applications, decision makers seeking to act with precision will benefit from access to more granular segmentation data, company-level profiling, and customized scenario analysis. Detailed market intelligence can help translate broad trends into specific sourcing, pricing, and product development decisions, enabling stakeholders to anticipate demand shifts, identify supply chain vulnerabilities, and prioritize investments where they are most likely to generate durable returns.
For detailed analysis of this topic, please visit the official page: Worldwide LED Tube Covers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


