



Fine Surface Oriented Strand Board FOSB Market: Why 5.85% CAGR Through 2032 Changes Everything

Fine Surface Oriented Strand Board (FOSB) Market: Navigating Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The Fine Surface Oriented Strand Board (FOSB) market has established itself as a significant segment within the broader wood-based panels industry, bridging the performance characteristics of traditional Oriented Strand Board (OSB) with the aesthetic and surface quality requirements of finer applications. Over the historical period from 2020 to 2025, the market demonstrated resilient growth, reflecting steady commercialization and increasing adoption across multiple downstream sectors. With the value expanding from approximately 939.85 million USD to 1250.0 Million in 2025, the sector has transitioned from a niche product to a recognized alternative to plywood, medium-density fiberboard (MDF), and particleboard in specific use cases. Projections for the forecast period 2026 through 2032 indicate sustained expansion, driven by broader structural demand for engineered wood products and the material's favorable strength-to-weight properties.
At the macroeconomic level, the market is characterized by a moderate consolidated structure. The top three firms hold a combined share of roughly 28.5 percent, while the top five account for about 39.2 percent of total revenue. This concentration suggests that while global capacity is distributed across multiple geographies, specialized FOSB production is still dominated by a limited number of players with the technical capability to produce fine surface layers at commercial scale. The forecast compound annual growth rate of approximately 5.85 percent through 2032 points to steady but not explosive expansion, implying that value creation will increasingly depend on differentiation, cost efficiency, and alignment with downstream application trends rather than pure volume scaling.
Despite the positive trajectory, the industry currently faces several structural challenges that are shaping competitive positioning. First, raw material security and adhesive cost exposure remain persistent concerns. FOSB production relies on specific feedstock profiles, often fast-growing eucalyptus or selected softwood strands, combined with resin systems that meet stringent surface and emission requirements. Fluctuations in wood supply dynamics and the cost of adhesives, which are influenced by petrochemical feedstock movements, introduce margin variability that producers cannot entirely pass through to downstream buyers.
Second, the market sits at a technical crossover point. FOSB must continuously justify its position against established substitutes such as MDF and high-grade particleboard, particularly in furniture manufacturing and interior finishing, where surface finish, machining behavior, and total installed cost are tightly evaluated. While FOSB offers structural advantages and surface quality improvements over standard OSB, the value proposition must be clearly articulated to specifiers and fabricators who are accustomed to traditional materials.
Third, regulatory and environmental expectations are becoming more granular across major end markets. Low formaldehyde emission classifications and other indoor air quality considerations are increasingly treated as baseline requirements rather than differentiators, especially in furniture and interior construction applications. Compliance is necessary, but it also compresses the space for premium pricing unless accompanied by genuine performance or process advantages.
Key Drivers Shaping the FOSB Market
The growth and evolution of the FOSB market are being shaped by a convergence of technological, regulatory, demand-side, and cost-structure developments. Understanding how these forces interact is essential for identifying where durable advantages can be built.
Technology and process capability remain the most distinctive driver. FOSB is not simply OSB with a cosmetic overlay; it typically integrates an OSB core with fine surface layers engineered for superior finish and structural properties. Producers investing in advanced continuous press technology and precision surface treatment are better positioned to deliver consistent panel quality, reduced variability, and surface characteristics that can compete with more traditionally processed boards. The move toward low-formaldehyde or formaldehyde-free adhesive solutions in selected product lines further illustrates how process innovation can simultaneously address performance, regulatory, and branding objectives. Where these technologies are deployed effectively, they enable FOSB to enter applications that previously favored MDF or laminated particleboard.
On the policy and regulatory side, emission standards and interior-use specifications are acting as both a constraint and an enabler. Low formaldehyde emission grades, such as E0 and E1 classifications, have become standard expectations in major markets for FOSB used in furniture and interior applications. Rather than being treated as optional premium features, these requirements are increasingly embedded in procurement specifications and building practices. This regulatory trajectory favors producers that have already integrated cleaner adhesive systems and quality control processes into their operations, while creating a barrier for capacity that cannot reliably meet tighter emission profiles at scale.
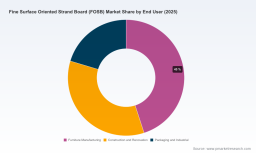
Demand-side dynamics are equally important and are shifting the center of gravity for FOSB adoption. Furniture manufacturing continues to represent a large end-use segment, where surface appearance, stability, and finish compatibility influence material selection. At the same time, construction and renovation activity sustains demand for panels that combine structural performance with improved surface qualities for exposed or semi-exposed applications. A smaller but meaningful portion of demand also comes from packaging and industrial uses, where board consistency and mechanical properties matter. What ties these segments together is a broader move toward engineered wood solutions that can reduce weight, improve dimensional stability, or offer more predictable machining behavior than conventional alternatives.
Cost structure and supply chain factors complete the picture. Wood-based panel economics are sensitive to feedstock availability, log and fiber pricing, energy costs, and resin markets. For FOSB, the use of fast-growing eucalyptus or selected softwood strands and the incorporation of specialized adhesives mean that procurement strategy is tightly linked to product positioning. Recent price signals for OSB and FOSB in key supply regions indicate a market where cost discipline matters, but where differentiation in surface quality and adhesive profile can still support value-based positioning. Producers that manage feedstock mix, press efficiency, and resin usage with greater precision are better insulated against input volatility and more capable of competing on quality rather than price alone.
Competitive Landscape and Leading Strategies
The competitive environment in FOSB is defined by a mix of established OSB producers, regional specialists, and manufacturers actively expanding fine-surface capability. The strategic positioning of leading firms reflects different combinations of technology access, feedstock strategy, geographic presence, and application focus.
Strategic Positioning Among Core Players
PW Consulting Health Care Research Center
Fletcher Building is advancing a focused FOSB strategy that emphasizes the material's superiority over particleboard and MDF in targeted applications. Its planned CEBRO Fine OSB production at the Laminex Taupo site, supported by Dieffenbacher technology, signals an intent to move beyond conventional OSB into higher-value surface panels. The timeline for commissioning of the finishing line, followed by initial board production activity in 2026, indicates a deliberate ramp-up rather than an immediate volume play, consistent with a strategy centered on qualification, application development, and downstream acceptance.
In China, Luli Group represents a scale-oriented approach, with multiple fine OSB lines operational and expanded FOSB capacity coming online through additional fine-OSB lines. The company's emphasis on low-formaldehyde formulations and advanced continuous press technology reflects an alignment with furniture and construction requirements in domestic and export markets. This positions Luli as a player that can address volume demand while maintaining attention to surface and emission specifications.
GuangXi Dekek Group adopts a more specialized premium positioning. Its use of Dieffenbacher equipment, MDI adhesive options, and eucalyptus feedstock points to a product focus on fine surface panels for furniture and decorative uses. By concentrating on premium fine surface panels, Dekek illustrates how feedstock and adhesive choices can be combined with process technology to serve higher-specification end segments rather than competing primarily on commodity board characteristics.
West Fraser and Louisiana-Pacific contribute a different competitive logic. As large North American OSB manufacturers with broad structural and specialty panel portfolios, they bring extensive capacity, supply chain scale, and market access. Their relevance to FOSB lies partly in the structural OSB base that can support fine surface applications and engineered wood product development, offering the potential to leverage existing operational strengths while expanding into higher-value panel grades where requirements permit.
In Europe, Kronospan and Egger bring established wood-based panel expertise and broad construction and furniture market reach. Kronospan's capabilities in OSB with fine surface variants and Egger's wood-based material portfolio indicate that European producers are not merely following North American or Asian FOSB developments but are shaping their own product strategies around regional application needs, emission expectations, and finish requirements.
Market Evolution and Competitive Dynamics
The overall market structure suggests a landscape in transition. With the top five firms accounting for under 40 percent of revenue, there is room for both consolidation and specialist differentiation. New capacity additions in key producing regions indicate that growth is being pursued not only by incumbents expanding within existing footprints but also by producers building dedicated fine surface lines to capture specific application demand. This points toward a market that is likely to remain somewhat fragmented at the global level while becoming more concentrated within premium FOSB niches where technology, feedstock, and qualification matter most.
Competitive advantage is increasingly likely to come from three intertwined elements: the ability to deliver consistent fine surface quality at scale, the capacity to meet low-emission expectations without compromising cost, and the strength of application-specific relationships with furniture manufacturers, construction specifiers, and industrial buyers. Firms that treat FOSB as a distinct product category with its own technical and commercial requirements are better positioned than those that view it simply as a subset of general OSB production.
OSB Sheathing Market
Future Outlook: Trends and Opportunities
Looking ahead to the 2026-2032 period, several interconnected trends are likely to shape the FOSB market and define where commercial value accrues.
The first trend is the gradual narrowing of FOSB's application footprint around segments where its combination of surface quality and structural performance delivers a clear advantage. Rather than displacing all competing boards, FOSB is likely to gain traction in furniture parts, interior fit-out components, and certain construction applications where surface finish, stability, and machining behavior are critical. This selective adoption will reward producers that invest in application development and specifiers' education rather than relying solely on board-level marketing.
The second trend is the growing importance of adhesive technology and emission performance as baseline expectations. As low-formaldehyde and formaldehyde-free options become more common in premium FOSB lines, producers that can control resin usage, achieve consistent bonding, and document emission performance will be better equipped to serve regulated interior markets. This trend also creates opportunities for differentiation through product documentation, testing, and specification support, especially in markets where compliance is expected but implementation quality varies.
Oriented Strand Board (OSB) Market
The third trend concerns supply chain and cost management. With wood and adhesive inputs remaining sensitive to broader commodity dynamics, producers that optimize feedstock mix, press efficiency, and surface layer application are likely to manage margins more effectively. In parallel, regional pricing conditions will continue to influence competitive attractiveness across geographies, meaning that market entry and expansion decisions will need to account for local feedstock availability, logistics, and downstream pricing power.
These trends translate into tangible commercial opportunities. For producers, the opportunity lies in converting technological capability into recognized application fit, particularly in furniture and interior construction, where surface and emission attributes can support value-based positioning. For investors, the opportunity is to distinguish between capacity that is aimed at commodity substitution and capacity that is designed to serve premium fine surface demand with defensible technical and supply chain advantages. For procurement and specification teams, the opportunity is to use FOSB selectively where it reduces downstream processing cost, improves finished-product quality, or enables design choices that are harder to achieve with traditional boards.
Potential risks and uncertainties should not be overlooked. Substitution pressure from MDF, particleboard, and improved OSB grades remains real, particularly where FOSB does not offer a sufficiently compelling cost or performance advantage. Feedstock and adhesive cost volatility can compress margins if not managed proactively. In addition, regulatory expectations may continue to rise, shifting the baseline for what qualifies as acceptable performance and increasing the cost of non-compliance. These factors suggest that confidence in long-term FOSB growth should be paired with disciplined application targeting and cost control.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to define FOSB as a distinct product platform rather than a generic panel. This means aligning technology investment, feedstock strategy, and adhesive selection with specific end-use requirements, and building qualification and specification support that helps buyers understand where FOSB adds value. Producers that can demonstrate consistent surface quality, predictable emission performance, and reliable supply are better positioned to secure long-term relationships in furniture and interior construction segments.
For investors, due diligence should focus on the fit between capacity strategy and application reality. The most attractive opportunities are likely to be found where new lines are tied to clear downstream demand, supported by appropriate press and surface technology, and managed with cost structures that can withstand input volatility. Broader OSB capacity expansions should be evaluated separately from dedicated FOSB projects, since the commercial logic and risk profile differ meaningfully.
For procurement and specification teams, the practical path is to evaluate FOSB on a segment-by-segment basis, comparing total installed cost, finish compatibility, machining behavior, and compliance attributes against entrenched alternatives. Where FOSB offers a genuine combination of surface quality, structural performance, and supply reliability, it can be a constructive option; where it does not, traditional boards may remain the better choice.
For stakeholders seeking a deeper, segment-level view of market size, regional dynamics, and company-level positioning, the full PW Consulting report provides structured detail and customized interpretation to support internal planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Fine Surface Oriented Strand Board (FOSB) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


