



Printing Plate Market 2026: Packaging Demand Drives 2.82% CAGR Beyond Forecasts

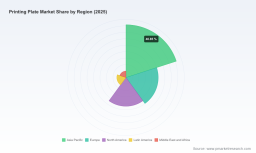
The Worldwide Printing Plate Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The global printing plate market has navigated a period of recalibration, evolving from a stable growth trajectory into a landscape defined by structural shifts and margin pressures. With a compound annual growth rate of 2.82% projected through 2032, the sector is not experiencing explosive expansion but rather a mature, value-driven evolution. Revenue figures have demonstrated resilience, climbing from approximately $4.15 billion in 2020 to a base-year valuation of $4.78 billion in 2025. This trajectory reflects an industry that has absorbed significant external shocks while maintaining its foundational role in global printing infrastructure. However, the path forward is anything but linear, and stakeholders must look beyond headline metrics to understand the underlying dynamics.
One of the most pressing challenges confronting the industry is the volatility in raw material costs, particularly aluminum. The primary substrate for conventional offset and lithographic printing plates has seen sustained price escalation, with the US Producer Price Index for aluminum sheet, plate, and foil manufacturing reaching 221.71 in early 2025, marking a year-over-year increase of over twelve percent. This cost pressure is not isolated; it directly translates into pricing power struggles across the value chain. Suppliers are forced to pass through increases, while converters and end-users resist, creating a tense negotiation environment that compresses margins and demands operational agility. Companies that rely heavily on traditional aluminum-based plates are finding that input cost management is no longer a back-office function but a strategic imperative.
A second critical challenge lies in the regulatory environment, which is rapidly reshaping responsibility and cost allocation. As of 2025, multiple US states have enacted Extended Producer Responsibility laws that explicitly cover packaging materials and printed paper. These regulations shift the financial and operational burden of end-of-life management from municipal systems to producers, compelling them to account for the environmental footprint of their packaging choices. This regulatory wave is not merely a compliance exercise; it fundamentally alters the value proposition of packaging materials and the printing plates that enable them. Manufacturers must now consider how plate technology influences substrate recyclability, waste generation, and the overall sustainability narrative that downstream brands are increasingly required to communicate.
Digital Offset Printing Plate Market
Market concentration further complicates the landscape. The sector is characterized by a moderately consolidated structure, where a relatively small group of dominant players captures a substantial share of revenue. This concentration provides scale advantages in R&D and global distribution but can also create barriers for niche innovators and regional players. The interplay between entrenched incumbents and agile specialists creates a dynamic where differentiation is increasingly tied to technological specificity rather than broad market presence. Understanding this concentration dynamic is essential for assessing competitive threats and partnership opportunities.
The industry stands at a crossroads where cost pressures, regulatory mandates, and concentration dynamics intersect. Navigating this environment requires more than incremental adjustments; it demands a clear-eyed assessment of which structural forces are temporary and which represent permanent shifts in how printing plates are sourced, produced, and valued.
Key Drivers of Market Evolution
Technological innovation continues to serve as the primary engine of differentiation in the printing plate market, with sustainability and process efficiency converging into a single strategic priority. Developments such as process-free and pre-heat-free offset plates, alongside chem-free technologies, reflect a broader industry push to reduce chemical consumption, lower energy requirements, and simplify plate processing workflows. These innovations are not merely incremental improvements; they address operational pain points that directly impact total cost of ownership for print service providers. By eliminating or reducing wet processing steps, manufacturers are enabling faster turnaround times, lower water usage, and reduced hazardous waste handling, all of which resonate with both economic and environmental objectives. The integration of renewable raw materials into polymer layers, with some recent flexographic plate series incorporating upwards of nineteen to twenty-nine percent bio-based content, further illustrates how material science is being leveraged to meet sustainability targets without sacrificing print quality or run length performance.
Policy and regulatory frameworks are acting as powerful accelerants for technology adoption and supply chain reconfiguration. Extended Producer Responsibility laws, now active in multiple jurisdictions, are forcing a reevaluation of packaging lifecycles and the role of printing substrates within them. For plate manufacturers, this regulatory shift has two implications. First, it creates demand for plates that enable cleaner, more recyclable packaging outputs, particularly in flexographic and offset applications where ink adhesion, substrate compatibility, and waste reduction are critical. Second, it introduces compliance complexity that rewards companies with strong regulatory intelligence and the ability to provide documented sustainability credentials. The requirement for producers to register with designated responsibility organizations and report on material flows means that transparency and traceability are becoming competitive differentiators, not just operational niceties.
Demand-side behavior is undergoing a parallel transformation, driven by shifts in consumer preferences and enterprise procurement strategies. The continued global expansion of e-commerce and the premium placed on high-quality flexible packaging have reinforced demand for flexographic plates optimized for corrugated and film-based substrates. At the same time, commercial printers are increasingly consolidating their plate sourcing around suppliers that offer predictable performance, shorter makeready times, and consistent color fidelity. This behavior is pushing the market toward solutions that reduce variability and improve throughput, particularly in high-volume packaging runs where downtime and waste carry significant financial consequences. Brands are also becoming more vocal about the environmental attributes of their packaging, which cascades pressure down to converters and plate suppliers to demonstrate measurable sustainability gains.
Supply chain and cost structure dynamics are reshaping competitive positioning in ways that extend beyond raw material pricing. The sustained elevation of aluminum costs has forced a reevaluation of substrate alternatives, processing efficiencies, and pricing architectures. Suppliers that can decouple performance from pure aluminum dependence, whether through hybrid material designs, thinner gauge plates, or alternative substrate chemistries, gain a structural advantage. Simultaneously, the integration of digital workflow tools that optimize plate imposition, reduce waste, and improve press readiness is becoming a critical component of value delivery. The ability to offer end-to-end efficiency, rather than a commodity plate, is increasingly what separates long-term partners from transactional vendors. These drivers collectively point toward a market where value is created not through volume alone but through technological specificity, regulatory alignment, and total cost optimization.
Competitive Landscape and Leading Strategies
The competitive field in the printing plate market is defined by a mix of global specialists, diversified material science players, and focused regional manufacturers, each pursuing distinct strategic positioning. Fujifilm Holdings Corporation has built a reputation around thermal and violet CTP plates, including process-free and Brillia series offerings, which aligns with the market's push toward reduced chemical use and workflow simplification. Agfa-Gevaert, operating through its ECO3 brand, has emphasized chem-free and pre-heat-free offset technologies such as the Azura and Energy Elite series, targeting both commercial and packaging segments with a clear sustainability narrative. These players illustrate a common strategy among leading incumbents: leverage process innovation to reduce total operating costs for customers while building a defensible sustainability proposition.
Flexographic plate specialists occupy a different competitive tier, driven by the structural growth of flexible packaging and labeling. Flint Group, with its Nyloflex portfolio and consumables focus, competes on depth of application expertise in flexible packaging and labels. DuPont, MacDermid Graphics Solutions, and Miraclon, through its FLEXCEL technology, each pursue differentiated photopolymer and flexographic solutions optimized for specific substrate performance and impression requirements. Asahi Photoproducts has carved out a position with water-washable flexographic plates that address environmental processing concerns, while Toray and Toyobo focus on high-run flexographic plates and photopolymer solutions tailored to packaging durability and consistency. XSYS rounds out this competitive group with Nyloflex and Nyloprint offerings that serve both flexographic and letterpress applications in packaging. These companies share a common strategic thread: deep application specificity, close collaboration with converters and brand owners, and continuous iteration on polymer formulations and plate handling characteristics.
Several other players bring distinct advantages to the competitive mix. Eastman Kodak Company continues to leverage process-free thermal photopolymer plates for offset and packaging, drawing on established brand recognition and technology heritage. Heidelberger Druckmaschinen AG provides offset plates and integrated systems that align with sheetfed and packaging production workflows. PlateCrafters and Container Graphics Corporation represent a more specialized tier, manufacturing custom flexographic photopolymer plates for corrugated and packaging applications, often competing on responsiveness, customization, and niche substrate expertise. The presence of these focused manufacturers highlights a market where segmentation is not just about plate type but about application tuning, regional service density, and the ability to address specific substrate challenges.
Recent market developments provide concrete evidence of how these competitive dynamics are playing out. In February 2026, ECO3 announced a double-digit global price increase for offset printing plates, citing continued rises in aluminum costs and aluminum-related treatments, with the adjustment taking effect in March 2026. This move underscores the pricing pressure that raw material volatility places on suppliers and signals that cost pass-through is becoming a more frequent competitive lever. Conversely, in May 2025, XSYS launched the Nyloflex Eco Flexo Plate Series, incorporating a notable share of renewable raw materials in the polymer layer while reducing processing time for packaging applications. This launch illustrates how competitors are using material innovation and process efficiency to differentiate beyond price, targeting customers who value sustainability credentials and workflow improvements in equal measure.
The market structure is evolving along two parallel tracks. On one hand, consolidation pressures remain, as larger players with global distribution, integrated R&D, and diversified product portfolios are well-positioned to capture share from smaller, less-resourced competitors. On the other hand, fragmentation persists in application-specific niches, where specialized plate formulations, regional service capabilities, and custom product development create opportunities for focused players to thrive. New entrants or expanders that bring meaningful technological differentiation, strong sustainability credentials, or superior cost structures can disrupt established relationships, particularly in packaging segments where brand owner mandates are reshaping converter preferences. The net effect is a landscape where competitive advantage is increasingly tied to the ability to combine material innovation, regulatory responsiveness, and total cost optimization rather than scale alone.
Future Trends and Commercial Implications
Looking toward the 2026 to 2032 horizon, three interconnected trends are likely to shape the direction of the printing plate market. First, sustainability-driven material innovation will move from a differentiator to a baseline expectation, particularly in packaging applications. Plates that incorporate renewable content, reduce processing chemical requirements, or enable lower-waste press runs will increasingly be evaluated alongside traditional performance metrics. This trend creates commercial opportunity for suppliers that can document measurable environmental benefits without compromising print quality, run length, or press compatibility. It also raises the bar for competitors that continue to rely on conventional material architectures, as regulatory mandates and brand owner procurement criteria tighten.
Second, pricing dynamics and cost structure adaptation will remain central to competitive strategy. With aluminum costs elevated and regulatory requirements adding new layers of operational expense, the ability to manage input costs, optimize plate thickness, and deliver workflow efficiencies will differentiate financially resilient players from those squeezed by margin compression. Companies that invest in substrate alternatives, process simplifications, and digital workflow integration are positioned to offer more predictable total cost profiles, which is increasingly valuable to converters operating under tight margins and volatile input markets. The trend suggests a market where pricing power will belong to those who can articulate and deliver tangible cost advantages across the full production lifecycle.
Third, regulatory expansion and producer responsibility frameworks will continue to reshape procurement behavior and product specifications. As more jurisdictions implement Extended Producer Responsibility requirements and packaging waste targets, the printing plate market will feel indirect but meaningful pressure to align with downstream sustainability goals. This creates opportunities for suppliers that can provide compliance-supporting documentation, lifecycle transparency, and plate technologies that facilitate recyclability or waste reduction. However, it also introduces risk for players that lack regulatory visibility or whose product portfolios are heavily tied to substrates and processes that may face future restrictions or cost penalties.
These trends converge on a clear commercial implication: value will migrate toward solutions that combine performance, sustainability, and cost predictability. Suppliers and investors who anticipate these shifts and align their portfolios accordingly will be better positioned to capture growth in packaging and commercial segments where these factors are becoming decisive. The primary uncertainty lies in the pace and geographic scope of regulatory adoption, as well as the extent to which raw material costs stabilize or continue their upward trajectory. Both variables will influence the speed at which sustainability and cost innovations translate into market share gains.
Actionable Recommendations for Decision-Makers
For plate manufacturers and technology suppliers, the priority is to accelerate investment in process-efficient and material-innovative plate solutions that directly address sustainability mandates and cost pressures. Differentiation should focus on measurable reductions in chemical use, processing time, and waste, paired with clear documentation that supports customer compliance and brand owner sustainability claims. Strategic partnerships with converters and packaging producers can provide early feedback loops and co-development opportunities that lock in preference before procurement criteria harden.
For investors evaluating exposure to this market, the opportunity lies in companies that demonstrate a credible path to total cost leadership and regulatory alignment, rather than those competing solely on scale or legacy product breadth. Attention should be paid to players with strong flexographic and packaging specialization, as these segments are benefiting from structural demand growth and brand owner sustainability mandates. Monitoring raw material cost trajectories, regional regulatory expansion, and M&A activity among mid-tier specialists will provide early signals of shifting competitive dynamics and valuation opportunities.
For procurement leaders and print service providers, the strategic imperative is to evaluate plate suppliers based on total cost of ownership, process reliability, and sustainability support, rather than unit price alone. Engaging suppliers early in packaging design and workflow planning can unlock makeready efficiencies, reduce waste, and improve press consistency, all of which contribute to margin protection in a cost-volatile environment. Building supplier relationships that include regulatory intelligence and sustainability documentation will also reduce compliance risk and strengthen brand owner confidence.
Flexographic Printing Plate Market
As the market evolves, the leaders who capture disproportionate value will be those with access to granular segmentation data, company-level competitive benchmarks, and forward-looking scenario analysis that ties regulatory, cost, and technology trajectories to specific commercial outcomes. A detailed research report can provide the segmentation-level revenue breakdowns, regional demand patterns, product-level performance comparisons, and customized strategic recommendations needed to translate these macro trends into precise action plans. Access to this level of depth enables decision-makers to move from general awareness to targeted portfolio adjustments, pricing strategies, and partnership decisions that directly impact competitiveness through 2032.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Printing Plate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


