



Textile Chemicals Market 2026: Beyond the 4.8% CAGR and Asia Pacific’s $15.4B Pull

The Textile Chemicals Market: Strategic Shifts and Commercial Opportunities Through 2032
The textile chemicals sector has entered a phase of structural recalibration. After a decade of steady volume growth underpinned by expanding apparel production and industrial fabric consumption, the market is now being reshaped by tighter environmental mandates, evolving consumer expectations, and technological breakthroughs that are redefining how fibers are treated, dyed, and finished. For executives, investors, and procurement leaders, the central question is no longer whether demand will grow, but where value will concentrate and which capabilities will separate winners from laggards in the coming years.
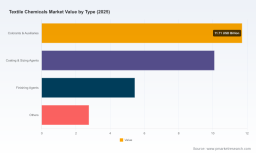
The global market for textile chemicals has reached a valuation of approximately 30 billion USD in 2025, representing a measured acceleration from roughly 21.5 billion USD in 2020. Over the 2020 to 2025 period, revenue expanded at a compound trajectory that reflects both post-pandemic recovery and the steady integration of chemical solutions across garment, home textile, and technical fabric supply chains. Looking ahead to 2032, the market is projected to surpass 41 billion USD, driven by a compound annual growth rate averaging 4.8 percent. While this growth rate signals resilience, it also indicates that the era of unconstrained volume expansion is giving way to a more selective, regulation-aware, and performance-driven landscape. Value creation will increasingly depend on how effectively companies navigate compliance complexity, capture premium segments, and align product portfolios with sustainability and circularity mandates.
Market Reality and Critical Inflection Points
The headline growth figures mask underlying tensions that are already reshaping competitive dynamics. Three interlocking challenges define the current inflection point for the sector.
First, regulatory intensity is shifting from voluntary best practices to enforceable, auditable standards. Chemical input approval criteria, substance restriction lists, and wastewater discharge targets are no longer confined to niche certifications. They are cascading through procurement contracts, brand compliance programs, and regional market access requirements. Companies that treat compliance as a retrospective documentation exercise are finding themselves locked out of premium accounts or forced into costly reformulation cycles. The regulatory wave is compressing margins for undifferentiated products while rewarding firms that have built formulation transparency and substitution capability into their R&D workflows.
Second, the cost and availability of conventional chemical building blocks remain structurally uncertain. Feedstock volatility, energy price swings, and shifting trade flows have disrupted the predictability that many formulators relied on for cost planning. At the same time, the transition toward lower-impact and bio-based alternatives introduces new input economics that can be higher in the short term. The practical consequence is that pricing strategies based solely on historical material costs are increasingly brittle. Businesses that succeed are those that combine multi-source sourcing, formulation flexibility, and service-level agreements that share risk more intelligently across the value chain.
Textile Dyes Market
Third, customer expectations are bifurcating the market. Mass-market segments continue to pressure suppliers for cost efficiency and reliable delivery, while premium and performance-oriented segments demand demonstrable environmental attributes, functional performance in demanding applications, and traceability. This polarization makes portfolio strategy decisive. Suppliers that attempt to serve all segments with a uniform offering risk being commoditized in the low end while failing to capture the margin in the high end. Those that can clearly segment their value proposition, back claims with verified data, and align service models accordingly are better positioned to defend pricing and deepen customer relationships.
Key Drivers Reshaping the Landscape
Understanding where growth and margin will concentrate requires looking past top-line volume to the forces that are changing how textile chemicals are developed, approved, and deployed.
Technological innovation and formulation breakthroughs. Advances in low-temperature dyeing, enzyme-assisted pretreatment, waterless or reduced-water finishing, and digital color matching are steadily reducing resource intensity while improving reproducibility. Digital tools are also enabling faster formula optimization and more precise dosing, which directly lowers wastewater load and chemical waste. These innovations matter commercially because they translate environmental performance into operational savings that customers can verify. Suppliers that embed these capabilities into ready-to-adopt process packages, rather than offering only raw ingredients, are building stickier relationships and gaining pricing power.
Policy and regulatory environment. The regulatory framework is tightening across multiple jurisdictions, with substance restrictions, organic textile chemical criteria, and endocrine disruptor limits all moving toward stricter thresholds and broader coverage. Recent updates to major standards have introduced lower limits for certain substances, expanded the list of regulated compounds, and added mandatory due diligence expectations for chemicals used in organic fiber production. In parallel, regional legislation targeting specific chemical families in textiles, clothing, footwear, and waterproofing agents has moved into force or toward implementation, with exemptions limited to specific recycled or industrial use cases. For suppliers, the strategic implication is clear: product stewardship is now a market-access requirement. Formulation roadmaps must anticipate substitution needs, documentation must meet audit expectations, and technical support must help customers navigate compliance without disrupting production.
Demand-side behavior. Brands and manufacturers are increasingly tying procurement decisions to measurable sustainability outcomes and risk reduction. Consumer-facing claims are being scrutinized more closely, which pushes upstream suppliers to provide credible, standardized evidence rather than marketing narratives. At the same time, the rise of technical textiles and high-performance applications is expanding demand for chemicals that deliver specific functionalities such as durability, moisture management, antimicrobial action, or flame resistance, often with tighter environmental profiles. This dual pressure rewards suppliers that can combine performance with verifiable attributes and that can support customers in meeting both internal targets and external claims.
Supply chain and cost structure realignment. Geographic concentration of production, logistics bottlenecks, and evolving trade dynamics have encouraged buyers to diversify sources and favor suppliers with regional presence or strong distribution networks. Distributors and integrated suppliers that can guarantee continuity, offer technical troubleshooting, and consolidate multiple chemical needs into a single interface are gaining importance, particularly for smaller and mid-sized processors. The cost structure is also being reshaped by the premium attached to compliant, lower-impact chemistries and by the operational savings that come from more efficient application processes. Businesses that can articulate total cost of ownership rather than unit price are better equipped to navigate these shifts.
The Competitive Field: Positioning, Differentiation, and Evolution
The market remains moderately concentrated, with the largest players holding a meaningful share of total revenue while significant space remains for specialized and regional players. This structure favors a dual strategy: scale players compete on broad portfolios, global reach, and technical service infrastructure, while specialists compete on deep application knowledge, niche performance attributes, and agility in formulation.
Fine Chemicals Market
Archroma occupies a prominent position as a global provider of sustainable dyes, colorants, and performance chemicals tailored to dyeing, finishing, and printing applications. Its differentiation rests on a strong sustainability narrative backed by product development focused on reduced environmental impact and process efficiency, combined with the ability to serve large, multi-site customers with consistent standards.
Huntsman Textile Effects, with operations spanning Switzerland and Germany, focuses on functional dyes, finishing chemicals, and performance solutions. Its strength lies in blending application expertise with high-performance outcomes, allowing it to address demanding end-use requirements while supporting customers in meeting quality and compliance expectations.
CHT Group, based in Germany, specializes in textile chemicals, auxiliaries, and dyeing solutions for printing, finishing, and processing. Its positioning emphasizes depth in application know-how and a focused specialty portfolio, which enables close collaboration with processors seeking tailored solutions rather than broad commodity offerings.
Azelis operates as a distributor and integrated supplier across dyes, bleaching agents, pretreatment chemicals, and finishing solutions. Its competitive advantage comes from network reach, inventory continuity, and the ability to bundle technical support with supply reliability, an increasingly valuable proposition for customers managing complex compliance and sourcing requirements.
On the Asia-centric side, NICCA Chemical stands as Japan's leading developer and manufacturer of scouring, dyeing, and finishing chemicals, leveraging strong process expertise and a reputation for quality and reliability. Sarex Chemicals and Fineotex Chemical, both based in India, contribute specialist coverage across auxiliaries, pretreatment, dyeing, printing, and finishing. Their relevance lies in serving full value-chain needs with regional cost structures, local technical presence, and the ability to support high-volume production environments that demand consistent availability and practical process support.
The competitive landscape is evolving along three trajectories. Consolidation continues to favor larger players that can integrate R&D, compliance documentation, and global service delivery, particularly as customers seek fewer, more accountable partners. At the same time, fragmentation remains viable for specialists that can dominate specific application niches, offer differentiated performance, or provide rapid regional responsiveness. A third dynamic is the growing role of events and platforms that concentrate the industry's attention on chemicals and dyes. The launch of a dedicated Textile Chemicals and Dyes product segment at a major international trade fair, featuring more than 30 exhibitors across dyes, auxiliaries, functional finishes, and polymer technologies, signals that chemical solutions are being elevated from supporting inputs to strategic showcase categories. Early booking windows and confirmed participation from established players further indicate that the segment is becoming a focal point for partnership formation, product launches, and market signaling. Regional expos centered on textile chemicals and auxiliaries continue to reinforce the importance of Asia as both a manufacturing base and a sourcing hub, where proximity, cost, and technical support intersect.
Forward Outlook: Three Trends Shaping 2026 to 2032
The combination of regulation, technology, and demand evolution points to a set of trends that will define commercial opportunities over the next several years.
Compliance-driven reformulation will become a recurring revenue stream rather than a one-time project. As substance restrictions tighten, due diligence expectations expand, and wastewater guidelines grow more prescriptive, processors will need ongoing support to maintain market access. This creates sustained demand for alternative chemistries, testing support, documentation services, and process adjustments. The commercial opportunity lies not only in new molecules but in service architectures that help customers stay ahead of change. Suppliers that anticipate regulatory trajectories and pre-develop substitute portfolios will capture switching demand before competitors react. The risk is that compliance becomes a reactive cost center if firms lack foresight, leading to rushed substitutions, production disruptions, and eroded trust.
Performance and sustainability will increasingly converge in premium segments. Functional finishes, durable properties, and reduced-impact processing are moving from separate considerations to combined requirements. Customers want chemicals that deliver specific end-use performance without undermining environmental targets, and they expect evidence that can satisfy both internal procurement criteria and external claims. This convergence favors suppliers that can bundle functional chemistry with application engineering and verified attribute data. The upside is margin expansion in segments where differentiation is defensible. The uncertainty is that verification standards and claim scrutiny will continue to rise, which raises the bar for substantiation and can slow adoption if proof points are weak.
Regional service models and distribution strength will matter as much as product formulations. As procurement teams diversify sourcing and tighten continuity requirements, the ability to deliver reliably, troubleshoot locally, and consolidate multiple needs into a coherent package becomes a differentiator. Distributors and integrated suppliers with strong regional footprints can reduce risk for processors that cannot manage complex multi-supplier relationships across borders. This trend supports growth for players that invest in local technical presence, inventory resilience, and responsive service. The downside is that building and maintaining such networks requires capital and operational discipline, and players that over-extend geographically without adequate support infrastructure may struggle to convert reach into profitable relationships.
Strategic Imperatives for Decision-Makers
The choices made over the next twelve to twenty-four months will shape competitiveness through the end of the decade. The following actions are most relevant across the main stakeholder groups.
PW Consulting Information & Electronics Research Center
For manufacturers and formulators. Build a reformulation pipeline that maps current product portfolios against anticipated regulatory thresholds and customer sustainability expectations. Prioritize formulations that lower water, energy, and waste intensity while maintaining or improving performance, because these solutions convert environmental goals into operational savings that customers can measure. Strengthen documentation, testing, and traceability so that claims can withstand audit scrutiny. Segment the portfolio clearly between cost-competitive essentials and premium performance or sustainability-led offerings, and align sales and technical service teams accordingly so that each segment is supported with the right value narrative and service model.
For investors. Favor business models with defensible differentiation: proprietary formulations paired with verified attributes, strong compliance capability, and regional service reach. Assess exposure to regulatory risk by examining how dependent revenue is on substances likely to face tighter limits, and evaluate whether the company has substitution roadmaps and credible alternatives. Look for evidence that environmental performance is being integrated into product design rather than treated as a separate initiative, since this integration increasingly determines access to premium accounts. Monitor distribution partnerships and technical service capacity, because continuity and support can be the deciding factor in procurement decisions for processors facing compliance and sourcing complexity.
For procurement and buying organizations. Treat chemical selection as a risk-management and total-cost decision rather than a unit-price exercise. Evaluate suppliers on formulation transparency, compliance readiness, substitution capability, and the ability to support process efficiency improvements that reduce resource use and waste. Encourage multi-year collaboration with key suppliers so that reformulation, testing, and documentation can be planned in advance rather than triggered by emergency compliance events. Prioritize suppliers that can provide standardized evidence packages aligned with the certifications and standards relevant to your markets, because this reduces downstream verification friction and strengthens your own claims.
Timely, granular intelligence is essential for executing these actions with precision. Market-level growth rates and segment sizes provide useful context, but the decisions that determine competitive advantage depend on how specific regulations will affect product lines, where substitution demand is emerging earliest, which applications are capturing premium margins, and how distribution and service models are shifting in key regions. A complete research report offers the detailed segmentation, company benchmarking, regulatory mapping, and scenario-based forecasts needed to translate these dynamics into concrete plans. It also provides the granular data and customized recommendations that allow decision-makers to prioritize initiatives, assess risk exposure, and identify the most actionable opportunities for their specific portfolio and geography.
For detailed analysis of this topic, please visit the official page: Textile Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


