



Polymer Capacitor Market at 8.2% CAGR: What 2032 Growth and Consumer Electronics Demand Really Signal

The Polymer Capacitor Market: Strategic Trends and Commercial Opportunities Through 2032
The global polymer capacitor market stands at a pivotal inflection point. From 2020 to 2025, total market revenue expanded from approximately 163.15 million to 215.0 million, reflecting steady growth across multiple end-use sectors. Looking ahead, the trajectory accelerates, with the market projected to reach 344.8 million by 2032, delivering a compound annual growth rate of 8.2 percent over the 2026 to 2032 forecast period. These numbers signal more than incremental expansion; they reflect a structural shift in how electronics manufacturers, automotive system designers, and industrial equipment engineers approach power management and signal integrity.
Beneath the headline figures lies a fragmented yet increasingly strategic competitive arena. The top three players collectively account for 24.6 percent of market revenue, while the top five capture 26.2 percent. This moderate concentration suggests room for differentiation, regional specialization, and technology-led positioning rather than pure scale dominance. For executives and investors evaluating the space, the question is no longer whether polymer capacitors will grow, but which sub-segments, applications, and supply chain strategies will capture disproportionate value as the market matures.
Market Dynamics and Structural Challenges
The polymer capacitor sector operates within a broader passive component ecosystem that is simultaneously experiencing demand surges, material constraints, and tightening qualification standards. Three interconnected challenges define the current landscape and will shape competitive outcomes over the next several years.
Balancing Miniaturization With Reliability Expectations
Design engineers across consumer electronics, automotive, and industrial applications continue pushing for smaller form factors while demanding higher ripple current tolerance, lower ESR, and extended operational lifespans. Polymer capacitors inherently address many of these requirements through conductive polymer electrolyte technology, but the pressure to reduce profile dimensions without compromising thermal stability or moisture resistance creates genuine engineering tension. Manufacturers that can deliver low-profile solutions while maintaining certification-ready performance metrics gain a clear advantage in qualification cycles and design-in opportunities.
PW Consulting Information & Electronics Research Center
Material Cost Volatility and Pricing Pressures
Cost structures across the passive component supply chain have faced sustained upward pressure, particularly in tantalum-based polymer lines. Industry pricing adjustments took effect in mid-2024 as manufacturers cited rising material input costs, and those dynamics have persisted into subsequent quarters. For product planners and procurement teams, this translates into longer hedging windows, tighter inventory buffers, and increased sensitivity to raw material availability. Suppliers with vertically integrated material strategies or diversified polymer formulations are better positioned to manage margin erosion while maintaining competitive pricing.
Qualification Rigor and Customer-Specific Validation Cycles
Automotive and high-reliability industrial applications now require stricter validation protocols. Compliance with AEC-Q200 qualification remains a baseline expectation for automotive polymer capacitors, ensuring consistent performance in electric vehicle power systems and related subsystems. Beyond automotive, industrial-grade polymer products increasingly face moisture-resistance benchmarking at elevated temperature and humidity conditions over extended durations. These qualification thresholds extend time-to-market for new part numbers and raise the barrier for generic commodity players. Companies that invest early in robust qualification dossiers and maintain transparent reliability data shorten customer design cycles and strengthen long-term supply agreements.
Supply chain timing further complicates planning. Across all capacitor technologies, average lead times have hovered around 19 weeks as of late 2025, reinforcing the importance of stable production scheduling and proactive capacity alignment. For buyers, this means demand forecasting and supplier diversification are no longer optional procurement best practices; they are operational necessities.
Core Drivers Shaping Market Trajectory
Several overlapping forces explain why polymer capacitors are capturing growing share across multiple end markets. Understanding these drivers helps decision-makers distinguish structural growth from cyclical demand swings.
Technology Innovation and Form-Factor Engineering
The most visible product-level evolution centers on profile reduction, thermal endurance, and ripple current performance. Recent commercial introductions illustrate how manufacturers are aligning advanced materials with application-specific constraints. In late 2025, Panasonic Industry began commercial production of conductive polymer tantalum solid capacitors with an industry-leading 3 mm profile, targeting USB Type-C power delivery architectures where space and current handling are equally critical. Around the same period, Taiyo Yuden commercialized hybrid aluminum electrolytic capacitor series engineered for higher rated ripple current and reduced profile, specifically addressing automotive ADAS and power steering applications. These launches reflect a broader pattern: manufacturers are not simply scaling existing designs, they are engineering product families around real-world system constraints such as board space, thermal environment, and power delivery topology.
Nichicon’s recent activity reinforces this trend from a thermal-reliability angle. The company introduced a highly heat-resistant conductive polymer hybrid aluminum electrolytic series capable of sustaining 4000 hours at 135°C, alongside automotive-rated hybrid capacitor series distributed across EMEA channels. High-temperature endurance directly supports automotive under-hood and near-power-electronics placements, where long-term degradation profiles determine component selection. Similarly, Nichicon’s broader portfolio emphasis on conductive polymer hybrid aluminum electrolytic and solid capacitors with elevated temperature ratings signals a strategy centered on reliability differentiation rather than cost-only competition.
Application-Side Demand Transformation
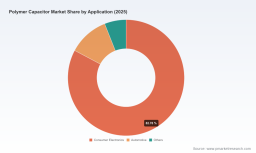
Consumer electronics remain the largest application anchor for polymer capacitors, driven by compact power systems, wireless charging, high-density motherboard designs, and ever-increasing power conversion requirements in portable devices. However, the most strategically significant demand shift is occurring in automotive electrification and advanced driver-assistance architectures. As vehicle power systems become more complex and electronics content per platform rises, polymer capacitors are increasingly integrated into DC-DC conversion stages, noise filtering networks, and decoupling arrangements that must tolerate fluctuating thermal and vibration environments.
Industrial automation, renewable energy inverters, and high-reliability infrastructure equipment also contribute to demand diversification. These sectors prioritize long service life, stability under continuous load, and qualification documentation over lowest-unit-cost sourcing. The result is a demand landscape that rewards suppliers capable of matching application-specific performance profiles, not merely volume capacity.
Regulatory, Qualification, and Standardization Pressure
Qualification frameworks and environmental reliability benchmarks increasingly shape purchasing decisions. AEC-Q200 continues to serve as the foundational reliability standard for automotive-grade polymer capacitors, while industrial product expectations have evolved toward stricter moisture and thermal endurance testing. These standards create a two-tier market dynamic: commodity-grade applications tolerate broader performance variance, while automotive and industrial buyers reward proven qualification records and traceable reliability data.
Standardization also influences supply chain behavior. When qualification requirements become more uniform across tier customers, manufacturers with established validation infrastructure gain efficiencies in documentation, testing throughput, and customer onboarding. Those without dedicated qualification capabilities face longer approval timelines and higher rejection risk, particularly in safety-related or mission-critical subsystems.
Supply Chain Resilience and Material Strategy
Recent pricing actions across tantalum-based polymer capacitors underscore the importance of material resilience. Rising input costs have prompted manufacturers to reassess sourcing strategies, formulation alternatives, and inventory positioning. At the same time, lead time elongation across capacitor technologies has reinforced the value of multi-source arrangements and forecast-aligned production planning.
For incumbent suppliers, the response has included hybrid capacitor architectures that combine conductive polymer benefits with aluminum electrolytic structural familiarity, offering a balance of performance and manufacturability. For buyers, this environment emphasizes the need to evaluate not only unit price but also manufacturing continuity, qualification coverage, and the supplier’s ability to sustain availability through cost cycles.
Competitive Landscape and Strategic Positioning
The polymer capacitor market features a mix of established Japanese manufacturers, U.S.-based specialty players, European component specialists, and Taiwan-based producers with regional manufacturing advantages. Despite moderate top-tier concentration, competitive differentiation is increasingly driven by product architecture, application targeting, and qualification readiness rather than broad commoditization.
KYOCERA AVX Components Corporation has positioned itself around conductive polymer solid electrolytic capacitors with notable attention to automotive and high-reliability segments. Its portfolio includes TCO and TCQ automotive series, high-reliability hermetically sealed polymers, and COTS+ military-grade tantalum polymer lines. This mix suggests a strategy that leans into reliability-grade differentiation and application-specific series development rather than volume-only competition.
Panasonic Industry Co., Ltd. maintains a broad polymer capacitor portfolio spanning conductive polymer aluminum electrolytic, tantalum solid, aluminum solid, and hybrid aluminum electrolytic capacitors. Its recent product activity emphasizes profile reduction for power delivery applications, aligning with consumer and computing trends that prize compact form factors without sacrificing current-handling capability.
Murata Manufacturing Co., Ltd. continues to leverage its broader passive component ecosystem, offering conductive polymer aluminum electrolytic and solid capacitors for automotive, industrial, and high-reliability applications. The company’s positioning benefits from integration with adjacent component categories and a strong design-in support structure across multiple end markets.
Nippon Chemi-Con Corporation has expanded its polymer capacitor emphasis through high-voltage series, liquid immersion cooling-oriented series, and hybrid models. The inclusion of high-voltage and cooling-specific product lines indicates attention to power electronics and industrial applications where voltage stress and thermal management are key selection criteria.
Nichicon Corporation has pursued a reliability-led strategy, highlighting conductive polymer hybrid aluminum electrolytic and solid capacitors with high-temperature ratings. Its recent automotive-rated series and heat-resistant product introductions reinforce a focus on application-grade durability, particularly relevant for automotive and industrial environments with sustained thermal exposure.
Rubycon Corporation and Lelon Electronics Corp. provide conductive polymer aluminum electrolytic solutions for general and automotive use. Their market roles illustrate how regional and mid-tier manufacturers compete by combining cost-competitiveness with targeted application support, rather than attempting to match the broadest portfolio breadth of larger incumbents.
Vishay Intertechnology, Inc. extends its presence through polymer tantalum and aluminum solid electrolytic capacitors for industrial, automotive, and aerospace applications. Its positioning reflects the demands of sectors where qualification rigor, material traceability, and reliability documentation carry significant commercial weight.
Würth Elektronik GmbH & Co. KG competes with aluminum polymer electrolytic capacitors and radial series, aligning with the broader European component distribution and design ecosystem. ROHM Co., Ltd. rounds out the competitive field with polymer tantalum and aluminum solid electrolytic capacitors following integration of related business assets, indicating continued consolidation and portfolio rationalization across the sector.
Several competitive themes emerge from this landscape. First, differentiation is shifting from generic capacitance ranges toward application-optimized families with defined thermal, profile, and ripple current characteristics. Second, hybrid architectures are gaining prominence because they combine polymer-level ESR and ripple performance with structural and manufacturing familiarity. Third, the market is unlikely to consolidate rapidly into a single dominant structure; instead, it will likely evolve into a tiered ecosystem where automotive and high-reliability applications favor qualified incumbents, while consumer and general-purpose segments remain more price-sensitive and accessible to multiple suppliers.
Recent product introductions also suggest that regional channel strategies matter. Automotive-rated series launched across EMEA channels highlight the importance of localized qualification support, distribution partnerships, and application engineering availability. Suppliers that can demonstrate consistent technical support across geographies are better positioned to secure design wins in regions where automotive and industrial sourcing decisions are highly relationship and qualification driven.
Forward Outlook: Trends and Opportunities Through 2032
Extrapolating current growth dynamics, qualification momentum, and product innovation patterns points to several interrelated trends that will shape commercial opportunities over the next three to five years.
Trend 1: Application-Specific Polymer Capacitor Families Will Displace One-Size-Fits-All Sourcing
As system designers face tighter thermal envelopes, higher power densities, and more demanding reliability thresholds, generic capacitor specifications will become less persuasive. Buyers will increasingly evaluate parts against application-level benchmarks such as thermal endurance, ripple current capability, profile constraints, and qualification documentation. Suppliers that publish clear application 매핑 and maintain robust reliability data will capture more design-ins, particularly in automotive and industrial segments where failure cost is high.
Commercial opportunity: Companies that invest in application engineering, reference designs, and qualification-ready documentation can shorten customer evaluation cycles and build longer-term supply relationships. This creates a defensible position even in a moderately concentrated market.
Trend 2: Hybrid and Advanced Polymer Formulations Will Broaden Performance Windows
Hybrid aluminum electrolytic structures and advanced conductive polymer formulations will continue to expand the balance between ESR reduction, temperature stability, and manufacturability. These architectures are particularly relevant where designers need polymer-level electrical performance without abandoning aluminum-based mechanical or cost advantages. The ongoing appearance of hybrid-oriented product launches supports the view that this direction is not a niche experiment but a mainstream performance strategy.
Commercial opportunity: Product planners should monitor hybrid and advanced polymer lines as potential candidates for next-generation power delivery, noise filtering, and decoupling designs. Early engagement with suppliers offering these architectures can provide first-mover advantages in demanding applications.
Trend 3: Automotive Electrification and High-Reliability Industrial Demand Will Drive Sustained Volume Growth, With Qualification as the Gatekeeper
Conductive Polymer Aluminum Solid Capacitors Market
The 8.2 percent CAGR projected through 2032 reflects more than cyclical replacement demand; it reflects a structural increase in electronics content across vehicles, industrial equipment, and energy-related infrastructure. Automotive platforms in particular will continue placing higher capacitor content per vehicle as power management architectures grow more decentralized and more performance-critical. At the same time, qualification requirements will remain the commercial gatekeeper, meaning that volume growth will disproportionately flow to suppliers with credible reliability records and efficient validation processes.
Commercial opportunity: Suppliers that build automotive and industrial qualification capabilities early can secure longer design cycles and multi-program visibility. For buyers, prioritizing qualification readiness and supply continuity over short-term unit cost can reduce downstream risk in safety-related or mission-critical designs.
Vacuum Capacitor Market
Risk and Uncertainty Considerations
Several uncertainties could alter this trajectory. Material cost volatility may persist, affecting tantalum-based and other polymer lines unevenly. Lead time normalization is not guaranteed; supply disruptions, capacity constraints, or sudden demand shifts could reintroduce planning friction. Qualification expectations may continue to tighten, compressing timelines for new entrants and rewarding incumbents with established testing infrastructure. Finally, competitive overcapacity in certain commodity-grade segments could pressure pricing, even as qualified automotive and industrial segments remain more resilient. Decision-makers should therefore treat the polymer capacitor market as a portfolio of differentiated sub-segments rather than a single homogeneous opportunity.
Strategic Actions for Decision-Makers
Different stakeholders face distinct priorities in this environment. The following actions are designed to translate market dynamics into executable planning.
For Manufacturers and Component Suppliers
- Prioritize application-specific product families that address profile, thermal endurance, and ripple current requirements simultaneously rather than competing solely on capacitance range or unit cost.
- Strengthen qualification documentation and reliability data packages, especially for automotive and industrial customers where AEC-Q200 and extended environmental testing are baseline expectations.
- Evaluate hybrid and advanced polymer formulations as a way to expand performance differentiation while maintaining manufacturability and cost discipline.
- Align production planning and inventory strategy with current lead-time realities, and consider multi-source options where qualification and performance allow.
For Investors and Strategic Allocators
- Focus due diligence on suppliers with credible automotive and high-reliability qualification footprints, because those segments are likely to capture disproportionate value even in a moderately concentrated market.
- Assess exposure to material cost sensitivity and pricing actions across tantalum and aluminum polymer lines, and weigh vertical integration or formulation diversification as risk-mitigation indicators.
- Watch for portfolio consolidation and asset integration activity that may reshape competitive positioning, especially where adjacent business assets are combined to strengthen polymer capacitor capabilities.
For Procurement, Engineering, and Supply Chain Leaders
- Treat qualification status, thermal performance, profile constraints, and supply continuity as core evaluation criteria alongside price, particularly for automotive and industrial designs.
- Diversify approved sources where application requirements permit, while maintaining clear qualification thresholds to avoid fragmented validation burden.
- Engage suppliers early in the design phase to align on reliability testing, documentation, and lead-time expectations, reducing the risk of late-stage redesign or sourcing disruption.
The polymer capacitor market is expanding with clarity in direction but complexity in execution. Growth will continue toward 344.8 million by 2032, but the value capture will depend on how well companies align product engineering, qualification readiness, and supply resilience with the application needs that matter most. For organizations seeking deeper segmentation data, regional positioning detail, and tailored strategy recommendations, the full PW Consulting research report provides the granular breakdown and scenario analysis needed to convert these trends into actionable plans.
For detailed analysis of this topic, please visit the official page: Polymer Capacitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


