



Surgical Blades & Scalpels Market 2026: Why 5.2% CAGR and Disposable Blades Reshape Strategy

The Surgical Blades & Scalpels Market: Strategic Trends and Commercial Opportunities Through 2032
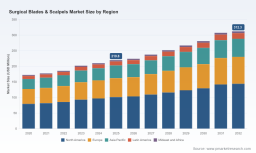
The global market for surgical blades and scalpels has entered a phase of steady, structurally supported expansion. Valued at approximately $172.5 million in 2020, the market reached $219.8 million in 2025 and is projected to climb to $312.3 million by 2032, reflecting a compound annual growth rate of 5.2 percent. This trajectory mirrors broader shifts in surgical practice, infection control standards, and procurement economics. While the product category itself is mature, the competitive and operational dynamics beneath the surface are evolving quickly. For executives, investors, and procurement leaders, the market presents a paradox: top-line growth is predictable, yet margin structures, channel control, and innovation pathways are being reshaped by regulation, safety mandates, and regional supply chain reconfiguration.
The market is heavily concentrated. The top three players account for roughly 60 percent of revenue, and the top five capture about 72 percent. This concentration signals scale advantages in manufacturing, sterilization, distribution, and compliance management. Yet the remaining share is fragmented across regional manufacturers, specialty blade producers, and safety-focused innovators, creating both pressure and opportunity depending on a company's positioning. The following analysis examines the core challenges, demand and supply drivers, competitive strategies, and forward-looking opportunities that will shape decision-making through the end of the decade.
Market Landscape and Core Challenges
A Mature Category Operating Under Structural Efficiency Pressure
The surgical blades and scalpels market is not experiencing explosive growth, but it is benefiting from persistent procedural volume expansion, a shift toward single-use sterile disposables, and tightening safety standards. The overall revenue path from 2020 through 2032 shows consistent year-over-year gains, with the steepest incremental increases expected in the latter half of the forecast period. This pattern is consistent with a category where volume growth, product mix shifts, and regional procurement changes compound rather than spike.
One of the most pressing challenges is the tension between cost containment and safety compliance. Hospitals and surgical centers are under sustained pressure to reduce indirect costs, yet regulatory and occupational safety expectations continue to favor single-use sterile blades and safety scalpels. The result is a procurement environment where price sensitivity exists alongside mandatory or strongly encouraged adoption of safety-engineered products. Manufacturers that can deliver standardized, compliant, and competitively priced disposable blades are better positioned than those relying on premium differentiation alone.
PW Consulting
A second challenge lies in the regulatory asymmetry across regions. In the United States, scalpel blades and scalpels are generally classified as Class I exempt devices, meaning most models do not require a premarket submission, but establishments must still register and list with the appropriate authorities. Manufacturing facilities are expected to meet ISO 13485 quality management expectations, and EU markets impose stricter single-use validation protocols under the Medical Device Regulation framework. This duality creates a compliance burden for companies selling across multiple jurisdictions, especially when validation documentation, sterilization records, and traceability requirements differ. The cost of maintaining multi-region compliance can erode margins for smaller producers while reinforcing the position of established players with mature quality systems.
A third challenge is the absence of dedicated reimbursement codes for blades and scalpels. Costs are typically embedded within global surgical procedure fees rather than billed as standalone items. This structure pushes procurement decisions toward total cost of procedure rather than device-level price comparisons, and it places a premium on reliability, inventory turnover, and integration with broader perioperative workflows. Suppliers that can demonstrate predictable availability, reduced sharps injury risk, and compatibility with existing surgical workflows gain leverage in a reimbursement environment that does not isolate blade economics.
Key Demand and Supply Drivers
Safety Standards and the Shift Toward Single-Use Sterile Disposables
A major driver of market evolution is the continued migration from reusable blades to single-use sterile disposables. This shift is reinforced by occupational safety mandates and international standards for safety scalpels, which aim to reduce sharps injuries among surgical staff. Facilities are increasingly standardizing on disposable sterile blades not only for clinical reasons but also to streamline infection control protocols and minimize reprocessing costs. The practical effect is a product mix that tilts toward disposable blades in many general surgery settings, while reusable blades retain relevance in specific use cases where reprocessing infrastructure and cost equations remain favorable.
Double Edges Blades Market
The commercial implication is clear: manufacturing capacity, sterilization capability, and distribution reliability for disposable blades are becoming strategic assets. Companies that can scale sterile disposable production while maintaining tight dimensional tolerances and consistent sharpness profiles are better positioned to capture share in a market where safety standards are accelerating adoption. At the same time, safety scalpel designs and retractable or shielded options are gaining attention in procurement specifications, giving an edge to suppliers with differentiated safety portfolios.
Regulatory Classification and Quality System Expectations
Regulatory classification shapes both entry barriers and operating economics. The Class I exempt status of most scalpel blades and scalpels in the United States lowers the premarket submission burden for many models, but it does not remove the need for establishment registration, listing, and robust quality management. ISO 13485 certification is effectively a baseline expectation for manufacturing facilities, and EU requirements add further validation rigor for single-use devices. These conditions favor manufacturers with mature quality infrastructure and disciplined documentation practices.
Worldwide Surgical Saw Blades Market
This environment also affects innovation incentives. Since many conventional blade models face a lighter regulatory pathway, competition often centers on manufacturing consistency, packaging, sterilization reliability, and supply continuity rather than dramatic product redefinition. By contrast, safety-engineered scalpels and specialty micro blades can involve more complex design validation, creating a higher barrier but also a stronger differentiation opportunity for companies that can demonstrate clinical and operational value.
Procurement Economics and the Embedded Cost Reality
Because blades and scalpels are generally absorbed into broader surgical procedure costs rather than reimbursed under dedicated codes, procurement decisions are influenced by total procedure economics. Surgical teams and purchasing departments evaluate availability, standardization, waste reduction, and injury prevention alongside unit price. This creates an environment where bundling compatibility, inventory management support, and safety alignment can be as important as the blade itself.
Demand-side behavior reflects this embedded cost reality. Hospitals seek to minimize variation across surgical service lines, which encourages standardization on a limited set of blade and handle configurations. At the same time, specialty procedures and microsurgical applications sustain demand for precision blades and ophthalmic knives. The net effect is a market where volume flow favors standardized disposable products, while higher-value niches reward precision engineering and application-specific design.
Manufacturing Scale, Regional Sourcing, and Cost Structure Dynamics
Cost structure remains a decisive competitive lever. Blade manufacturing requires precise metallurgy, controlled edge geometry, reliable sterilization, and consistent packaging. Companies with integrated production and quality systems can manage unit costs more effectively, while smaller or regionally focused producers must compete on flexibility, local service, or niche applications. Regional sourcing strategies are gaining importance as procurement teams look to reduce logistics risk, improve lead-time predictability, and align with local compliance expectations.
Recent distribution developments illustrate how channel strategy is evolving. For example, in early 2025, a Canadian distribution agreement expanded exclusive coverage for a major blade and scalpel portfolio, signaling a push to strengthen regional availability and service reliability. Moves like this reflect a broader pattern: established manufacturers are investing in distribution density and localized support to protect share in regulated, service-intensive markets, while emerging producers pursue export growth and selective partnerships to enter new regions.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Players
The competitive field combines long-established multinational manufacturers, precision-focused producers, and regional exporters with growing scale. The leading companies differentiate along several axes: product range breadth, safety portfolio depth, metallurgical precision, sterilization and sterile packaging capability, and integration into broader perioperative or specialty workflows.
Several strategic profiles are visible across the market. One group emphasizes heritage, broad blade and handle ranges, and comprehensive sterile disposable offerings. These players often compete on consistency, distribution reach, and the ability to serve General Surgery and multiple specialty segments with standardized products. Another group focuses on precision manufacturing and high-sharpness stainless steel products, with particular attention to safety scalpel lines and micro blade options. This positioning appeals to surgical specialties that require fine edge control and reliable performance in delicate procedures.
A third profile is built around regional export strength and cost-competitive sterile disposable manufacturing. These companies have expanded their footprint by offering full lines of carbon steel and stainless steel blades and scalpels, targeting price-sensitive procurement environments while meeting international quality expectations. A fourth profile lies in specialty focus, where ophthalmic surgical knives, micro blades, and dental-oriented scalpel systems create differentiated value in narrower but higher-specification applications. Finally, some broader perioperative solution providers incorporate scalpel blades and handles into integrated surgical workflows, using device availability and service continuity as part of a larger institutional relationship.
Market Structure Evolution: Consolidation Pressure and Targeted Expansion
The high concentration at the top of the market indicates that scale, compliance, and distribution maturity matter. Larger players benefit from the ability to standardize quality systems, manage sterilization at volume, and maintain inventory across multiple regions. At the same time, the long tail of smaller and regional manufacturers remains active, particularly where localized service, flexible order sizes, or specialty products create room for differentiation.
The evolution of the landscape is likely to continue along two tracks. First, established manufacturers will keep strengthening distribution partnerships and regional coverage to protect share and improve service levels. Second, targeted expansion by efficient regional producers and specialty innovators will pressure incumbents in specific segments, especially where disposable adoption is rising and procurement is open to alternative suppliers that can meet compliance requirements at competitive cost. M&A and rebranding activity also reshape the landscape indirectly, as companies reposition portfolios to emphasize safety, specialty precision, or perioperative integration.
Given the embedded cost structure and safety-driven adoption trends, competitive advantage increasingly comes from the ability to deliver standardized sterile disposables with reliable lead times, consistent quality, and safety-aligned design features. In specialty niches, the advantage shifts toward precision, application fit, and clinical trust. Companies that can operate effectively across both tracks—scale-driven standard products and higher-specification specialty offerings—are best placed to defend and expand their positions.
Forward Trends and Commercial Opportunities Through 2032
Continued Mix Shift Toward Sterile Disposable and Safety-Aligned Products
Over the next three to five years, the product mix is expected to keep moving toward single-use sterile disposables and safety-oriented scalpels where protocols and procurement specifications allow. This trend is supported by safety standards, infection control expectations, and the operational simplicity of disposables in high-volume surgical environments. For suppliers, the opportunity lies in scaling sterile disposable capacity, improving packaging and traceability, and aligning product lines with the safety expectations that hospitals are increasingly embedding into purchasing criteria.
A related opportunity is the expansion of safety scalpel adoption in settings that have historically relied on conventional blades. Education, workflow integration, and cost acceptance will influence the pace of adoption, but the direction of travel favors designs that reduce handling risk and support standardized disposal procedures.
Regional Growth and Supply Chain Localization
Regional dynamics will continue to shape growth patterns. North America remains the largest market, supported by established surgical volumes, safety adoption, and mature distribution. Europe follows with substantial demand and stricter validation expectations that reinforce quality and traceability requirements. Asia Pacific represents a meaningful growth path, driven by expanding surgical capacity, increasing procurement professionalism, and growing export competitiveness among efficient manufacturers. Latin America and the Middle East and Africa remain smaller in absolute terms but offer incremental opportunities where access, service, and compliance alignment improve.
Commercially, this points to a strategy of regional reinforcement rather than uniform global rollout. Companies that invest in localized distribution, predictable lead times, and documentation readiness for multiple regulatory environments can capture share more effectively than those relying solely on product price. For investors, regional scalability and channel control are likely to be critical indicators of long-term resilience.
Precision, Specialty, and Workflow-Integrated Positioning
While standardized disposables drive volume, specialty applications sustain higher-margin opportunities. Ophthalmic knives, micro blades, and application-specific scalpel systems require tighter tolerances and greater clinical confidence, which can support differentiated pricing when performance and reliability are demonstrable. At the same time, broader perioperative providers can create value by integrating blade and scalpel availability into larger surgical workflow solutions, making supply reliability and service continuity part of the value proposition.
This bifurcation suggests a practical strategic path: maintain a strong core in standardized sterile disposables to capture volume and safety-driven adoption, while building or strengthening specialty lines that serve precision procedures and specialized surgical workflows. The risk is spreading too thin across unrelated segments; the opportunity is to align precision and workflow integration with genuine clinical need rather than broad but shallow expansion.
Risks and Uncertainties
Several uncertainties could alter the trajectory. Regulatory and validation expectations may tighten further in certain markets, raising compliance costs and slowing the pace at which new entrants can scale. Procurement pressure could intensify if hospitals prioritize cost over safety features in specific budget cycles, temporarily dampening the shift toward premium safety designs. Supply chain disruptions, raw material cost volatility, and sterilization capacity constraints could also affect margin stability and service levels. Finally, because reimbursement does not isolate blade costs, demand can be indirectly affected by changes in surgical procedure volumes, service line economics, and broader healthcare spending patterns.
Strategic Implications for Decision Makers
For Manufacturers
Prioritize the operational foundations that convert market growth into defensible share. That means investing in sterile disposable capacity, quality system maturity, and distribution reliability, while maintaining enough precision capability to serve specialty segments. Standardize core blade and handle configurations where hospital procurement favors consistency, but preserve differentiated safety and micro blade options where clinical value supports them. Build regional channel strength through partnerships or localized service capacity, especially in markets where lead time and documentation readiness influence purchasing decisions.
For Investors
Evaluate businesses on their ability to manage compliance, scale sterile production, and control distribution across regions. Concentration in the market indicates that scale and quality infrastructure matter, but growth opportunities also exist for efficient producers and specialty innovators that can meet safety expectations at competitive cost. When assessing potential investments or partnerships, look for evidence of ISO 13485-aligned quality systems, reliable sterilization and traceability processes, and channel strategies that reduce reliance on a single geography or customer type. Also consider exposure to procedural volume cycles, since blade demand is tied to surgical activity even though reimbursement does not itemize the device separately.
For Procurement and Supply Chain Leaders
Treat blade and scalpel selection as part of total procedure economics rather than an isolated unit-price exercise. Standardize where clinical workflows allow, but preserve access to safety-aligned disposables and precision options for specialties that require them. Evaluate suppliers on consistency, injury-prevention design, inventory reliability, and documentation readiness as much as on price. Where possible, align purchasing specifications with occupational safety standards and infection control goals to reduce downstream operational risk.
Closing Perspective
The surgical blades and scalpels market is moving through a period where growth is steady, safety expectations are rising, and competitive advantage depends on execution quality as much as product design. The mix shift toward sterile disposables, the regulatory and validation environment, and the embedded cost structure of surgical procedures all point in the same direction: future success will belong to organizations that can combine scale, compliance discipline, and targeted precision where it matters most. For leaders navigating this landscape, the most valuable next step is to ground strategy in detailed, segment-level intelligence—covering regional demand patterns, product mix economics, channel dynamics, and competitor positioning—so that decisions on capacity, portfolio focus, and market entry are calibrated to the opportunities and risks that lie ahead.
For detailed analysis of this topic, please visit the official page: Surgical Blades & Scalpels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


