



Commercial Kitchen Ventilation Systems Market: Why 6.8% CAGR Signals Major Shifts

Commercial Kitchen Ventilation Systems Market: Strategic Trends and Commercial Opportunities Through 2032
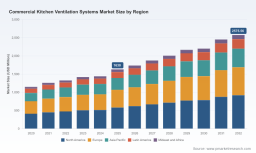
The commercial kitchen ventilation systems market is entering a phase of structural transformation, driven by tightening environmental mandates, accelerating energy-efficiency expectations, and a fundamental shift in how foodservice operators approach kitchen infrastructure. Valued at approximately $1.63 billion in 2025, the market is projected to expand at a compound annual growth rate of 6.8 percent through 2032, crossing the $2.58 billion threshold by the end of the forecast period. The growth trajectory reflects more than incremental replacement demand; it signals a rebalancing of how commercial kitchens are designed, regulated, and optimized for operational cost and compliance performance.
Historical momentum has been steady rather than explosive, with annual revenue progressing from $1.15 billion in 2020 toward the mid-$1.6 billion range by 2025. The acceleration in the 2025-2032 window is rooted in a confluence of regulatory upgrades, retrofit activity in aging foodservice footprints, and manufacturer-level innovation that is converting ventilation from a passive exhaust utility into an active energy and air-quality management asset. For executives, planners, and capital allocators, the strategic question is no longer whether the market will grow, but which sub-segments, geographies, and competitive positions will capture disproportionate value as standards tighten and operating economics shift.
Navigating the Current Inflection Point
Three structural challenges are reshaping how commercial kitchen ventilation markets evolve and how players position themselves within them.
The first is the regulatory ratchet. Kitchen ventilation has historically been governed by a patchwork of fire-safety, mechanical, and food-code requirements. The current trajectory moves beyond containment toward active performance standards. Recent proposals from the California Energy Commission point toward code changes designed to improve energy efficiency and reduce greenhouse gas emissions in commercial kitchens, including the potential introduction of mandatory Demand Control Kitchen Ventilation (DCKV) requirements as the next progression beyond existing standards. When jurisdictional frameworks begin to tie ventilation performance to energy usage and emissions, the market shifts from discretionary spend to compliance-driven investment, which changes the sales cycle, specification logic, and competitive differentiation for manufacturers and service providers alike.
The second challenge is the growing gap between installed base reality and modern performance expectations. Many commercial kitchens continue to operate with legacy exhaust hoods, fixed-speed fans, and non-integrated air management systems that were specified under older mechanical codes and pre-efficiency cost assumptions. Retrofitting these environments requires more than equipment swaps; it demands airflow engineering, grease management coordination, fire suppression compatibility, and controls integration. This elevates project complexity and favors suppliers that can deliver engineered solutions rather than commodity components. It also raises the stakes for installers and service networks, since performance guarantees increasingly depend on proper commissioning and ongoing maintenance.
The third challenge is cost structure volatility interacting with energy economics. Electrical pricing, refrigeration loads, cooking equipment heat output, and building envelope performance all influence the total cost of ownership for kitchen ventilation. A system that performs adequately from a compliance standpoint may still impose avoidable energy expenditure if airflow is not modulated to actual cooking load. As operators face sustained pressure on margins, the economic case for smarter ventilation becomes more compelling, but it also demands clearer quantification of savings, more credible performance data, and integration with broader kitchen energy strategies. The market is therefore moving toward solutions that can demonstrate a measurable link between ventilation control and operating cost reduction.
Key Drivers Behind Market Expansion
Technology Innovation and Demand-Controlled Ventilation
The most consequential technology trend in commercial kitchen ventilation is the shift toward demand-controlled operation. Instead of running exhaust and makeup air at fixed capacities, DCKV systems adjust airflow based on real-time cooking activity, thermal load, or contaminant detection. This approach directly addresses the energy penalty of over-ventilation, which has long been an overlooked source of waste in commercial kitchens. By matching ventilation output to operational demand, facilities can reduce fan energy consumption, lower heating and cooling losses, and improve hood capture efficiency under variable cooking conditions.
This innovation is not occurring in isolation. It is converging with broader building controls, digital commissioning tools, and smarter air-flow management architectures. Providers such as Systemair and Melink illustrate the direction of travel with offerings that combine exhaust performance with smart flow controls and demand-controlled ventilation solutions, while companies with DCKV-focused portfolios such as Gaylord and Melink emphasize modulation as a core value proposition. The strategic implication is clear: ventilation hardware is increasingly evaluated not only by capture area, material durability, and fire-safety conformance, but also by how effectively it integrates with controls that minimize idle energy use.
Residential Ventilation Systems Market
Regulatory Pressure as a Market Accelerator
Regulation is becoming a primary catalyst for both new construction specifications and retrofit programs. The FDA Food Code requires commercial kitchen exhaust systems to capture and contain heat, smoke, grease, and vapors to protect public health, while NFPA 96 sets mandatory requirements for ventilation control and fire protection in commercial cooking operations. These frameworks establish the floor for safe ventilation design. The emerging layer is the energy and emissions dimension, where jurisdictions are exploring requirements that go beyond containment and address efficiency performance.
At the installation and mechanical design level, updated model codes such as the 2021 Uniform Mechanical Code provide the baseline requirements for safe installation of commercial kitchen ventilation and exhaust systems. As local jurisdictions adopt, modify, or layer additional performance expectations on top of these standards, the specification environment becomes more formalized and more consequential. For manufacturers, this creates a dual opportunity: compliance assurance remains a licensing requirement for market participation, but added-value solutions that help operators meet evolving efficiency expectations can command stronger positioning and more resilient demand.
Demand-Side Shifts in Foodservice Operations
The application landscape reflects a broad, diversified demand base rather than reliance on a single end-use channel. Restaurants and cafes continue to represent the largest application share, supported by ongoing build-out, refresh cycles, and the need to upgrade older ventilation installations. Hotels and hospitality facilities contribute a substantial secondary demand stream, where ventilation is tied not only to kitchen safety but also to guest-facing comfort, indoor air quality, and multi-use facility performance. Corporate and industrial canteens, educational institutes, and hospitals and healthcare facilities each bring distinct operating requirements and procurement cycles, broadening the market’s resilience and reducing dependence on any single sector’s investment timing.
Operationally, the demand story is being shaped by labor, throughput, and risk management considerations. Kitchens are under pressure to improve consistency, reduce downtime, and simplify maintenance. Ventilation systems that are easier to commission, cleaner to service, and better aligned with variable cooking loads can improve day-to-day reliability while reducing the operational burden on kitchen staff and facility teams. In institutional and healthcare settings, the air-quality and containment rationale is especially strong, reinforcing ventilation as part of broader facility safety and environmental control strategies.
Supply Chain and Cost Structure Dynamics
Cost structures in commercial kitchen ventilation are influenced by material inputs, fabrication complexity, ratings and certification requirements, and the labor associated with installation and service. For hoods and ducting assemblies, material selection, fabrication tolerances, and fire-rated components can materially affect both pricing and delivery timelines. For controls and makeup air systems, value is increasingly determined by integration capability, sensor reliability, and software-mediated performance optimization rather than by hardware alone.
This changing cost-and-value equation is nudging the market toward more bundled and engineered offers. Suppliers that can coordinate hood design, exhaust and supply airflow, grease management, fire suppression coordination, and controls into a coherent specification are better positioned to manage total project risk and capture more of the value chain. At the same time, component-level suppliers that can deliver certified, cost-competitive hardware with reliable lead times retain an important role, especially in retrofit and maintenance-driven demand. The competitive edge is moving toward coordination, specification support, and documented performance.
Competitive Landscape and Positioning Strategies
The market is characterized by a concentrated set of established manufacturers and a broader tier of regional and application-focused players. Concentration at the top reflects the importance of scale, certification depth, engineered product portfolios, and service reach in winning specification-driven projects. At the same time, fragmentation persists because commercial kitchen ventilation is not a single product category; it spans exhaust hoods, fans and ducting systems, makeup air units, controls and accessories, and installation services, with different competitors leading in different slices.
CaptiveAire Systems stands out as a broad-line manufacturer of commercial kitchen ventilation systems, including exhaust hoods, fans, grease management, and complete HVAC solutions for foodservice operations. Its positioning emphasizes a full-system capability that can address the integrated nature of modern kitchen design, where exhaust, makeup air, and grease handling must work together. Greenheck Fan Corporation similarly occupies a wide portfolio position, offering exhaust hoods, fans, make-up air units, and energy recovery ventilation for restaurants and foodservice. The strategic significance of this breadth is that it allows specification of complementary components under a more unified performance logic, which can reduce integration risk and simplify procurement for larger projects.
Systemair AB brings an advanced-exhaust and air-purification orientation, with high-performance air purifiers, smart air flow controls, and demand-controlled ventilation solutions. This places the company closer to the efficiency and controls frontier, where value is created through modulation, filtration, and system intelligence rather than through hardware volume alone. Gaylord Industries focuses on Demand Control Kitchen Ventilation systems, custom kitchen hoods, and pollution control equipment for commercial foodservice, reinforcing a differentiated stance around active ventilation control and custom engineering. FAST Kitchen Hoods contributes a more specialized, regionally anchored presence as a Canadian manufacturer of cULus-rated commercial kitchen hoods, exhaust systems, island hoods, and low-ceiling hoods for restaurants, illustrating how rating compliance and form-factor specialization can anchor a defensible niche.
Chef’s Deal Restaurant Equipment operates with a service-intensive model as a supplier and installer of comprehensive commercial kitchen ventilation systems, including engineered hoods, make-up air units, ventless exhaust, Type 1 and Type 2 grease hoods, and related accessories. Its recent expansion of its Commercial Kitchen Hood Service portfolio to include fully engineered ventilation systems, professional consultation, customized hood packages, make-up air units, ventless exhaust, Type 1 grease hoods, Type 2 condensate hoods, food truck hoods, pizza oven hoods, fire suppression, and exhaust hood filters and accessories for restaurants, food trucks, retailers, and institutional kitchens reflects a deliberate move toward broader solution coverage and consultative specification support. North American Kitchen Solutions maintains a multi-site U.S. footprint with manufacturing of commercial kitchen hoods, exhaust and supply fans, fire suppression, and portable ventless hood systems, showing how geographic and product diversification can support both project-based and supply-driven demand.
How Leaders Differentiate
Across these players, differentiation tends to cluster around several strategic levers. The first is portfolio breadth versus specialization. Full-line providers compete on integration, specification ease, and project-scale capability. Specialists compete on performance depth, rating expertise, or application fit. The second lever is controls and efficiency capability. As energy and emissions expectations rise, manufacturers that can demonstrate meaningful demand-controlled operation, reliable airflow modulation, and credible energy outcomes are better positioned for specification advantage. The third lever is installation and service reach. Ventilation performance depends heavily on proper sizing, duct routing, commissioning, and ongoing maintenance, so providers with strong field capacity can convert product capability into realized performance. The fourth lever is compliance and ratings fluency. In a market shaped by mechanical codes, fire-safety standards, and food-code requirements, the ability to navigate certification and demonstrate conformance is a basic but essential competitive precondition.
Market Structure Evolution
The competitive structure is likely to evolve along three lines. First, integration pressure will increase as operators and specifiers seek fewer interfaces between hood, fan, makeup air, controls, and suppression. This favors companies that can deliver coordinated designs and may encourage selective partnerships or acquisitions that close capability gaps. Second, the controls and efficiency layer will become more valuable, creating openings for players that can bring software-mediated ventilation management, better sensor integration, and verifiable savings narratives into the market. Third, regional and application-focused specialists will continue to find room to compete, especially where local code interpretation, rating requirements, or niche form factors such as low-ceiling or mobile-food applications create specificity that larger portfolios do not automatically address.
Future Trends and Commercial Opportunities
Efficiency Mandates Will Move From Optional to Expected
The most consequential near-to-medium-term trend is the normalization of demand-controlled and efficiency-oriented ventilation as a standard expectation rather than a premium option. With regulatory discussions increasingly pointing toward mandatory DCKV-style requirements in leading jurisdictions, and with model codes and food-safety standards already establishing the containment baseline, the market is heading toward a two-layer framework: safe capture and fire protection as the foundation, and active efficiency performance as the differentiating expectation. Commercial opportunity lies in products and services that can make demand-controlled operation reliable, easy to commission, and simple to verify after installation. Manufacturers and integrators that can reduce the friction of controls adoption—through clearer specification tools, more robust sensor performance, and stronger field support—will be well placed to convert regulatory momentum into specification share.
Retrofit and Performance Upgrades Will Outpace Pure New-Construction Demand
Given the size and age of existing foodservice footprints, a significant portion of future demand will come from upgrading or replacing ventilation systems that no longer meet current performance, safety, or efficiency expectations. Retrofit demand is more fragmented and more service-intensive than new construction, but it also creates opportunities for engineered assessments, phased replacement programs, and controls retrofits that improve energy performance without full kitchen rebuilds. The commercial opportunity here is in bundled upgrade packages that pair hood or fan replacement with airflow rebalancing, controls integration, and grease management review. Providers that can quantify pre- and post-upgrade performance and reduce operational disruption will have an advantage in this segment.
PW Consulting Automotive & Machinery Research Center
Smart Air Management and Integrated Kitchen Energy Design Will Gain Share
Ventilation is increasingly being evaluated as part of the broader kitchen energy and air-quality system rather than as a standalone exhaust function. This creates a trend toward tighter integration between exhaust, makeup air, temperature control, and demand modulation, with controls acting as the connective tissue. The opportunity is for suppliers that can position kitchen ventilation as an energy-management asset with measurable impact on fan power, thermal load, and indoor comfort. It also opens the door to more sophisticated service models, including performance monitoring, scheduled commissioning checks, and data-informed maintenance. As operators look for ways to manage operating costs and meet internal sustainability expectations, integrated air management solutions will become more relevant and more defensible.
Risks and Uncertainties
The outlook carries meaningful uncertainty. Code adoption is uneven across jurisdictions, so the pace and shape of mandatory efficiency requirements will vary, creating a patchwork rather than a uniform transition. Economic conditions can shift the timing of restaurant build-outs, hospitality renovations, and institutional procurement cycles, affecting demand volatility. Supply chain and input cost pressures can influence hardware pricing and project economics, particularly for fabrication-intensive components. Finally, the promised energy and operational savings from controls-based ventilation depend on correct design, installation, and ongoing calibration; if realized performance falls short of expectations, trust in efficiency narratives can erode. Participants should therefore treat performance validation, service quality, and transparent specification as strategic necessities rather than supporting functions.
Actionable Recommendations for Decision-Makers
For Manufacturers and Solution Providers
Position around integration, not just equipment. The market is rewarding providers that can coordinate hood design, airflow balance, controls, grease management, and fire protection into a coherent offer. Invest in specification support, commissioning expertise, and post-installation performance validation so that efficiency claims are credible and repeatable. Where portfolio breadth is not achievable, build clear differentiation around a specialized strength such as demand-controlled control logic, rating compliance for a specific form factor, or a service model that reduces install and maintenance friction. Monitor regulatory signals closely, especially jurisdictional moves toward efficiency-oriented kitchen ventilation requirements, and prepare specification tools and product configurations that align with the next code progression.
Worldwide Commercial Kitchen Fire Suppression System Market
For Investors and Capital Allocators
Evaluate exposure to the efficiency and controls layer as a distinct value driver. Pure hardware volume plays may continue to perform, but the higher-margin, higher-differentiation opportunity is increasingly tied to demand-controlled ventilation, integration services, and performance verification. Consider the mix of new-construction exposure versus retrofit and service exposure in any target, since retrofit-heavy models can be more resilient to construction-cycle volatility while demanding stronger field and service capabilities. Assess regulatory sensitivity as part of the investment thesis: companies aligned with the direction of tightening efficiency expectations are better positioned than those dependent on discretionary, low-performance specifications. In due diligence, probe installation quality, commissioning processes, and the evidence base for energy or operating-cost claims, because these factors increasingly determine whether a product wins repeat specification.
For Procurement and Facility Decision-Makers
Treat kitchen ventilation as a total-cost and compliance asset, not merely a capex line item. Specify with attention to demand-controlled capability, proper airflow design, grease management integration, and fire-safety conformance, and require clear commissioning and performance verification before project closeout. Evaluate suppliers on their ability to deliver engineered solutions and documented post-installation performance, not only on unit pricing. Where existing systems are underperforming, consider targeted retrofits that improve modulation and control before committing to full replacements, and align ventilation decisions with broader kitchen energy and maintenance strategies to capture operational savings over time.
The commercial kitchen ventilation market is moving from a compliance-and-commodity orientation toward a performance-and-integration orientation. That shift creates winners among companies that can combine certification strength, engineering depth, controls capability, and service reliability, while leaving narrower or purely transactional models exposed to margin and specification pressure. As efficiency expectations mature and retrofit demand expands, the strategic value of timely, granular market intelligence becomes harder to overstate. Decision-makers who understand where regulation is heading, how controls are reshaping operating economics, and which competitive positions are gaining specification advantage will be better equipped to allocate capital, prioritize product roadmaps, and structure procurement around the next phase of market growth.
For detailed analysis of this topic, please visit the official page: Commercial Kitchen Ventilation Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


