



Oil Mist Separator Market: Why 5.3% CAGR and Asia Pacific Lead the 2032 Growth

Strategic Trajectories and Commercial Opportunities in the Global Oil Mist Separator Market
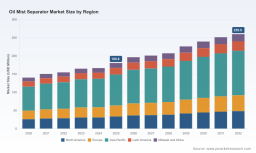
The global market for oil mist separators has entered a phase of measured but steady expansion, reflecting broader shifts in industrial air quality standards, manufacturing precision requirements, and energy efficiency mandates. Valued at approximately 140.5 million USD in 2020, the market climbed to 180.8 million USD by 2025, and is projected to reach 259.9 million USD by 2032. This trajectory translates to a compound annual growth rate of 5.3 percent across the forecast horizon, signaling a maturing yet increasingly dynamic sector. Growth is no longer driven solely by incremental equipment replacement; it is being reshaped by tighter emissions controls, smarter filtration architectures, and cross-regional industrial modernization programs. The market remains moderately concentrated, with a handful of established players capturing a dominant share of contract wins, technology patents, and regional distribution networks. This concentration underscores both the barrier to entry for newcomers and the strategic importance of partnerships, licensing, and targeted product modernization for mid-tier manufacturers. As industrial operators balance compliance obligations with productivity targets, the oil mist separator segment is evolving from a commoditized component category into a value-added system integration opportunity.
Mist Eliminator Market
Market Landscape and Core Challenges
Regulatory Pressure and Performance Verification
The industry is navigating a period where compliance and verification requirements are tightening across multiple jurisdictions. Without listing regional revenue splits or application-specific dollar figures, it is clear that manufacturing footprints in both mature and emerging economies are confronting stricter exposure limits for mineral oil aerosols and particulate matter. Occupational safety frameworks now mandate continuous monitoring approaches and defined time-weighted average thresholds for workplace air quality, forcing plant operators to treat filtration not as an optional add-on but as a baseline operational requirement. At the same time, engine and compressor standards are increasingly calling for uniform testing procedures that cover dust collection efficiency, dust capacity, and oil carry-over measurements. These requirements create a dual challenge: manufacturers must demonstrate consistent performance under standardized test conditions, while end users must integrate separator systems that meet verifiable benchmarks rather than nominal specifications.
Technical Complexity Versus Installation Practicality
A second structural challenge lies in balancing filtration performance with physical integration constraints. Oil mist separators are deployed across diverse machine environments, from compact machining centers to large compressor halls, and each deployment presents distinct airflow, space, and maintenance profiles. Mounted configurations dominate volume applications where direct integration with existing equipment is preferred, while standalone units address centralized extraction and facility-wide air cleaning. The challenge for designers is to maintain high capture efficiency without imposing excessive pressure drops, frequent media replacement cycles, or complex ductwork modifications. Operators increasingly favor solutions that can be retrofitted into legacy lines without extensive downtime, yet they also demand filtration performance that aligns with precision tolerances in food-grade, medical, or high-finish machining contexts. Bridging this gap requires material engineering, flow optimization, and service-friendly filter media designs to advance in tandem.
Consolidating Competition and the Cost of Differentiation
A third challenge is the competitive dynamic shaped by market concentration. When a limited group of firms accounts for more than half of total market activity, incumbents benefit from established distribution channels, reference installations, and long-term service contracts. New entrants or smaller regional manufacturers must therefore compete on niche performance attributes, localized support, or total cost of ownership rather than price alone. This environment rewards companies that can articulate measurable operational savings, energy reduction, or maintenance interval extension, while penalizing those that compete purely on hardware cost. As procurement teams become more technical in their evaluation criteria, the burden on suppliers to provide verifiable performance data, installation guidance, and lifecycle cost models grows heavier.
Key Drivers Shaping Market Evolution
Technology Innovation and Energy-Conscious Filtration Design
Innovation in filtration media, airflow control, and system intelligence is a leading catalyst for change. Recent product introductions highlight a clear shift toward energy-aware extraction systems and higher-precision filter units designed for demanding machining environments. Smart energy-saving devices integrated into oil mist extraction systems are gaining traction, reflecting operational priorities around electricity usage, fan load optimization, and variable airflow demand. In parallel, advanced filter units built for high-precision machining environments emphasize finer aerosol capture, stable performance under variable load conditions, and simplified media replacement. These developments matter because they connect directly to two persistent operator concerns: running costs and process consistency. When a separator can reduce parasitic energy consumption while maintaining capture efficiency, the value proposition extends beyond compliance into operational economics. Manufacturers that embed control logic, condition monitoring, or modular media architectures into their offerings are positioning filtration as an active system component rather than a passive accessory.
Regulatory and Standards Evolution
Policy and standardization activity continues to shape purchasing behavior and engineering requirements. Compressed air quality classifications that define strict oil aerosol limits for the highest cleanliness tiers are reinforcing demand in food-grade, pharmaceutical, and precision industrial applications, where even minimal contamination can affect product integrity or process reliability. At the same time, occupational safety expectations for mineral oil mist exposure are pushing facility managers to adopt continuous monitoring and better containment strategies, particularly in environments where multiple machines contribute to cumulative aerosol loads. In parallel, industrial emissions frameworks in major markets are tightening limits on volatile organic compounds and particulate matter from manufacturing facilities, which indirectly accelerates replacement cycles and upgrades for older separator installations. The net effect is a market where regulations do not merely constrain operations; they actively redirect capital toward more capable filtration and air cleaning architectures. Companies that can map their product capabilities to specific regulatory benchmarks, and document compliance through standardized testing, gain a meaningful advantage in specification-driven procurement processes.
Shifts in End-User Behavior and Operational Priorities
Demand-side behavior is changing as plant operators look beyond immediate compliance and evaluate filtration through the lens of productivity, worker comfort, and equipment longevity. Oil mist that escapes containment can affect visibility, housekeeping frequency, coolant loss, and downstream component reliability, all of which influence total operating cost. As a result, purchasing decisions are increasingly influenced by facility managers and engineering teams who weigh filtration performance alongside ease of maintenance, noise reduction, and integration with existing extraction infrastructure. The emphasis on fog-free environments, clearer workstation conditions, and reduced cleaning cycles reflects a broader operational mindset: air quality is not an isolated environmental metric but a contributor to throughput and labor efficiency. This behavioral shift creates opportunities for suppliers who can present separator systems as part of a holistic air management strategy rather than as standalone compliance devices. Case documentation and field references are becoming more influential in this context, since they translate technical specifications into observable operational outcomes.
Supply Chain Structure and Cost Considerations
Cost structures in the filtration sector are being influenced by material availability, manufacturing precision, and the economics of distribution across regions. High-performance filter media, housing materials, and sealing components must meet durability expectations under continuous operation, while suppliers also face pressure to keep lead times predictable and service parts accessible. In a moderately concentrated market, cost leadership is often less about unit price and more about lifecycle economics: how often media must be replaced, how much pressure loss accumulates over time, and how easily a unit can be serviced without specialized labor. These factors are especially relevant as operators reassess capital expenditure against operating expenditure, particularly in facilities facing rising energy costs or tighter maintenance windows. Suppliers that can standardize core assemblies while offering application-specific customizations tend to manage cost and flexibility more effectively than those pursuing fully bespoke designs for every project. This balance between standardization and adaptation is becoming a defining feature of competitive cost positioning.
PW Consulting Automotive & Machinery Research Center
Competitive Landscape and Leading Strategies
Dominant Players and Strategic Positioning
The competitive field features a mix of long-established manufacturers and specialized filtration providers, each leveraging distinct strengths in engineering heritage, application coverage, and service ecosystems. Companies with multi-decade experience in oil mist collectors and workplace air cleaning solutions have built brand recognition around reliability, broad application familiarity, and continued product iteration. Their strategy often centers on maintaining a wide reference base, expanding into adjacent air quality applications, and reinforcing regional service presence. Other firms emphasize industrial mist collection for compressed air and machine tool environments, using application-specific engineering and standardized performance documentation to win specification-driven projects. A further group focuses on advanced oil mist elimination and industrial air purification, differentiating through modular product families, precision filtration architectures, and integration with broader air management systems.
Additional suppliers contribute to the landscape by targeting specific operational niches. Some specialize in oil mist separation for manufacturing plant compressor and turbine systems, where reliability under continuous duty and resistance to oil carry-over are critical. Others concentrate on ecological and application-tailored separator designs for rotating machines and turbines, positioning around sustainability messaging and customized extraction solutions. There is also a cohort of providers that emphasize universal separator coverage across wide engine power ranges or offer industrial mist separators and collectors optimized for machine tool use. Together, these players illustrate a market where differentiation comes from application alignment, engineering documentation, and the ability to support both centralized and distributed installation strategies.
Oil Water Separator Market
Differentiation Levers in a Concentrated Market
In a market where a small group of firms holds a substantial share, differentiation tends to emerge through several recurring levers. First, product intelligence and energy optimization are increasingly central. The introduction of smart energy-saving devices for extraction systems demonstrates how incremental controls can reduce operating burden while preserving capture performance. Second, application specialization matters. Filter units developed for high-precision machining environments reflect an understanding that contamination limits and process tolerances vary significantly by sector, and that generic solutions may not satisfy the strictest cleanliness classifications. Third, ecosystem support and reference building influence procurement confidence. Trade show participation, case study dissemination, and documented installations help translate technical claims into practical credibility. Fourth, standardization of performance verification is becoming a competitive asset. As testing procedures for inlet air cleaning equipment become more uniform and compressor or engine standards increasingly specify measurement approaches for collection efficiency and oil carry-over, suppliers that proactively align with these protocols gain visibility in specification reviews.
Evolution of the Competitive Structure
Looking at recent developments, the market appears to be moving through a phase of selective consolidation in capability rather than purely in corporate structure. Established players are expanding their portfolios through product line extensions, energy-efficiency features, and targeted applications, while also strengthening visibility through exhibitions, case publications, and regional engagement. At the same time, specialized manufacturers continue to compete by focusing on particular machine types, precision cleanliness requirements, or custom extraction configurations. This creates a landscape where scale advantages coexist with niche strength. New entrants face the challenge of overcoming reference inertia, but they can still gain traction by addressing underserved machine configurations, offering more flexible integration options, or providing superior service and documentation. The likely trajectory is not a wholesale shakeout, but a gradual stratification in which broad-line suppliers dominate volume segments and specialized firms secure positions in high-value or technically demanding applications. For decision makers, this means vendor selection is increasingly about matching system architecture to operational profile rather than choosing from a single category of equivalent products.
Forward Trends and Commercial Implications
Smarter, Energy-Optimized Filtration Systems
Over the next three to five years, one of the most consequential trends will be the deepening integration of energy optimization and control logic into oil mist separation systems. As operating cost sensitivity rises and extraction equipment runs for longer periods across multiple shifts, even modest reductions in fan load or airflow waste can create meaningful savings. Systems that adapt output to actual contamination levels, support easier servicing, and provide clearer performance feedback will be better positioned than static, fixed-performance units. Commercial opportunity lies in bundling filtration hardware with controls, service contracts, and documentation that simplify lifecycle management for plant teams. The upside is real, but it depends on manufacturers delivering measurable savings in field conditions, not just in laboratory benchmarks. If promised energy benefits fail to materialize consistently, buyer confidence in smart features may erode.
Stricter Compliance and Cleanliness-Driven Demand
A second trend is the continuing alignment of separator demand with stricter cleanliness and exposure expectations. As occupational exposure limits, compressed air quality classifications, and industrial emissions expectations become more rigorously enforced or more widely adopted in procurement specifications, facilities will face stronger incentives to replace aging equipment and upgrade filtration performance. This creates a sustained upgrade cycle in sectors where product integrity, worker exposure, or emissions reporting carry direct financial or regulatory consequences. The commercial opportunity is in providing verifiable cleanliness performance, standardized test alignment, and documentation that procurement teams can use in specification and audit processes. The uncertainty is that regulatory implementation pace can differ by region and by facility type, which may create uneven demand timing. Suppliers that assume uniform acceleration across all markets risk misjudging where near-term investment will actually appear.
Service-Led Models and Regional Expansion
A third trend is the shift toward service-oriented commercial models and more deliberate regional execution. As installed bases grow and equipment ages, maintenance intervals, media availability, and local technical support will increasingly influence repeat purchasing and system longevity. Companies that build reliable parts supply, clear replacement procedures, and application-specific guidance can convert initial sales into long-term relationships. Regional expansion also remains relevant, especially where industrial modernization, machining capacity growth, and compressor utilization are increasing. Here, success depends on more than product availability; it requires localized engineering support, understandable installation guidance, and a credible service response timeframe. The opportunity is in building trusted regional presence and repeatable deployment models. The risk is that overextension into too many territories without adequate support infrastructure can dilute reliability and weaken the performance reputation that underpins premium positioning.
Actionable Insights for Decision Makers
For Manufacturers and System Suppliers
Differentiation should be anchored in verifiable performance and operational economics rather than product claims alone. Prioritize control features and filtration designs that reduce energy burden and simplify maintenance, then document those benefits in real installation contexts. Align product language with the testing and cleanliness expectations that procurement teams increasingly reference, and build a portfolio that balances standardized assemblies with application-specific adaptations. Invest in reference deployments and case documentation, because credibility in this market is often earned through observable outcomes in actual facilities. Finally, treat service and parts availability as part of the product, since lifecycle reliability frequently determines whether a sale becomes a repeat contract.
For Investors and Corporate Strategists
The market’s moderate concentration and steady growth profile suggest that value creation will come from companies that can combine technical credibility with cost-aware design and strong service execution. Evaluate exposure not only by installed unit volume but by how well a supplier is positioned for the trends shaping the next decade: energy optimization, stricter clean air expectations, and service-led retention. Watch for firms that can demonstrate consistent field performance, clear compliance alignment, and disciplined regional expansion rather than broad but shallow market claims. Be mindful that demand timing may vary by region and by application, so portfolio resilience matters more than betting on a single growth narrative.
For Procurement Teams and End-User Operators
Selection criteria should extend beyond upfront equipment cost to include pressure drop behavior over time, media replacement frequency, service accessibility, and evidence of compliance with relevant exposure or cleanliness expectations. Where precision, food-grade, or auditoried environments are involved, prioritize suppliers that can provide standardized performance documentation and clear installation guidance. Consider total operational impact, including worker visibility, housekeeping burden, coolant retention, and integration with existing extraction infrastructure. When evaluating newer smart or energy-saving features, request field-oriented performance evidence and confirm that control logic will not add complexity without measurable operational benefit. A disciplined evaluation framework reduces the risk of purchasing a nominally compliant system that creates higher maintenance or energy costs downstream.
Conclusion
The oil mist separator market is advancing along a path defined by tighter compliance expectations, smarter filtration design, and a competitive field that rewards both scale and application focus. Steady growth supported by industrial modernization and cleaner air requirements provides a durable backdrop, but the real commercial differentiation will come from how well suppliers translate performance, energy efficiency, and service reliability into measurable operational value. For manufacturers, the opportunity lies in credible innovation and lifecycle economics. For investors, it lies in backing players with disciplined execution and alignment to the compliance and efficiency trends ahead. For operators, it lies in choosing systems that perform under real conditions, not just in specification sheets. Detailed segmentation data, regional demand patterns, and customized scenario analysis can sharpen these decisions further, and organizations seeking that level of granularity are well positioned to explore the full research depth available on PW Consulting for this market.
For detailed analysis of this topic, please visit the official page: Oil Mist Separator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


