



VTS Market Insights: Beyond the 4.9% CAGR with North America Driving $373M by 2032

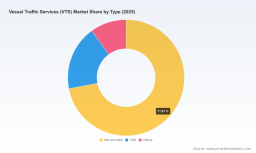
The Strategic Evolution of Vessel Traffic Services: Navigating Market Shifts and Commercial Opportunities (2026–2032)
Market Landscape: Growth Trajectory and Structural Challenges
The global Vessel Traffic Services market has entered a phase of measured acceleration, driven by increasing maritime complexity, regulatory modernization, and the integration of digital navigation infrastructure. From 2020 through 2025, the market expanded from approximately $205 million to $267 million in annual revenue. The forecast period from 2026 to 2032 indicates sustained momentum, with projected revenue reaching $373 million by the end of the horizon. The implied compound annual growth rate of 4.9 percent reflects steady demand rather than explosive expansion, suggesting a maturing but still evolving ecosystem where value creation depends on strategic positioning rather than volume alone.
Several structural shifts define the current inflection point. First, legacy VTS deployments are increasingly reaching end-of-life cycles, creating a replacement and upgrade wave that favors providers capable of delivering interoperable, software-defined platforms rather than isolated hardware installations. Second, maritime authorities and port operators are balancing mandatory reporting requirements with budget constraints, making lifecycle cost, operational resilience, and integration with existing shore-side systems decisive purchase factors. Third, the rise of higher-density traffic in confined waterways and environmentally sensitive corridors is intensifying the need for real-time situational awareness, which in turn pushes vendors toward predictive analytics, advanced radar processing, and integrated information services.
These dynamics are not merely operational concerns; they reshape competitive priorities. Suppliers that can align technology roadmaps with procurement realities—modular upgrades, remote monitoring, and standardized training frameworks—are better positioned to convert modernization demand into durable contract relationships. At the same time, the market’s relatively modest concentration indicates room for differentiated plays, particularly for organizations that can combine domain expertise with adaptable architecture.
Core Drivers: Technology, Regulation, Demand, and Cost Realities
The trajectory of VTS adoption is being pulled by four interconnected forces, each reinforcing the others in ways that create both urgency and optionality for maritime stakeholders.
Technology Innovation and the Shift Toward Integrated, Predictive Platforms
The most visible technological driver is the migration from standalone surveillance and tracking tools toward integrated vessel traffic management ecosystems. Modern deployments increasingly combine radar processing, navigation information services, route planning support, and operator workstations into unified environments. This integration reduces operational silos and allows maritime authorities to manage traffic, respond to incidents, and share hydro-meteo and routing guidance through a single operational picture.
Radar technology itself continues to advance, with solid-state architectures and digital processing improving target discrimination in cluttered port environments and coastal zones. Simulation capabilities are also becoming more central to the value proposition, supporting operator training, scenario rehearsals, and system validation before live deployment. These capabilities lower the operational risk of complex upgrades and help organizations maintain readiness during transition periods.
Importantly, the technology conversation is shifting from capability demonstration to integration assurance. Buyers are less interested in isolated features and more focused on whether a solution can connect with existing navigation systems, port community platforms, and communication networks. Providers that can demonstrate interoperability and maintainability are increasingly differentiating themselves from those that compete purely on sensor specifications.
Regulatory and Standardization Pressures as Catalysts for Modernization
Regulatory frameworks are acting as both a baseline requirement and a modernization trigger. Guidance from the International Maritime Organization emphasizes information services for high-traffic and sensitive areas, including hydro-meteo data provision and route planning support. These expectations raise the operational bar for VTS functions and encourage authorities to invest in systems that can deliver consistent, accessible information to vessel traffic.
Standardization initiatives further reinforce this direction. Recommendations from the International Association of Marine Aids to Navigation and Lighthouse Authorities address operator recruitment, qualifications, and training, promoting consistency in how VTS services are staffed and executed across jurisdictions. Harmonized guidance for inland waterways, where applicable, also supports more predictable procurement and deployment patterns for multi-state or cross-border corridors.
In several high-density regions, mandatory reporting and coordinated traffic management have become entrenched operational practices. This regulatory certainty creates a stable demand base for VTS infrastructure, but it also raises expectations around resilience, redundancy, and information quality. Authorities managing these environments are more likely to prioritize solutions that support long-term service continuity and clear upgrade paths.
Demand-Side Shifts: Port Efficiency, Coastal Traffic, and Operational Safety
On the demand side, port operators and coastal authorities are motivated by a combination of throughput efficiency, safety management, and environmental stewardship. Vessel traffic services are increasingly viewed not only as a safety function but also as an operational enabler that supports scheduling, berthing coordination, and incident mitigation. As traffic density rises in congested corridors, the ability to provide structured information services and coordinated traffic oversight becomes more valuable to port economics and operational reliability.
The commercial rhythm of maritime logistics also matters. Fluctuations in trade flows, port call patterns, and coastal routing can create pockets of peak demand that stress existing systems. VTS platforms that can adapt to variable traffic profiles, provide clear operator support, and integrate information services for route and weather awareness help organizations manage volatility without expanding headcount proportionally. This operational flexibility is a meaningful driver for adoption, particularly in environments where labor availability and training pipelines are constrained.
Supply-Side and Cost Considerations: Total Cost of Ownership and Delivery Models
Cost structures are reshaping procurement behavior. Capital expenditure for new installations remains significant, but lifecycle operating costs—maintenance, software updates, training, and spare parts—are increasingly central to procurement decisions. As more systems move toward software-based management and remote support, vendors are being asked to justify total cost of ownership rather than upfront hardware pricing alone.
Delivery models are adapting in response. Organizations are exploring options that reduce on-site integration risk and streamline ongoing support. Simulation-based training, remote diagnostics, and modular upgrade paths can help mitigate long-term operating burdens. At the same time, supply chain considerations for specialized radar components and communication equipment remain relevant, especially where lead times and customization requirements can affect project schedules. Providers that can stabilize delivery and reduce post-deployment friction gain an advantage in competitive tenders.
Competitive Landscape: Strategic Positioning and Emerging Patterns
The competitive environment for VTS reflects a mix of regional specialization, technology breadth, and an emerging tension between integrated platform providers and focused component or capability specialists. Several themes stand out when examining representative participants and recent developments.
A number of established players are anchored in integrated VTS platforms, coastal surveillance, and maritime traffic management systems, often with strong relationships across port authorities and maritime administrations. Their positioning tends to combine domain expertise with broad system scope, allowing them to address multi-element deployments that span surveillance, information services, and operator workstations. For these organizations, differentiation frequently depends on integration maturity, support infrastructure, and the ability to align with local regulatory and operational expectations.
Other participants emphasize specific layers of the value chain. Some focus on radar and coastal surveillance technology, including solid-state radar series designed for reliable detection in challenging environments. Others concentrate on simulation, operator training, and harbor traffic management solutions that complement live VTS operations. This specialization can be advantageous in projects that require proven sensor performance or robust training environments, especially where procurement teams value targeted capabilities alongside broader system compatibility.
Recent developments illustrate how the landscape is being reshaped by corporate strategy as well as technical cooperation. A major maritime instrumentation group announced plans to spin off its maritime unit as an independent company, with a stock exchange listing targeted for the first half of 2026. This move signals a strategic push to position maritime capabilities as a distinct growth entity, potentially sharpening its focus on VTS, coastal surveillance, and related maritime solutions while giving investors a clearer exposure to the sector’s trajectory.
In parallel, technology partnerships and public showcases are reinforcing capability differentiation. Advanced radar technology was presented at a major defense and security exhibition, alongside a partnership intended to strengthen VTS capabilities. Such moves highlight how vendors are combining hardware, software, and partnership channels to expand credibility and reach in contested procurement environments. At the consultancy level, a major professional services firm was appointed to support the modernization of a major city’s Vessel Traffic Services system, underscoring that transformation programs increasingly require integration, governance, and operational redesign—not just equipment replacement.
Taken together, these patterns suggest a market that is neither fully consolidated nor highly fragmented. The relatively balanced concentration among leading participants leaves space for differentiation, but it also means that advantage is increasingly earned through execution quality, integration credibility, and adaptability to local requirements. New entrants and niche specialists can compete by addressing underserved segments, while larger players can leverage breadth and delivery scale. The likely evolution is not a simple consolidation wave, but a selective blending of platform breadth, specialized technology, and professional services expertise.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
Looking ahead to the 2026–2032 horizon, several trends are likely to define where value is created and where execution risk concentrates.
Trend 1: Software-defined, interoperable VTS platforms will become the default procurement expectation. As modernization programs replace aging infrastructure, authorities will favor solutions that can integrate with existing navigation, communication, and port systems rather than requiring isolated stand-alone environments. This shift increases the importance of interface design, data exchange standards, and vendor support for migration and coexistence during transition phases. Commercial opportunity will accrue to providers that can reduce integration risk and demonstrate repeatable deployment patterns across similar port or coastal contexts.
PW Consulting
Trend 2: Operator readiness and training will move from a supporting function to a core buying criterion. Given the emphasis on standardized recruitment, qualification, and training practices, organizations will increasingly evaluate VTS investments through the lens of workforce sustainability. Simulation-based training, scenario rehearsal, and structured competency development will be treated as part of the system’s operational value rather than as optional add-ons. Suppliers that embed training and readiness into their offerings can strengthen retention and reduce the cost of operational discontinuity during upgrades or staffing transitions.
Trend 3: Regional modernization programs will create uneven but significant demand peaks. Large-scale consultancy-led modernization in high-profile ports and coastal systems, combined with ongoing regulatory drivers and replacement cycles, will generate concentrated demand in select geographies and corridors. This creates opportunities for providers with proven delivery capability and local partnership networks. At the same time, demand will not be uniform; some regions may prioritize inland waterways harmonization or smaller-scale upgrades, while others pursue broader coastal surveillance and traffic management transformation. Commercial planning will need to account for this uneven rhythm rather than assuming a linear global expansion path.
These trends carry embedded uncertainties. Procurement timelines can shift with budget cycles and bureaucratic processes. Technology expectations may evolve faster than delivery capacity, particularly where integration complexity is underestimated. Supply constraints for specialized components can affect project schedules, and regulatory interpretations may differ across jurisdictions, influencing requirement definitions and acceptance criteria. Organizations that anticipate these variables and build flexibility into their offerings and project plans are more likely to convert opportunity into durable outcomes.
Strategic Implications for Decision Makers
For executives, investors, and procurement leaders, the VTS market presents a landscape where steady growth is paired with meaningful differentiation potential. The practical question is not whether demand exists, but how to position for the right segments and reduce execution risk.
Voyage Data Recorders (VDR) Market
For manufacturers and solution providers: prioritize integration maturity and lifecycle serviceability over feature volume. Demonstrating interoperability, remote support, simulation-based training, and modular upgrade paths can strengthen competitive positioning, especially where authorities are managing modernization within constrained operating budgets. It is equally important to align product roadmaps with regulatory expectations around information services and operator readiness, since these are increasingly part of procurement rationale. Companies should also consider targeted partnership or consultancy-led engagement models, particularly for large transformation programs where technology is only one component of a broader operational change.
For investors: evaluate exposure through the lens of platform continuity, service revenue potential, and the ability to participate in modernization waves rather than one-time equipment sales. Corporate restructuring moves, such as spin-offs or separate listings targeting maritime units, can indicate where management believes value is most visible, but they also raise questions about delivery scale, customer concentration, and follow-on investment needs. The most resilient opportunities are likely to be tied to recurring support, training, software evolution, and repeated deployment in similar environments, rather than purely project-based revenue.
For procurement and maritime operators: treat VTS selection as an operational continuity decision, not just a technical purchase. Prioritize systems that reduce long-term operating strain through interoperability, maintainable architecture, and training support, and clarify acceptance criteria around integration, information service quality, and redundancy. Where modernization programs are underway, embedding consultancy or integration expertise early can help align technology with governance, staffing, and change-management requirements, lowering the risk of delivery gaps between equipment installation and operational readiness.
The market’s next phase will reward organizations that can connect technology, regulation, and operational practice in practical, repeatable ways. Detailed segmentation analysis, company-level capability mapping, and region-specific procurement dynamics can sharpen planning significantly, especially for teams evaluating entry points, partnership structures, or expansion timing. For decision makers seeking to move from strategic direction to actionable choices, deeper intelligence on submarket size, competitive positioning, and project-level delivery patterns provides a more precise basis for investment and procurement decisions.
Maritime Intercom Market
Readers looking for a fuller view of market size by segment, regional dynamics, and company-level strategy can explore the complete PW Consulting analysis for granular data and tailored recommendations aligned with specific operating contexts.
For detailed analysis of this topic, please visit the official page: Vessel Traffic Services (VTS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


