



Biologics and Biosimilars Market: Why 10.42% CAGR and $1T+ Growth Redefine the Industry

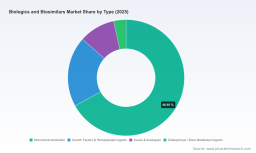
The Biologics and Biosimilars Market: Strategic Trends and Commercial Opportunities Through 2032
Market Trajectory and Structural Challenges
The global market for biologics and biosimilars has entered a sustained expansion phase, with revenue reaching $527.36 billion in 2025 and projected to climb to $1.055 trillion by 2032. This trajectory reflects a compound annual growth rate of approximately 10.42% across the forecast period, signaling robust and compounding demand across therapeutic categories. Historical momentum from 2020 through 2025 demonstrates consistent upward pressure, as the market grew from $321.27 billion to its current level, driven by expanding clinical applications, maturing manufacturing capabilities, and shifting treatment paradigms toward complex biologics. The revenue base is now large enough that even single-digit percentage shifts in adoption or pricing translate into billions of dollars in industry-wide impact.
Despite the headline expansion, the market faces structural friction points that will shape how value is captured over the next several years. First, the disconnect between biosimilar adoption volume and healthcare spending remains pronounced. Regulatory approvals have multiplied, yet biosimilars continue to account for less than 20% of therapeutic market share despite representing over half of total drug expenditure. This gap points to persistent barriers in formulary positioning, interchangeability recognition, and provider confidence rather than a lack of approved alternatives. Second, reimbursement structures are lagging behind product innovation and cost realities. Hospitals and care networks face systemic underfunding, with cumulative underpayments exceeding $100 billion annually, creating margin compression that influences procurement decisions, formulary negotiations, and patient access pathways. These reimbursement constraints can slow the transition from originator biologics to follow-on alternatives even when clinical equivalence is established. Third, the manufacturing and supply base remains geographically concentrated and vulnerable to cost shocks. A significant share of critical inputs, including active pharmaceutical ingredients and sterile injectable capacity, originates from a limited set of international suppliers, while recent trade measures on single-use systems and other process inputs have raised per-batch production costs by 5–10% for mid-scale monoclonal antibody operations. This cost sensitivity matters because biosimilar economics depend on disciplined manufacturing scale and yield optimization to compete against entrenched originator pricing.
Taken together, these conditions define a market where growth is real but uneven, and where competitive advantage will increasingly derive from regulatory strategy, manufacturing resilience, and access-model innovation rather than product approval alone.
Key Drivers Shaping Market Dynamics
The market’s expansion is being propelled by a convergence of scientific, regulatory, demand-side, and supply-side forces that reinforce each other. Understanding these drivers is essential to identifying where commercial opportunity will concentrate.
Technological Innovation and Development Pathways
Developers are benefiting from more efficient pathways to demonstrate biosimilarity and reach the market. Recent regulatory signals have emphasized streamlined approaches to biosimilarity studies, reducing the evidentiary burden for certain follow-on biologics and making interchangeable designations more attainable. These developments matter because interchangeable status can ease pharmacy-level substitution, accelerate formulary inclusion, and support broader utilization without requiring repeated prescriber actions. Alongside regulatory simplification, manufacturing science continues to mature, with process optimization, analytical comparability, and scale-up capabilities improving the economic feasibility of complex molecules. The result is a broader pipeline of candidates targeting high-value therapeutic classes, including monoclonal antibodies and growth-related agents, where originator franchises have historically generated substantial revenue. In this environment, the companies that can compress development timelines while maintaining quality and comparability are best positioned to convert pipeline activity into commercial relevance.
Policy and Regulatory Environment
The regulatory landscape is becoming both more permissive and more operationally complex. Approval activity across 2025 illustrates a steady cadence of decisions across therapeutic categories, including biosimilars in oncology, inflammatory conditions, ophthalmology, and bone metabolism. Interchangeability designations are increasingly recognized as commercially meaningful because they reduce friction in substitution and dispensing. At the same time, regulatory clarity is not uniform across jurisdictions, and developers must navigate divergent expectations for data packages, post-approval commitments, and local market access requirements. For multinational strategies, this means that approval is a necessary but insufficient condition for commercial success; the regulatory win must be paired with launch readiness, health-system engagement, and reimbursement alignment. Companies that anticipate these downstream requirements earlier in development are likely to achieve faster and more durable revenue realization.
Demand-Side Shifts in Clinical and Economic Behavior
On the demand side, payers, providers, and health systems are under sustained pressure to manage biologic expenditure without sacrificing clinical outcomes. This has accelerated interest in alternatives that can preserve efficacy while lowering net cost, especially in high-volume indications such as oncology and autoimmune care. The clinical adoption of biosimilars, however, depends not only on cost but also on confidence in comparability, supply continuity, and therapeutic interchange policies. As health networks consolidate and formulary management becomes more centralized, procurement decisions are increasingly influenced by total-cost-of-care considerations, supply reliability, and contract flexibility. This environment favors developers and distributors that can offer predictable supply, clear pharmacovigilance support, and implementation assistance that reduces the operational burden of switching or introducing new products. In short, demand is moving toward value-supported adoption rather than price-only decision-making.
Cost Structure and Supply Chain Realities
Cost dynamics are reshaping the competitive equation. Biologics manufacturing remains capital and process intensive, and the economics of biosimilars hinge on achieving reliable yields, minimizing batch failures, and controlling input costs. The concentration of critical materials and sterile manufacturing capacity in a limited number of geographies adds exposure to logistics disruption and pricing volatility. Recent trade-related cost increases on process inputs have demonstrated how even moderate cost pressure can affect per-batch economics for mid-scale production. At the same time, reimbursement pressure on providers creates downstream demand for cost predictability. These forces are likely to increase the premium on vertically integrated capabilities, dual-sourcing strategies, and manufacturing footprints that balance scale with resilience. For commercial strategies, it means that supply chain credibility is becoming part of the value proposition, especially in categories where therapeutic continuity is non-negotiable.
Competitive Landscape and Strategic Positioning
The competitive field is shaped by a mix of established multinationals, focused biosimilar specialists, and regional players expanding internationally. Rather than competing solely on molecule count, leading companies are differentiating through portfolio architecture, manufacturing readiness, regulatory cadence, and commercialization execution.
Differentiated Strategic Postures
Several patterns emerge among the companies setting the pace. Amgen has pursued a broad commercial biosimilars footprint, extending across multiple approved products and therapeutic areas, with cumulative portfolio sales exceeding $13 billion since 2018 and continued approvals and launches in 2025. Its strategy emphasizes scale in already-commercialized categories and sustained investment in follow-on biologics that can integrate into existing care pathways. Pfizer has leaned into operational expansion and manufacturing infrastructure as a foundation for growth, with notable operational gains in select categories and a biosimilar portfolio spanning oncology and other areas. This reflects a model in which manufacturing and supply reliability serve as enablers of commercial traction. Sandoz has positioned itself as a dedicated leader in high-quality follow-on biologics, advancing multiple FDA approvals and launches in 2025, with an emphasis on being a specialized partner for health systems seeking established biosimilar options. Celltrion has signaled an aggressive long-term expansion roadmap with a large product target set by the end of the decade, supported by new facility activity and recent launches, indicating a strategy oriented toward volume, geographic reach, and portfolio breadth. Biocon Biologics and Alvotech have each advanced recent approvals and launches, reflecting a focus on executing specific high-value biosimilar opportunities with FDA engagement in 2025. Formycon has concentrated on ophthalmology biosimilars with multiple approved candidates and 2025 launch activity, illustrating the value of indication focus where switching dynamics and specialty distribution can be managed deliberately. Samsung Bioepis has built a multi-product approval base and pursued U.S. commercialization partnerships, showing the importance of partnership structures in markets where launch execution depends on established distribution and accounts access. Fresenius Kabi has continued to expand its biosimilar portfolio in oncology and inflammatory treatment areas with 2025 regulatory activity, underscoring the role of integrated supplier profiles in certain procurement environments.
Across these approaches, a common thread is that approval momentum is increasingly paired with execution readiness. The companies gaining commercial ground are those that combine regulatory progress with manufacturing capacity, switching support, and reimbursement engagement.
Evolving Market Structure
The industry is likely to evolve through a combination of specialization and consolidation pressure. Pure-play biosimilar developers may continue to differentiate by therapeutic focus or by geographic expansion, while larger firms may seek to integrate biosimilars into broader portfolios for bundling, channel access, and risk diversification. The approval pipeline remains active, but fragmentation can create challenges in market access, pricing discipline, and brand recognition unless companies build differentiated commercial models. At the same time, new entrants may find opportunity in underserved indication segments, regional market expansion, and partnership-enabled commercialization rather than in head-to-head competition in saturated categories. Over the next several years, the market will likely reward players that can convert molecule-level activity into durable access, repeat utilization, and reliable supply.
Future Trends and Commercial Implications (2026–2032)
Several forward-looking trends are likely to define how value is created and captured across the forecast period.
Trend One: Interchangeability and Access Design as Commercial Levers
As interchangeable designations and simplified comparability pathways become more accessible, the commercial differentiator will shift toward access design. Products that can be integrated into substitution workflows, supported by clear pharmacist and prescriber guidance, and reinforced by health-system contracting are more likely to convert approval momentum into utilization. The commercial opportunity lies not just in bringing a biosimilar to market, but in shaping the adoption pathway so that it reduces friction for providers and predictability for payers. Companies that invest early in access strategy, including payer engagement, guideline alignment, and implementation support, may secure faster and more defensible market positions.
Worldwide Aflibercept Biosimilars Market
Trend Two: Manufacturing Resilience as a Competitive Asset
Supply concentration and input cost sensitivity will continue to elevate the importance of manufacturing resilience. The companies that can demonstrate dual sourcing, validated scale-up, and consistent batch performance will have a stronger value proposition in categories where continuity is critical. This trend also creates opportunity for partners and suppliers that can support process efficiency, single-use system optimization, and regional capacity strategies. For commercial planning, resilience will increasingly be part of the procurement narrative, especially where health systems are balancing cost control with clinical reliability.
Trend Three: Portfolio and Partnership Strategies to Manage Fragmentation
With a growing number of approved biosimilars and expanding indication coverage, fragmentation will intensify unless managed through portfolio logic and partnership models. There is opportunity in building focused portfolios that span complementary molecules, indications, or geographies, and in using partnerships to accelerate market access in regions where local execution capability is essential. This approach can help companies avoid competing solely on individual molecule price and instead create value through breadth, predictability, and service integration. The strategic implication is that commercial success will increasingly depend on how well companies assemble and execute a portfolio rather than on isolated product launches.
PW Consulting
These trends carry inherent uncertainties. Regulatory expectations may continue to evolve, reimbursement pressure could intensify, and cost shocks related to inputs or trade policy may affect margin profiles. In addition, provider confidence and formulary dynamics may vary by region and therapeutic class, creating uneven adoption even when approval and interchangeability are in place. Businesses should therefore treat growth as an opportunity to be engineered through access, supply, and execution, not as an automatic outcome of pipeline breadth.
Actionable Guidance for Decision-Makers
Different roles in the market face distinct strategic priorities, but all benefit from sharper visibility into pipeline timing, approval cadence, access requirements, and supply resilience.
For Manufacturers and Developers
Prioritize development and launch plans that integrate regulatory strategy with access readiness. Harmonize comparability, interchangeability, and substitution considerations early so that approval translates into smoother adoption. Strengthen manufacturing throughput, input diversification, and quality consistency to protect economics and supply credibility. Consider portfolio design that balances high-volume categories with focused indication plays, and use partnerships where local commercialization capability can accelerate uptake.
For Investors
Evaluate opportunities through a lens that combines pipeline progress with commercial execution capability. Approval announcements are necessary signals, but the durability of value depends on manufacturing readiness, reimbursement positioning, and access design. Pay attention to companies that can demonstrate repeatable launch execution, cost discipline, and credible supply continuity, particularly in categories where switching and utilization depend on health-system confidence. Diversification across therapeutic classes and geographic expansion should be assessed in the context of execution risk rather than treated as automatic growth drivers.
Worldwide Neulasta (Pegfilgrastim) and Biosimilar Market
For Procurement and Health-System Leaders
Use biosimilar adoption as a structured component of total-cost-of-care management rather than a narrow price comparison. Evaluate supply reliability, pharmacovigilance support, implementation assistance, and interchangeability status alongside net cost. Build contracting approaches that reward predictability and continuity, and align formulary decisions with provider workflows to reduce switching friction. A disciplined adoption strategy can support cost management while preserving clinical confidence and therapeutic continuity.
Navigating this market successfully depends on timely, granular intelligence across approvals, access dynamics, manufacturing constraints, and competitive moves. The broader trajectory is clear, but the details that determine commercial outcomes are often segment-specific and time-sensitive. For decision-makers seeking deeper segmentation data, regional nuance, and tailored strategic recommendations, the full PW Consulting research report provides a more detailed view of where to focus resources and how to structure execution for the 2026–2032 period.
For detailed analysis of this topic, please visit the official page: Biologics and Biosimilars Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


