



Bone Cement Market: 5.8% CAGR Trajectory and 2032 Outlook Beyond the Numbers

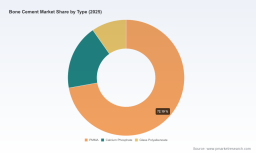
Strategic Shifts and Commercial Opportunities in the Global Bone Cement Market
The global bone cement market has evolved from a mature, commoditized segment into a dynamically regulated and clinically critical component of orthopedic and spinal care. Valued at approximately $1,226.41 million in 2025, the market has demonstrated consistent expansion over the 2020–2025 period, building on a 2020 baseline of $986.72 million. Forward projections through 2032 place the market at $1,823.54 million, reflecting a compound annual growth rate of 5.8 percent. This trajectory is not merely a function of aging demographics or surgical volume growth; it reflects a structural recalibration driven by clinical outcomes, regulatory tightening, supply chain fragility, and targeted reimbursement shifts. For executives, investors, and procurement leaders, the market presents clear expansion signals but also demands disciplined attention to resilience, differentiation, and compliance readiness.
The current landscape is defined by concentrated market power, wide product divergence, and a sector-wide reckoning with operational vulnerability. Understanding where value will accrue over the next several years requires moving beyond headline market size and examining the underlying forces reshaping procurement, R&D prioritization, and competitive positioning.
Market Landscape and Core Pressures
The bone cement market operates at the intersection of orthopedic reconstruction, trauma fixation, and vertebral augmentation. Historical performance from 2020 through 2025 shows a market that has absorbed inflationary pressures on raw materials, adapted to evolving regulatory expectations, and navigated shifting surgical preferences. The 5.8 percent CAGR projected across 2026–2032 indicates steady, not explosive, expansion. Such growth requires durable clinical adoption, predictable reimbursement pathways, and manufacturing reliability rather than purely volume-driven expansion.
Three structural challenges currently shape strategic decision-making across the value chain:
- Supply concentration and operational fragility: Highly consolidated supply bases create single points of failure. When a major production site experiences packaging faults, sterilization delays, or logistics disruptions, downstream surgical schedules, hospital procurement plans, and regional formularies can be disrupted within weeks. The February 2026 Heraeus Medical production interruption, which temporarily halted pouch bone cement output and delayed first global releases until late June 2026, illustrates how quickly supply reliance can expose procurement vulnerability.
- Regulatory burden and certification timelines: The transition from legacy device frameworks to stricter conformity assessments has raised the bar for market entry and product retention. Manufacturers must align formulation consistency, packaging integrity, traceability, and clinical documentation across jurisdictions. Compliance is no longer a checkbox exercise; it determines which products remain eligible for hospital tenders and which can be marketed across border regions without rework.
- Reimbursement pressure and value-based procurement: Health systems increasingly scrutinize implant and cement selection through total episode-of-care lenses rather than unit price alone. Even where add-on payments or technology-specific coverage exist, procurement teams compare clinical handling characteristics, infection management implications, radiopacity, viscosity profiles, and compatibility with delivery systems. The market rewards products that reduce revision risk, simplify intraoperative workflow, and support predictable supply conditions.
Key Drivers Reshaping the Market
Technological Innovation and Product Differentiation
Innovation in bone cement is increasingly oriented toward clinical reliability and surgical workflow rather than generic material substitution. High- and low-viscosity formulations, radiopaque integration, antibiotic loading strategies, and controlled handling windows are central differentiators. Advances in delivery systems, mixing consistency, and packaging design directly affect intraoperative ease and waste reduction. Products designed to support infection management while maintaining mechanical fixation properties are gaining attention, particularly in arthroplasty and trauma applications where postoperative complications carry high downstream costs.
The February 2026 Biocomposites launch of SYNICEM high- and low-viscosity gentamicin-loaded variants in the UK market demonstrates how targeted product availability can serve both clinical continuity and supply diversification. Similarly, the August 2025 CMS approval of CERAMENT G for New Technology Add-On Payment, providing up to $5,687.50 in additional reimbursement when costs exceed thresholds for open fractures, signals that reimbursement mechanisms can materially influence the commercial pull of differentiated bone cement products. Technology that aligns clinical benefit with reimbursable pathways is better positioned for sustained adoption.
Policy, Regulation, and Compliance-Driven Competition
Regulatory frameworks are reshaping competitive standing. Certification under updated medical device regulations, 510(k) clearances, and re-certifications of legacy product lines affect which companies can scale regionally without interruption. The February 2025 MDR certification for Heraeus Medical’s COPAL G+V Bone Cement and the May 2025 FDA 510(k) clearance for Teknimed F20 bone cement used with the VCFix Spinal System highlight how regulatory achievements act as commercial enablers, not administrative formalities.
For manufacturers, regulatory readiness determines market access windows. For buyers, certifications influence procurement risk and tendering eligibility. The practical implication is that compliance sophistication increasingly separates suppliers that can maintain uninterrupted hospital supply from those dependent on stopgap arrangements.
Demand-Side Shifts in Surgical Practice and Health System Procurement
Surgical demand continues to be shaped by the rising prevalence of osteoarthritis, fragility fractures, and vertebral compression fractures, alongside broader access to joint replacement and spinal augmentation procedures. Yet demand is not uniform across indications. Arthroplasty remains the dominant application, but vertebral augmentation and kyphoplasty continue to draw procedural growth in aging populations, particularly where minimally invasive stabilization is favored.
At the same time, procurement behavior is shifting toward resilience. NHS England’s February 2026 update detailing alternative supply arrangements from Zimmer Biomet and Johnson & Johnson in response to Heraeus constraints illustrates how health systems now treat multi-sourcing, qualification of alternate products, and regional stock buffering as operational necessities. Demand-side behavior is therefore reinforcing supply diversification, qualification readiness, and preference for products with proven handling profiles and delivery system compatibility.
Supply Chain Dynamics and Cost Structure Realities
Bone cement manufacturing relies on resin chemistry, powder-liquid blending precision, sterilization, packaging, and cold-chain or controlled storage considerations where applicable. Cost structures are sensitive to raw material volatility, packaging integrity requirements, and batch consistency. The Heraeus packaging fault demonstrates that even high-quality formulations can be constrained by downstream packaging logistics rather than the cement chemistry itself. For suppliers, the implication is that process control across the full production and packaging chain is a commercial asset, not merely an operational concern.
PW Consulting
For buyers, cost management increasingly involves total cost of procedure rather than cement unit price. Product consistency, reduced waste, reliable delivery, and minimized risk of substitution delays all contribute to cost outcomes that matter to finance and clinical leadership alike.
Synthetic Bone Graft Market
Competitive Landscape and Strategic Positioning
The market is moderately concentrated. The combined share of the top three competitors is approximately 49.5 percent, while the top five reach about 68.2 percent. This concentration reflects the presence of established orthopedic and spinal device leaders, but it also leaves meaningful room for specialized players with strong regional footing, differentiated infection-control offerings, or focused vertebral augmentation solutions.
Leading companies have carved out positions through product families, indication focus, and supply reliability strategies:
- Heraeus Medical has built recognition around high-viscosity antibiotic-loaded PMMA options, including Palacos, COPAL, and Refobacin. Its positioning ties closely to arthroplasty and trauma fixation, and its MDR certification of COPAL G+V in February 2025 reinforced compliance readiness even as the February 2026 packaging disruption exposed supply vulnerability.
- Zimmer Biomet supplies Biomet Bone Cement and Refobacin Bone Cement for joint arthroplasty. Its role as an alternative supplier for NHS England in February 2026 highlights how established portfolios can gain procurement traction during constraint events when alternate products are already qualified or rapidly deployable.
- DePuy Synthes (Johnson & Johnson) offers SMARTSET and DePuy CMW bone cements for hip and knee procedures. As part of a broader orthopedic reconstruction ecosystem, its strength lies in integrated procedure support and the ability to serve as a qualified alternate when supply disruptions affect other vendors.
- Stryker emphasizes KYPHON and Simplex P bone cements for vertebroplasty and orthopedic fixation. Its relevance in spinal augmentation and targeted vertebral applications gives it a differentiated angle within a broader musculoskeletal portfolio.
- Tecres S.p.A. focuses on radiopaque PMMA bone cements and delivery systems for arthroplasty. The September 2025 acquisition of majority assets from Next Science LTD expanded its orthopedic infection control footprint, signaling a strategic move toward portfolio depth and infection-related differentiation.
- Biocomposites has strengthened its profile through SYNICEM high- and low-viscosity antibiotic-loaded cements for orthopedic infection management. Its accelerated UK launch in February 2026 underscores how specialized antibiotic-loaded options can move from long-term product strategy to immediate supply continuity tool during national constraints.
- OsteoRemedies LLC provides SPECTRUM and related PMMA bone cements for orthopedic and joint replacement use, positioning within a competitive arthroplasty-focused segment where reliability and handling matter.
- Medtronic Sofamor Danek supports vertebroplasty and spinal augmentation through KYPHON HV-R and ACTIVOS bone cements, reinforcing a spinal intervention orientation aligned with vertebral augmentation demand.
- Arthrex, Inc. offers G3 40 and G3A 40 radiopaque and gentamicin-loaded PMMA options for joint and shoulder procedures, highlighting niche procedural relevance and antibiotic-loading differentiation.
- Amber Implants combines Teknimed F20 PMMA bone cement with the VCFix Spinal System for vertebral fracture treatment. FDA 510(k) clearance in May 2025 for this combination reflects how system-plus-cement positioning can shape adoption in vertebral fracture workflows.
The competitive evolution is trending toward three overlapping dynamics. First, integration continues as larger portfolios add infection-control assets and cement-plus-delivery combinations, a pattern reinforced by Tecres’ September 2025 acquisition. Second, differentiation is sharpening around viscosity options, radiopacity, antibiotic loading, and intraoperative handling rather than commodity substitution. Third, new entrants and regional specialists remain viable where they can serve localized supply needs, provide niche antibiotic-loaded formulations, or fill qualification gaps during disruption events. The practical lesson is that competitive advantage in this market increasingly depends on the ability to maintain certification continuity, demonstrate handling reliability, and qualify alternative supply pathways before crises occur.
Forward Outlook and Commercial Opportunities
Trend 1: Resilience as a Procurement Criterion
Over the next three to five years, hospital systems and regional procurement groups are likely to treat supply resilience as a primary purchasing criterion alongside clinical performance. The February 2026 disruption and the rapid qualification of alternative products show that buyers are reassessing single-source dependency, stock buffers, and secondary supplier readiness. Commercial opportunity lies in suppliers that can offer dual-source compatibility, predictable batch integrity, packaging reliability, and transparent lead-time communication. Manufacturers that proactively support qualification of alternate SKUs or interoperable delivery systems may gain preferential placement in future tenders.
Trend 2: Differentiation Through Infection Management and Clinical Workflow
Antibiotic-loaded formulations, viscosity options tailored to procedural needs, and cement-plus-delivery system designs are likely to command stronger commercial interest where they reduce complication risk and simplify surgical handling. The accelerated UK launch of gentamicin-loaded SYNICEM variants and CMS coverage support for differentiated open-fracture products indicate that reimbursement and clinical need can reinforce each other when product evidence and handling advantages align. Companies that invest in evidence generation, procedural compatibility, and packaging or mixing consistency are better positioned to capture value beyond base volume growth.
Trend 3: Regulatory Licensing as Strategic Gatekeeping
Certification events are becoming commercial inflection points. MDR certification, FDA 510(k) clearances, and re-certification of legacy lines determine whether products remain on formulary, can be tendered across regions, and can be scaled during disruption. Expected regulatory scrutiny on packaging, traceability, and documentation will likely reward manufacturers with mature quality systems and penalize those with unresolved compliance gaps. For investors and strategists, regulatory readiness is a leading indicator of market access durability.
Potential risks and uncertainties include continued raw material volatility, disruption of packaging or sterilization lines, uneven reimbursement adoption across regions, and the possibility that procedural mix shifts could alter demand intensity for specific cement types. Health systems may also adopt stricter value-based criteria that compress margins unless manufacturers can demonstrate differentiated clinical or workflow benefits.
Strategic Recommendations for Decision Makers
For Manufacturers
- Treat production and packaging control as a competitive asset. Quality systems should extend beyond formulation to include packaging integrity, release consistency, and rapid escalation protocols. Disruption response capability is now part of product value proposition.
- Build multi-indication and multi-viscosity portfolios deliberately. Products that support both arthroplasty and spinal applications, or that offer antibiotic-loaded and standard formulations with compatible delivery systems, can capture broader procurement relevance and improve resilience during regional constraints.
- Align regulatory and reimbursement strategy early. Certification milestones and coverage decisions should inform launch sequencing, indication prioritization, and commercial messaging. Where add-on payment pathways exist, evidence generation and coding readiness can materially improve adoption.
For Investors
- Prioritize companies with certification continuity, diversified supply options, and differentiated infection-control or spinal-augmentation positioning. Market growth will be uneven, and durable value is more likely where regulatory readiness and product differentiation reduce exposure to single-point supply failures.
- Assess supply-chain exposure as part of valuation. Manufacturing concentration, packaging dependency, and regional qualification readiness can materially affect revenue continuity. Disciplined due diligence should include scenario planning around disruption events similar to the February 2026 production halt.
For Procurement and Health System Leaders
- Formalize alternate supplier qualification before constraints emerge. Pre-qualification of compatible products, delivery systems, and antibiotic-loaded variants reduces procedural disruption when primary supply is delayed.
- Evaluate total procedural cost and workflow impact alongside unit price. Cement consistency, intraoperative handling, packaging reliability, and supply predictability influence operating room efficiency and downstream complication risk, which often carry greater financial impact than cement price alone.
For executives and investors seeking segmentation-level revenue splits, regional growth sensitivities, detailed company positioning, and scenario modeling across supply disruption and regulatory timelines, deeper data and customized analysis are essential. PW Consulting’s full research report provides granular market sizing, segmentation detail, competitive benchmarking, and procurement strategy frameworks to support planning beyond the aggregate trends outlined here.
Bone Cement for Spine Market
For detailed analysis of this topic, please visit the official page: Bone Cement Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


