



Cheque Scanner Market: Why the 5.6% CAGR and APAC Shift Change Everything

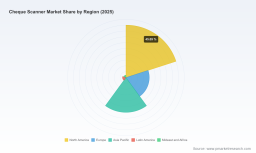
Strategic Trends and Commercial Opportunities in the Cheque Scanner Market
The global cheque scanner market has entered a phase of steady structural expansion, driven by the ongoing digitization of financial back-office operations and the gradual modernization of check processing infrastructure. By 2025, the market has crossed a significant revenue milestone, with industry data placing the total market size at approximately $1 billion. Looking ahead to a forecast period spanning 2026 through 2032, the sector is projected to grow at a compound annual growth rate of 5.6 percent, reaching a multi-billion-dollar valuation by the end of the decade. While this growth trajectory may appear measured in percentage terms, the underlying dynamics reveal a market undergoing meaningful technological maturation, regulatory alignment, and shifting usage patterns across geographic and operational segments.
Document Scanner Market
The historical progression from 2020 through 2025 illustrates a consistent upward curve, reflecting incremental investments by banks and financial institutions to replace legacy handling methods with intelligent imaging solutions. The forecast period suggests that this momentum will continue, albeit with shifting drivers as the market moves from early adoption phases into more mature deployment cycles. As the installed base expands and end-user expectations around speed, image fidelity, and remote processing capabilities evolve, manufacturers and solution providers face an increasingly nuanced landscape where differentiation depends less on basic scanning functionality and more on integration, workflow optimization, and compliance readiness.
Market Maturity and Core Challenges
Operational Scale and Legacy Transition Pressure
One of the defining characteristics of the current market environment is the tension between established processing habits and the operational need to accelerate digitization. Cheque scanners are no longer viewed simply as point hardware; they are components of broader capture ecosystems that must interact with network infrastructure, image quality standards, and downstream processing workflows. Institutions deploying these systems are balancing the need to reduce physical check handling time with the reality that many branches and back-office environments still operate with heterogeneous equipment, varying floor space constraints, and different throughput requirements. This creates a challenge for vendors seeking scalable deployment models and for buyers who must justify standardization across multiple locations.
A second challenge lies in aligning hardware innovation with regulatory expectations. Image quality and data retention requirements have become embedded in the operational fabric of check processing. Systems must not only scan efficiently but also produce images that satisfy established transmission and retention protocols. This regulatory backdrop raises the technical bar for new entrants and reinforces the importance of long-term compatibility, which in turn favors manufacturers with sustained product development roadmaps and robust service networks.
Fragmentation and Coordination Across Use Cases
A third pressure point is the uneven pace of adoption across different operational settings. Some environments prioritize high-volume teller capture and centralized processing, while others require compact desktop solutions that can support distributed branch operations or remote deposit workflows. The coexistence of these divergent needs complicates product strategy, as manufacturers must balance volume-oriented engineering with user-friendly, low-footprint designs. At the same time, end-users are increasingly evaluating scanners as part of broader cost-efficiency and processing-time initiatives, meaning that purchase decisions are increasingly tied to total workflow performance rather than unit-level features alone.
Core Drivers Shaping Market Direction
Technological Innovation and Processing Accuracy
Technological advancement remains one of the most visible catalysts for demand. Modern scanning platforms are being engineered to improve MICR reading accuracy, enhance image capture under varied conditions, and support faster throughput without sacrificing image quality. Recent product introductions illustrate how manufacturers are responding to these expectations. In late 2025, Digital Check Corp. introduced the next-generation TellerScan TS250 UV ultraviolet cheque scanner, succeeding the TS240 model and designed for distribution through its global reseller network. Alongside this, the company emphasized updated CheXpress CX35 and CX35-Network models featuring a zero-footprint design and Smart Button technology. These updates signal a broader industry shift toward compact form factors, simplified operator interaction, and modularity that supports both localized and networked deployment scenarios.
The emphasis on ultraviolet imaging, network-capable configurations, and streamlined physical design reflects a market that is increasingly attentive to space constraints, operator ergonomics, and the ability to integrate scanning into digitally connected branch environments. As imaging specifications become more tightly aligned with downstream processing requirements, scanner performance is evolving from a stand-alone specification into a workflow enabler.
Regulatory Frameworks and Image-Based Clearing Standards
Policy and regulatory frameworks continue to play a central role in shaping procurement behavior and technology requirements. The Check Clearing for the 21st Century Act has provided the legal foundation for image-based clearing, requiring participating institutions to maintain image retention capabilities and implement standardized transmission protocols. This framework has helped accelerate the transition toward digital check processing by giving institutions a clear regulatory basis for moving away from purely physical handling.
Complementing that foundation, Federal Reserve guidelines have established minimum image quality standards for check processing, setting technical specifications that modern scanners must satisfy. These quality mandates have practical commercial consequences: they influence product specifications, encourage consistent image output across different environments, and raise the importance of compliance-grade engineering. For manufacturers, this means that competitive advantage increasingly depends on delivering hardware that reliably meets regulatory image expectations while also reducing operator error and rework.
Demand-Side Behavior and Branch-Level Efficiency Goals
Demand-side dynamics are being reshaped by institutional priorities around processing speed, cost control, and branch-level efficiency. U.S. banks process, analyze, and clear a large volume of checks each day, and many are installing scanners at various branches to shorten the overall clearing cycle. This operational push aligns with broader government guidance that encourages the use of digital checks and image-based workflows. As a result, scanner adoption is increasingly tied to measurable time savings, reduced manual intervention, and faster reconciliation.
At the same time, demand is not limited to large centralized banking operations. Distributed environments that require remote deposit capture and localized image acquisition are also contributing to purchasing activity. This broadening usage profile is encouraging vendors to develop solutions that can serve both high-volume teller environments and smaller-scale branch or back-office settings, creating a more diverse demand base than in earlier phases of market development.
Cost Structures and Deployment Economics
Cost considerations continue to influence how quickly and broadly scanner technology is adopted. Institutions weigh not only upfront hardware expenditure but also installation complexity, maintenance demands, and the ability to standardize devices across sites. The growing availability of network-enabled and space-efficient models is reshaping these economics by reducing some of the physical and operational friction associated with deployment. When a scanner can be integrated into existing branch layouts without extensive floor space requirements, and when it can interface cleanly with capture workflows, the total cost of adoption becomes more attractive relative to the operational benefits it delivers.
PW Consulting Automotive & Machinery Research Center
Supply-side dynamics also matter. Manufacturers with established distribution channels and global reseller networks are better positioned to scale new models efficiently, while those with broader imaging and document capture portfolios can offer complementary capabilities that strengthen the value proposition for end-users seeking integrated solutions.
Competitive Landscape and Leading Strategies
Established Players and Product-Line Differentiation
The competitive field is shaped by a mix of specialized cheque scanner manufacturers and broader imaging and financial systems providers. Digital Check Corp., headquartered in Northbrook, Illinois, continues to emphasize teller capture, remote deposit, and high-volume production imaging through products such as the CheXpress CX35 and TellerScan TS250 series. Its recent product moves highlight an emphasis on refreshed imaging features, network-ready configurations, and reseller-led distribution, reinforcing a strategy centered on product continuity and broad availability.
Panini S.p.A., based in Turin, Italy, positions itself around intelligent cheque scanners such as the EverneXt and Vision X lines, targeting distributed check capture and remote deposit applications. Its approach reflects an orientation toward intelligent capture functionality and flexibility across deployment contexts. Epson America, Inc. offers desktop models like the TM-S1000II and TM-S1000II-NW, combining MICR reading with RDC and back-office capture features, while Canon U.S.A., Inc. supports the imageFORMULA CR-series for desktop and check transport imaging. These players illustrate how established imaging brands leverage document capture expertise to compete in cheque scanning by emphasizing reliability, ergonomic design, and integration with broader office or branch imaging ecosystems.
Currency Count Machine Market
Banking-Centric and Systems-Integrated Approaches
Other competitors bring a stronger systems-integration orientation. ARCA Tech Systems, LLC provides LS40 and LS100 scanners for teller and remote deposit capture, while RDM Corporation supplies network-focused models such as the EC9000i and EC9600i for image capture and MICR applications. NCR Voyix Corporation aligns cheque scanning with broader banking and retail capture systems, positioning scanners as components of integrated financial processing environments rather than standalone devices.
This divergence in positioning matters strategically. Some manufacturers compete primarily on hardware refinement and product-line breadth, while others compete on integration, workflow compatibility, and the ability to match scanner capabilities to institutional capture systems. A market concentration measure indicates that the top three firms account for roughly 24.6 percent of revenue and the top five for about 26.2 percent, suggesting a landscape that remains relatively dispersed while still featuring recognizable leaders with distinct strategic identities.
Evolution of the Competitive Structure
The competitive structure appears to be evolving along several axes. One is the continued refinement of product families to serve both centralized and distributed use cases. Another is the increasing importance of compliance-grade image quality and network readiness as baseline expectations rather than premium differentiators. A third is the role of distribution and integration partnerships in extending reach, especially in environments where branch technology decisions are made in coordination with broader banking technology roadmaps.
New entrants and adjacent imaging brands may find opportunities in niche deployment scenarios or in specific geographic markets where regional service support and localized product features matter. At the same time, established players benefit from product maturity, regulatory familiarity, and existing relationships with financial institutions. The net effect is likely to be a market where competition intensifies not primarily through price alone, but through reliability, integration ease, and the ability to reduce operational friction in real-world branch and back-office settings.
Future Trajectory and Emerging Opportunities
Deeper Integration of Scanning into Digital Capture Workflows
Over the next three to five years, one of the most important trends is likely to be the further integration of cheque scanners into digitally connected capture workflows. As institutions continue to prioritize faster clearing cycles and reduced manual handling, scanners will increasingly be evaluated in relation to how well they support remote deposit capture, networked branch operations, and image-based reconciliation. This creates commercial opportunities for manufacturers that can offer hardware with strong compatibility, straightforward configuration, and predictable service requirements. It also creates opportunities for solution providers that can bundle scanning with workflow software, image quality assurance, and operational support.
Growth in Distributed and Space-Constrained Deployments
A second trend is the continued expansion of distributed capture models, especially in environments where compact, easy-to-deploy devices are preferred. The move toward zero-footprint designs and simplified operator controls suggests that end-users are placing greater value on branch-friendly equipment that can be installed without major layout changes. As a result, there may be growing demand for desktop and low-profile scanners that still meet image quality and MICR reading expectations. For manufacturers, this trend rewards engineering that balances performance with form factor, while for buyers it opens the door to broader standardization across locations with different physical constraints.
Regulatory Alignment as a Stable Demand Anchor
A third trend is the ongoing role of regulatory compliance as a stabilizing force behind procurement. Because image-based clearing frameworks and quality standards are embedded in operational practice, demand for scanners that satisfy these requirements is unlikely to disappear even if overall market growth moderates in certain periods. This creates a degree of structural resilience, but it also means that product roadmaps must keep pace with evolving image expectations and transmission protocols. Companies that treat compliance alignment as a core engineering priority rather than an add-on are better positioned to maintain continuity in purchasing environments where auditability and image retention remain critical.
Risk Factors and Uncertainty
Despite these favorable structural signals, several uncertainties bear watching. If macroeconomic conditions constrain institutional spending, procurement cycles may lengthen, particularly for non-essential hardware upgrades. If imaging standards or clearing protocols shift materially, manufacturers may need to adapt product specifications more quickly than anticipated. In addition, as more functions become digitized and centralized, certain branch-level capture needs could consolidate into fewer device categories, potentially intensifying competition among suppliers seeking to remain relevant across a narrower set of deployment scenarios. Finally, competitive pressure from adjacent imaging technologies and integrated capture platforms could limit standalone scanner growth in segments where end-users prefer bundled solutions.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Leaders
Product strategy should prioritize three areas. First, keep image quality, MICR reliability, and network compatibility at the center of engineering roadmaps, since these capabilities increasingly function as baseline requirements rather than optional features. Second, invest in deployment-friendly design that reduces installation friction, especially for branch and distributed environments where floor space and setup simplicity matter. Third, strengthen channel and integration partnerships so that new models can reach end-users efficiently and align with broader capture ecosystems. Companies that can demonstrate measurable improvements in throughput, ease of use, and compliance-readiness will be better positioned to justify premium positioning in a market that is maturing but still expanding.
For Investors and Market Observers
From an investment perspective, the market's projected mid-single-digit growth path suggests a sector that is expanding steadily rather than erupting explosively, which makes differentiation and execution quality especially important. Attention should focus on manufacturers with clear product continuity, strong distribution reach, and proven alignment with banking workflow needs. It is also worth monitoring how integration-focused players and broader imaging brands compete for the same procurement budgets, since this can influence share dynamics across both specialized and conglomerate competitors. In this environment, value creation is likely to come from companies that can sustain relevance across multiple deployment models while adapting to regulatory and workflow evolution.
For Procurement and Banking Technology Buyers
For institutions evaluating scanner purchases, the priority should be to assess total workflow impact rather than device specifications in isolation. Key considerations include how well a scanner integrates with existing capture and processing systems, whether it meets applicable image quality expectations, how easily it can be standardized across locations, and what service and support model accompanies the hardware. Given the growing variety of form factors and network-capable options, procurement teams should also weigh whether compact desktop solutions, teller-oriented high-throughput units, or network-integrated devices best match the operational profile of each site. Aligning device selection with branch layout, processing volume, and compliance requirements can reduce implementation friction and improve long-term return on deployment.
As the market continues to evolve from basic scanning toward integrated, compliance-aligned capture environments, the strategic picture becomes more nuanced and more opportunity-rich for organizations that have access to detailed, up-to-date segmentation and competitive data. A deeper review of regional and application-level deployment patterns, product roadmap sequencing, and company-level positioning can help decision-makers translate broad market momentum into concrete procurement, investment, and product decisions. For those seeking a more granular view of these dynamics, the full PW Consulting research report provides expanded segmentation detail, competitive profiling, and customized strategic scenarios tailored to specific operational contexts.
For detailed analysis of this topic, please visit the official page: Cheque Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


