



Fiber Cement Market 2026: Asia Pacific's 9.79B Demand Reshapes Growth Beyond 4.08% CAGR

Strategic Trends and Commercial Opportunities in the Fiber Cement Market: A 2032 Outlook
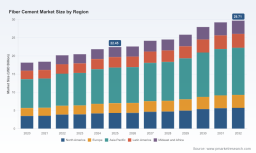
The global fiber cement market has established itself as a cornerstone of modern construction materials, driven by the demand for durable, fire-resistant, and low-maintenance building envelopes. As of 2025, the market is valued at 22.45 billion USD, reflecting steady growth from 18.17 billion USD in 2020. This trajectory indicates a compound annual growth rate of approximately 4.08% through 2032, signaling a mature yet expanding sector. The forecast period from 2026 to 2032 suggests continued momentum, with projected revenues reaching nearly 29.71 billion USD by the end of the decade. This growth is not uniform; it is shaped by regional dynamics, technological advancements, and shifting regulatory landscapes. For executives and investors, understanding the underlying forces behind these figures is critical to capitalizing on emerging opportunities while mitigating structural risks.
Fiber Cement Board Market
Market Resilience Amidst Structural Headwinds
Despite the positive growth trajectory, the industry faces significant challenges that demand strategic attention. The market is characterized by high concentration, with the top three players commanding 60% of the revenue and the top five holding 70%. Such consolidation creates barriers for new entrants and places pressure on mid-tier manufacturers to differentiate or consolidate. Additionally, the production of fiber cement involves fibrous silicate minerals, which have come under increased regulatory scrutiny. In 2025, the United States Environmental Protection Agency issued instructions on safe use and exposure during manufacturing, while the government of British Columbia proposed additional safety measures for plants handling these materials. These regulatory shifts introduce compliance costs and operational complexities that can erode margins if not managed proactively. Furthermore, raw material price fluctuations for cement and cellulose have raised production costs, compounding the pressure from rising labor expenses in high-cost regions.
The Inflection Point: Compliance vs. Innovation
The industry is currently at an inflection point where regulatory compliance and technological innovation intersect. Manufacturers must navigate the dual challenge of adhering to stricter safety protocols while simultaneously investing in product enhancements that justify premium pricing. The balance between cost efficiency and safety standards is becoming a key differentiator. Companies that treat compliance as a mere obligation risk falling behind, whereas those that integrate safety into their operational ethos can leverage it as a competitive advantage. This dynamic is reshaping the competitive landscape, favoring firms with robust R&D capabilities and agile supply chains.
Cement Boards Market
Key Drivers Shaping Market Evolution
Several core factors are propelling the fiber cement market forward, creating a complex environment where strategic agility is paramount.
Technological Innovation and Product Differentiation
Innovation remains a primary catalyst for growth. Manufacturers are continuously expanding their portfolios to meet diverse architectural and performance needs. For instance, in February 2025, James Hardie Building Products Inc. unveiled new and expanded Hardie® products, including Artisan Trim, at the NAHB International Builders' Show. This move highlights the industry's focus on aesthetic versatility and customization, allowing fiber cement to compete more effectively with traditional materials like wood and vinyl. Such product unveilings are not merely incremental; they represent a strategic push to capture higher-margin segments within the siding and trim categories. As consumers and builders increasingly demand materials that offer both durability and design flexibility, companies that lead in product innovation are well-positioned to capture market share.
Regulatory Environment and Standardization
Regulatory developments are fundamentally altering the market's operational framework. In October 2025, ICC-ES proposed new criteria for fibre-cement siding complying with ASTM C1186 or ISO 8336 in both combustible and noncombustible construction. This standardization effort aims to clarify performance expectations and facilitate broader adoption in construction projects where fire safety is paramount. Simultaneously, environmental regulations regarding fibrous silicate minerals are tightening. The EPA's guidelines on safe use and exposure, along with provincial measures in British Columbia, signal a global trend toward stricter occupational and environmental health standards. While these regulations increase compliance burdens, they also raise the barrier to entry, potentially consolidating the market further around established players with the resources to manage complex regulatory requirements. Standardization can also open new application avenues, particularly in commercial and multi-family residential sectors where code compliance is a critical decision factor.
Demand-Side Shifts and Cost Pressures
On the demand side, the construction industry's preference for low-maintenance and long-lasting materials continues to drive adoption. Fiber cement's resistance to rot, pests, and fire aligns with the growing emphasis on sustainable and resilient building practices. However, cost structures are evolving. Raw material price volatility for cement and cellulose directly impacts production economics, forcing manufacturers to optimize supply chains or pass costs to customers. Concurrently, the cost of living in high-cost states drives up both labor and material costs for fiber cement siding projects, which can dampen demand in price-sensitive segments. This economic pressure is prompting buyers to evaluate total cost of ownership rather than upfront prices, favoring materials that reduce lifecycle maintenance expenses. Manufacturers must therefore communicate value propositions that extend beyond unit price, emphasizing durability and energy efficiency benefits.
Supply Chain Dynamics and Regional Concentration
Supply chain resilience has become a focal point, particularly given the geographic distribution of production and consumption. Asia Pacific represents the largest revenue contributor, reflecting rapid urbanization and infrastructure development in the region. North America follows as a significant market, driven by residential renovation and new construction activity. The concentration of revenue in these regions underscores the importance of localized supply chains and distribution networks. Disruptions in raw material sourcing or logistics can have outsized impacts, making diversification and strategic partnerships essential. Companies are increasingly investing in regional manufacturing capabilities to reduce lead times and mitigate currency or tariff risks. This localization trend also supports faster response to regional building codes and consumer preferences.
Competitive Landscape and Leadership Strategies
The fiber cement market is defined by a mix of global giants and regional specialists, each pursuing distinct strategies to secure their position.
Strategic Positioning of Leading Players
James Hardie Industries PLC, headquartered in Ireland, maintains a strong focus on Hardie® fiber cement siding and backer boards, leveraging its brand recognition and extensive distribution network in North America. The company's recent activities, such as the three-year exclusive agreement with Davidson Homes announced in May 2025, illustrate a strategy of deepening partnerships with key builders to secure volume and market presence. This approach not only guarantees supply volume for Hardie® siding and trim products but also embeds the brand into the builder's product specifications, creating switching costs for competitors.
ETEX Group, based in Belgium, specializes in fiber cement boards and sheets, catering to a broad range of construction applications. Their strategy emphasizes product versatility and technical performance, positioning them as a reliable supplier for both residential and commercial projects. Saint-Gobain, a France-based multinational, offers fiber cement products for construction applications, benefiting from its vast resources and cross-industry synergies. The company's scale allows it to invest in sustainability initiatives and global distribution, appealing to large-scale developers and institutional buyers who prioritize supplier stability and comprehensive product lines.
Nichiha Corporation from Japan focuses on high-performance fiber cement panels and siding, leveraging technological expertise to deliver products with superior durability and aesthetic qualities. This focus on high-performance segments allows them to command premium pricing in markets that value advanced material properties. Cembrit Holding A/S, headquartered in Denmark, provides fiber cement siding and exterior products, with a strong presence in European markets where aesthetic preferences and regulatory standards differ from those in North America.
In the United States, companies like Allura USA and American Fiber Cement Corporation offer fiber cement siding products and boards, competing on regional availability and customer service. Allura USA's focus on fiber cement siding products positions it as a direct competitor in the residential siding segment, where brand loyalty and installer networks play crucial roles. American Fiber Cement Corporation's offering of fiber cement boards and sheets addresses both siding and industrial applications, diversifying its revenue streams.
Elementia Materials from Mexico supplies fiber cement products for construction, capitalizing on its proximity to the North American market and cost advantages. Everest Industries Limited, based in India, produces fiber cement boards, tapping into the growing demand for affordable yet durable building materials in emerging economies. CSR Limited in Australia provides fiber cement products, serving the Asia Pacific region with a focus on local market requirements. Plycem Corporation and Swisspearl Group, both US and Switzerland-based respectively, offer fiber cement siding, boards, and cladding, emphasizing quality and design in their respective markets.
PW Consulting
Competitive Dynamics and Market Evolution
The competitive landscape is evolving through a combination of integration, differentiation, and selective entry. The high market concentration suggests that mergers and acquisitions may continue as larger players seek to expand their geographic reach or product portfolios. However, niche players are finding opportunities by specializing in specific applications, such as high-performance panels or decorative trim, where they can build strong brand identities. New entrants face significant hurdles due to regulatory barriers and the capital intensity of manufacturing, but strategic partnerships or acquisitions of smaller brands can provide a pathway to market. The trend toward exclusive distribution agreements, as seen with James Hardie and Davidson Homes, indicates a shift toward securing dedicated channel partnerships to ensure stable demand and reduce competitive pressure in key accounts.
Future Trends and Commercial Opportunities (2026-2032)
Looking ahead, several trends will shape the fiber cement market, presenting both opportunities and risks for stakeholders.
Trend 1: Consolidation of Standards and Expansion into New Applications
As regulatory bodies like ICC-ES finalize criteria for fibre-cement siding, the market is likely to see a harmonization of standards that facilitates broader adoption in commercial and multi-family construction. This trend opens opportunities for manufacturers to develop products that exceed new performance benchmarks, positioning them as preferred choices for code-compliant projects. The clarification of combustible and noncombustible construction usage can unlock new revenue streams, particularly in regions where fire safety regulations have previously limited material choices. Companies that proactively align their product development with these standards can gain first-mover advantage in emerging application segments.
Trend 2: Supply Chain Localization and Cost Optimization
Continued raw material volatility and labor cost pressures will drive further localization of supply chains. Manufacturers will increasingly invest in regional production facilities to reduce logistics costs and respond faster to local demand fluctuations. This trend favors companies with the capital to expand capacity or form joint ventures with local partners. For investors, regions with growing construction activity and favorable cost structures, such as parts of Asia Pacific and Latin America, may offer higher growth potential. However, localization also requires navigating diverse regulatory environments and building local expertise, which can be resource-intensive. Opportunities exist for firms that can balance global scale with local agility, leveraging regional hubs to serve nearby markets efficiently.
Trend 3: Sustainability and Lifecycle Value as Purchasing Drivers
Sustainability is becoming a more prominent factor in material selection, driven by both regulatory requirements and consumer preference for eco-friendly buildings. Fiber cement's durability and resistance to environmental degradation align with lifecycle assessment criteria, potentially giving it an edge over materials with shorter lifespans or higher maintenance needs. Manufacturers that can provide transparent data on environmental impact, recycling potential, and energy efficiency benefits will be better positioned to capture projects with green building certifications. This trend also creates opportunities for innovation in formulations that reduce the use of regulated materials or improve recyclability. However, the risk lies in greenwashing accusations or failure to substantiate claims, which can damage brand reputation. Stakeholders must ensure that sustainability messaging is backed by verifiable data and third-party certifications.
Actionable Insights for Decision Makers
For executives, investors, and procurement professionals, navigating the fiber cement market requires a clear understanding of where to focus efforts and resources.
For Manufacturers and Producers
Prioritize innovation in product lines that address emerging aesthetic and performance demands, such as specialized trim and high-performance panels. Invest in compliance infrastructure to navigate evolving regulations regarding fibrous silicate minerals and product standards, turning these requirements into a competitive moat. Explore strategic partnerships or exclusive agreements with key builders and distributors to secure demand and reduce channel conflict. Additionally, evaluate supply chain resilience by diversifying raw material sources and considering regional production investments to mitigate cost volatility and logistics risks. Building a robust installer and contractor network can also enhance market penetration, as these groups influence product specification at the project level.
For Investors and Capital Allocators
Focus on companies with strong market positions, high concentration advantages, and the capability to invest in R&D and compliance. The market's growth trajectory suggests steady returns, but selectivity is crucial given the concentration and regulatory risks. Look for firms that demonstrate adaptability to regional demand shifts and have strategies to manage raw material and labor cost pressures. Consider the potential of consolidation plays, where acquiring regional players can accelerate market entry or product diversification. Due diligence should include a thorough assessment of regulatory exposure, supply chain dependencies, and the sustainability of competitive advantages in a market where barriers to entry are rising.
For Procurement and Construction Decision Makers
Evaluate fiber cement products based on total cost of ownership, including durability, maintenance requirements, and compliance with local building codes. Engage with suppliers that offer transparent information on product performance, safety standards, and environmental impact. Consider the reputational and operational risks associated with supply chain disruptions; diversifying suppliers or selecting manufacturers with localized production can mitigate these risks. Stay informed about evolving standards, such as the proposed ICC-ES criteria, to ensure that selected materials meet current and future code requirements. Building relationships with manufacturers that provide technical support and installer training can also reduce installation errors and improve project outcomes.
Accessing Detailed Intelligence for Strategic Advantage
The fiber cement market presents a complex array of opportunities and challenges that require granular data and tailored analysis to navigate effectively. While macroeconomic trends and competitive dynamics provide a high-level view, the specific nuances of regional demand, segment performance, and company-level strategies are essential for making informed decisions. Detailed segmentation data, including breakdowns by region, type, and application, can reveal hidden growth pockets and inform targeted market entry or expansion plans. Furthermore, customized insights into supply chain dynamics, regulatory timelines, and competitor benchmarking can help organizations anticipate shifts and allocate resources with precision. For those seeking to deepen their understanding and refine their strategic planning, accessing comprehensive research reports with granular segmentation and proprietary analysis is a valuable step toward securing a competitive edge in this evolving market.
For detailed analysis of this topic, please visit the official page: Fiber Cement Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


