



Bromine Market 2026: Why 5.5% CAGR and Asia’s 1.23B Demand Shift the DNA of Global Competition

Bromine Market Outlook 2026–2032: Strategic Shifts and Commercial Opportunities
Market Overview and Core Challenges
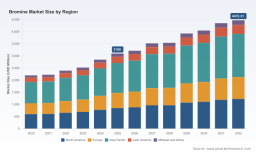
The global bromine market is entering a phase of measured but structurally significant growth. Revenues expanded from approximately $2.2 billion in 2020 to an estimated $3.1 billion in 2025, with forward indicators pointing toward a sustained annual growth rate of roughly 5.5 percent through 2032. By the end of the forecast period, total market value is projected to exceed $4.4 billion. This trajectory reflects more than cyclical recovery; it signals a market being reshaped by diverging regional supply realities, tightening environmental controls, and shifting demand patterns across industrial, energy, and specialty chemical end-use sectors.
Despite the positive top-line momentum, the market faces a set of interconnected challenges that reward strategic foresight rather than passive participation. Three structural pressures stand out as particularly consequential for commercial decision-making.
First, supply concentration and geographic vulnerability continue to define market stability. Bromine extraction relies heavily on natural brine deposits that are inherently localized. Operations tied to a few major basins face disproportionate exposure to regulatory shifts, resource management constraints, and geopolitical friction. When supply from these nodes is interrupted or restricted, downstream manufacturers and formulators experience cost variability and procurement uncertainty that cannot always be smoothed through inventory alone.
Second, environmental and operational regulations are increasingly reshaping production economics. Jurisdictions with significant brine processing capacity have moved to tighten oversight of extraction and handling practices. These measures are necessary from a sustainability and safety standpoint, but they also introduce compliance costs, operational pauses, or capacity reductions that ripple through the supply chain. The result is a market in which price stability is less a function of raw commodity dynamics and more a function of regulatory resilience and operational adaptability.
Third, demand is bifurcating in ways that complicate long-term planning. Traditional applications tied to industrial formulations and energy services remain foundational, yet growth is increasingly concentrated in specialty and pharmaceutical pathways. Companies that depend on a single demand profile are more exposed to substitution pressure, margin compression, or regional policy swings. The market now favors players who can navigate between steady bulk demand and higher-value, specification-sensitive applications.
These challenges do not undermine the market’s growth narrative; they clarify it. The opportunity lies in recognizing that bromine is transitioning from a largely commoditized input to a more strategically managed material where supply security, regulatory readiness, and application-specific differentiation determine competitive advantage.
Key Drivers of Market Change
Innovation and Product Specialization
Technological progress in bromine chemistry is steadily expanding the value that end-users can extract from bromine-based compounds. Rather than competing purely on volume, leading manufacturers are investing in higher-purity grades, controlled derivative portfolios, and application-tailored formulations. This shift matters because downstream sectors increasingly demand consistency, contaminant control, and reproducible performance, especially where bromine acts as a building block in complex synthesis pathways.
The trend is visible in pharmaceutical and fine chemical production, where bromine-derived intermediates support the synthesis of active ingredients used in sedatives, antiseptics, and oncology-related therapies. As drug manufacturing scales in major production hubs, the need for reliable, specification-grade bromine inputs grows in tandem. Companies that can supply with consistent purity and documented quality controls are gaining preference over those competing primarily on base price. In this context, innovation is less about dramatic breakthroughs and more about the cumulative value of precision, reliability, and technical support.
Regulatory and Policy Influence
Policy and regulatory developments are now central drivers of market behavior, not peripheral compliance issues. Environmental oversight of brine operations has intensified in several regions, influencing production continuity and cost structures. At the same time, safety standards and handling requirements affect logistics, storage, and customer qualification processes. These forces create a market where regulatory agility has become a competitive asset.
The commercial implication is straightforward: producers and distributors that can demonstrate robust compliance frameworks, predictable operating practices, and transparent sourcing are better positioned to retain and expand customer relationships during periods of regulatory tightening. Conversely, operations that depend on lenient enforcement environments or have limited flexibility to adjust processes face higher risk of disruption and price instability. Regulatory change is therefore acting as a filter, rewarding disciplined operators and reshaping procurement preferences across the value chain.
Demand-Side Shifts in Energy, Construction, and Healthcare
Demand patterns are evolving on multiple fronts. In oil and gas drilling, bromine-based fluids remain important for well completion and operational performance, sustaining demand from energy service activity. At the same time, the flame retardant segment continues to anchor a substantial share of consumption, driven by ongoing requirements in electrical equipment, building materials, and transportation components. These applications benefit from long-lived infrastructure and equipment cycles, providing a stable baseline for market activity.
Beyond these core uses, healthcare and specialty chemical demand is becoming increasingly influential. Growth in pharmaceutical manufacturing, together with rising interest in bromine-based intermediates for targeted chemical synthesis, is expanding consumption among formulators and producers seeking higher-value output. This does not replace traditional demand, but it alters the composition of growth. Companies that can serve both bulk industrial needs and specification-driven specialty applications are capturing a broader set of revenue opportunities than those locked into a single demand channel.
Supply Chain and Cost Structure Dynamics
Cost structures in the bromine market are increasingly shaped by location-specific factors rather than uniform global benchmarks. Production tied to stable domestic feedstock and favorable operating conditions can offer a meaningful buffer against international price volatility. By contrast, supply dependent on distant or constrained brine sources may be more exposed to energy costs, logistics complexity, and operational interruptions.
This divergence has practical consequences for procurement and production strategy. Buyers in regions with access to steady local supply are often better positioned to manage cost predictability, while those reliant on international flows must account for geopolitical, regulatory, and logistical risk in sourcing decisions. For producers, the implication is that cost leadership is no longer purely a function of scale; it also depends on securing resilient feedstock access, optimizing handling and transport, and maintaining operational continuity under changing environmental and policy conditions.
Competitive Landscape and Leading Strategies
The bromine market is concentrated among a group of well-positioned producers and specialty suppliers, with the top three firms accounting for roughly two-thirds of market share and the top five approaching four-fifths. This concentration reflects the capital intensity of brine-based extraction, the technical requirements of derivative production, and the importance of long-term customer qualification in pharmaceutical and industrial applications. Yet the landscape is not static; it is evolving through investment partnerships, regional specialization, and increasing divergence between bulk suppliers and fine-chemical-focused entrants.
Albemarle Corporation stands out for its scale and breadth across elemental bromine and derivatives serving industrial and pharmaceutical markets. Its positioning benefits from integrated capabilities, established customer relationships, and a presence in regions that can help insulate certain buyers from global price volatility. ICL Group Ltd has built a strong identity around bromine and bromine-based compounds sourced from Dead Sea brines, emphasizing industrial solutions and derivatives. Its operations illustrate both the advantages and the vulnerabilities of geographically concentrated feedstock: strong cost and supply advantages under normal conditions, but heightened sensitivity to environmental and operational disruptions.
LANXESS AG and Tosoh Corporation represent important nodes in the value chain for flame retardants, organobromines, and fine chemical intermediates. Their relevance lies in the ability to connect bromine supply with downstream application requirements, particularly where performance specifications and chemical consistency are critical. Gulf Resources Inc. reflects the importance of regional brine-based production and export capacity, while TETRA Technologies Inc. reinforces the link between bromine supply and energy-sector applications. Tata Chemicals Limited and Hindustan Salts Limited highlight the growing role of Indian producers in serving industrial, technical, and specialty demand.
In parallel, a cluster of firms with stronger fine-chemical and pharmaceutical orientations is gaining relevance. Archean Chemical Industries Ltd. has established a notable position in liquid bromine supply with high-purity offerings for pharmaceutical use. Jordan Bromine Company Ltd. operates as an exclusive regional producer serving industrial and pharmaceutical applications, and its strategic connection with broader regional partners underscores the role of investment alignment in capacity expansion. Chemada Fine Chemicals, Solaris ChemTech Industries Ltd., and Agrocel Industries Pvt. Ltd. illustrate how specialized manufacturers are carving out value in pharmaceutical, agrochemical, and intermediate segments by focusing on precision, customer-specific requirements, and application knowledge rather than competing solely on commodity terms. Honeywell International Inc. further rounds out the landscape as a supplier of bromine-based products and derivatives for industrial chemicals and performance materials, reinforcing the breadth of demand across multiple end markets.
PW Consulting
The strategic takeaway is that competitive advantage in this market is increasingly multidimensional. Scale remains important, but differentiation is coming from supply reliability, purity and quality assurance, regional reach, and the ability to serve both industrial and specialty pathways. Recent developments reinforce this direction. In January 2025, Arab Potash Company and Albemarle Corporation signed a joint investment agreement to expand bromine production capacity at Jordan Bromine Company, signaling that capacity growth is being pursued through partnership structures that combine regional resource access with established technical and commercial capabilities. Meanwhile, the July 2025 launch of Ipratropium Bromide Nasal Solution by Lupin Limited in the United States illustrates how bromine-based pharmaceutical products continue to enter competitive markets in forms that demand consistent raw material quality and regulatory readiness upstream.
Looking forward, the market is likely to see both consolidation and targeted fragmentation. Consolidation may continue where scale, feedstock access, and integrated derivative capabilities create durable advantages. Fragmentation is equally plausible in fine chemicals and pharmaceutical intermediates, where smaller or more specialized producers can compete on purity, customization, and technical service. New entry will probably remain limited at the raw extraction level due to resource and regulatory barriers, but value-added derivative production and application-specific formulation remain open avenues for disciplined players.
Future Trends and Commercial Implications
Trend 1: Supply Resilience Will Become a Primary Commercial Differentiator
Over the next three to five years, customers are likely to place increasing weight on suppliers that can demonstrate predictable continuity, transparent sourcing, and the ability to absorb or mitigate disruptions. This is not simply a procurement preference; it reflects the reality that brine-based supply is exposed to environmental, operational, and geopolitical variables. Companies that invest in diversified supply relationships, contingency planning, and clear quality documentation will be better positioned to secure long-term contracts and preferred-supplier status.
Lithium Bromide Market
For commercial players, the opportunity lies in building credibility around reliability. This can include strengthening regional supply options, improving inventory and logistics planning, and offering downstream customers clearer visibility into sourcing and handling practices. In a market where disruption risk is a meaningful cost driver, reliability can command preference even when base pricing is not the lowest.
Trend 2: Growth Will Accelerate in Specification-Sensitive and Specialty Applications
The next phase of market expansion is expected to lean increasingly on demand that requires higher purity, tighter controls, and stronger application support. Pharmaceutical synthesis, fine chemicals, and selected specialty industrial uses are natural beneficiaries of this shift, especially as manufacturing activity in major chemical-producing regions continues to expand. This trend favors suppliers and intermediaries that can provide consistent grades, technical collaboration, and responsive service rather than those operating purely as volume sellers.
Commercially, this suggests that revenue growth may be increasingly tied to value-added positioning. Companies that align product portfolios with specification needs, support customer qualification processes, and maintain strong quality systems can capture share in higher-margin segments. The broader implication is that bromine’s commercial relevance will depend not only on how much is produced, but on how effectively it is adapted to demanding downstream requirements.
Trend 3: Regional Divergence Will Shape Pricing, Risk, and Sourcing Strategy
Market participants should expect continued divergence between regions with stable, well-controlled production environments and those facing tighter regulatory or operational constraints. This divergence will influence not only price levels but also risk premiums, contract structures, and sourcing strategies. Buyers who depend on a single geography or a narrow supplier base may face greater exposure to localized disruptions or policy shifts, while those with flexible sourcing and regional alternatives can manage volatility more effectively.
Worldwide Bromobenzene Market
The strategic opportunity here is to treat geography as a risk-management variable rather than a background detail. For procurement teams, that may mean broadening supplier options, qualifying alternate sources, and aligning contract terms with continuity requirements. For producers and distributors, it may mean emphasizing regional stability, operational resilience, and service consistency as part of the commercial proposition.
Risks and Uncertainties to Watch
Several uncertainties could alter the pace or shape of these trends. Regulatory actions affecting brine operations may tighten further, creating additional constraints on production in certain regions. Geopolitical tensions and conflict-related disruptions can affect transport, feedstock access, and operating confidence, particularly where supply is concentrated. Demand could also evolve faster or slower than expected if substitution technologies advance in flame retardants or if energy-sector activity changes materially. Finally, quality and compliance expectations in pharmaceutical and specialty applications may rise, increasing the cost of entry for suppliers that cannot meet stricter requirements. These uncertainties do not cancel the market’s growth outlook; they make strategic preparedness essential.
Strategic Actions for Decision Makers
For Manufacturers and Producers
Position portfolios for both continuity and specialization. Core industrial demand provides a stable base, but long-term advantage will increasingly come from higher-purity grades, reliable derivative supply, and the technical support that specialty customers require. Invest in quality systems, application-facing expertise, and supply contingency planning so that operational resilience becomes part of the commercial offer. Where feasible, pursue partnerships or capacity alignment that strengthen regional feedstock access without over-concentrating risk in a single basin or operating environment.
For Investors and Strategic Capital Players
Focus on resilience and segmentation rather than aggregate volume alone. The market’s growth is real, but the most durable value creation is likely to come from players that can manage supply risk, meet specification-sensitive demand, and operate with disciplined compliance and cost control. Evaluate exposure to region-dependent brine operations, the ability to serve pharmaceutical and fine chemical pathways, and whether a company’s differentiation rests on credible operational and technical advantages. Capacity expansion financed through partnerships may offer a more balanced risk profile than isolated scale bets, particularly where feedstock concentration and regulatory sensitivity are high.
For Procurement and Supply Chain Leaders
Treat bromine sourcing as a continuity and quality strategy, not just a price optimization exercise. Diversify supplier options where possible, qualify alternate supply routes for critical applications, and align contract terms with the need for stable delivery and documented quality. Forspecification-driven use cases, prioritize suppliers with strong traceability, consistent purity, and proven regulatory readiness. Building flexibility into sourcing can reduce exposure to regional disruptions and help stabilize total cost of ownership, especially when international supply is subject to environmental or geopolitical shocks.
The bromine market is moving toward a phase where strategic positioning matters as much as raw market size. Success will depend on how well organizations anticipate supply vulnerability, regulatory evolution, and the shift toward higher-value applications. For decision makers who need more granular segmentation data, regional cost dynamics, and tailored scenario planning, a detailed market study can provide the deeper commercial context required to translate these trends into specific action plans.
For detailed analysis of this topic, please visit the official page: Bromine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


