



How Dental 3D Printer Market’s 6.98% CAGR and Orthodontics Boom Redefine Growth Beyond 2032

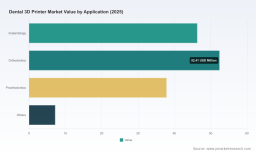
The Dental 3D Printer Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The dental 3D printing market has evolved from a niche prototyping tool into a core component of digital dentistry workflows. Valued at approximately 98.45 million USD in 2020, the sector reached 143.76 million USD by 2025, reflecting a compound annual growth rate of 6.98 percent through 2032. This trajectory is not merely a function of printer adoption; it signals a structural shift in how dental laboratories, clinics, and manufacturing partners approach restorations, surgical planning, and orthodontic appliances. The expansion is broad-based, yet concentrated enough that strategic positioning matters significantly for players navigating the next cycle.
Several inflection points define the current environment. First, the transition from laboratory-centric production to chairside and direct-clinical workflows is accelerating, but infrastructure readiness varies widely. Many practices are still integrating intraoral scanning, design software, and post-processing into cohesive pipelines, creating both friction and whitespace for integrated solutions. Second, material validation and regulatory clearance remain gatekeepers to clinical adoption. Not all resins or printing protocols achieve the mechanical, biocompatibility, or long-term performance thresholds required for permanent or semi-permanent restorations, which means technology adoption is often paced by regulatory milestones rather than hardware availability alone. Third, the industry is grappling with fragmentation in workflow compatibility. Printer manufacturers, material suppliers, design platforms, and milling or post-curing partners do not always align on open standards, creating integration costs that can slow decision-making for laboratories evaluating capital investment.
These challenges are not insurmountable, but they do shape where growth will materialize first. Markets that already support digital restoration reimbursement frameworks are seeing faster uptake, while regions still building clinical and laboratory digital literacy are likely to follow a more stepwise adoption curve. The implication for decision-makers is clear: the market's headline numbers mask uneven readiness across workflows, materials, and geographies, and the winners will be those who reduce integration friction while aligning with regulatory and clinical validation pathways.
Key Drivers Reshaping the Market
Technology Innovation and Material Advancements
Hardware innovation continues to raise the bar on speed, resolution, and repeatability, but the more consequential shifts are occurring in materials and process integration. High-precision stereolithography and digital light processing platforms are becoming more accessible, and the emergence of direct-print aligner systems and jetted denture solutions demonstrates that the industry is moving beyond models and temporary appliances toward permanent and semi-permanent restorative applications. The commercial availability of FDA-cleared resins for flexible removable partial dentures, alongside clearances for multi-material monolithic dentures and fixed hybrid dentures, illustrates how material science is expanding the clinical envelope. For manufacturers, these developments open new use cases; for laboratories and clinics, they reduce the need for multi-step hybrid workflows that combine printing with milling or manual fabrication.
Regulatory and Reimbursement Dynamics
Regulatory clearance is increasingly a bottleneck and a competitive moat. Several resin and system-level clearances in recent years have enabled broader clinical use cases, including temporary crowns, bridges, veneers, surgical guides, and certain denture applications. These approvals do more than validate safety and performance; they shape purchasing confidence and procurement cycles. When a material or workflow carries recognized clearance, laboratories and dental practices face fewer clinical and liability concerns, and procurement teams can justify capital expenditure with clearer clinical rationale. At the same time, reimbursement frameworks in leading markets are beginning to better accommodate digital restorations and appliance production, which strengthens the economic case for in-house or near-site production. The interplay between clearance velocity and reimbursement clarity will influence regional uptake patterns and the pace at which new applications move from pilot to routine use.
Demand-Side Behavioral Changes
Demand is being reshaped by both clinical expectations and operational economics. Patients and providers increasingly expect faster turnaround, improved fit, and more aesthetic outcomes, particularly in orthodontics and restorative cases. At the same time, dental laboratories and group practices are under pressure to manage labor constraints, reduce remake rates, and improve margin stability. Digital workflows that consolidate design, printing, and post-processing can address these pressures by standardizing outputs and reducing dependence on highly variable manual steps. The orthodontic segment, in particular, continues to show strong pull for aligner and appliance production, while implantology and prosthodontics are expanding as surgical guide and restoration workflows become more reproducible. The net effect is a demand environment that rewards speed, consistency, and clinical validation over novelty alone.
Supply Chain and Cost Structure Evolution
Cost structures are shifting as printer reliability improves, material libraries expand, and post-processing becomes more standardized. Lower total cost of ownership is enabling smaller laboratories and group practices to evaluate in-house production that previously made less economic sense. At the same time, supply chain considerations around material availability, resin formulation consistency, and servicing have become more salient. Buyers are increasingly sensitive not just to printer price but to the reliability of material supply, the breadth of validated materials, and the ease of workflow integration. This is tilting competitive advantage toward providers that can offer stable material portfolios, clear validation documentation, and support ecosystems that reduce downtime and rework.
Competitive Landscape and Leading Strategies
The competitive field blends established hardware and materials players with specialized dental-focused providers, each pursuing different angles of differentiation. Some competitors emphasize chairside accessibility and closed workflows tailored to clinical settings, while others focus on laboratory-grade precision, open material ecosystems, or multi-material capabilities for complex restorations. The divergence in strategy is intentional: dental 3D printing is not a single use case, and the companies gaining traction are those aligning their hardware, materials, and workflow support with specific clinical or laboratory priorities.
A notable pattern is the convergence of hardware, material validation, and workflow automation. Providers that can offer FDA-cleared resins for specific applications, paired with printers designed for those workflows, are positioned to reduce adoption friction. Systems that support direct-print aligner production or multi-material denture fabrication are expanding the addressable scope beyond models and temporaries. At the same time, companies with open material libraries are appealing to laboratories that value flexibility and the ability to test multiple formulations across different restoration types. The strategic lesson is that hardware specifications alone no longer define leadership; the combination of clearance readiness, material breadth, workflow integration, and support reliability now determines who can scale adoption in real clinical environments.
PW Consulting
Market concentration remains moderate, with the top three and top five players holding comparatively modest shares, indicating that the landscape is still accessible to focused entrants and that differentiation can be achieved through application-specific solutions rather than scale alone. However, consolidation dynamics are likely to intensify as larger players seek to broaden material portfolios, integrate design and post-processing, and strengthen regional support networks. New entrants that can demonstrate clear clinical value in a narrow application area may still carve out meaningful positions, but sustained advantage will increasingly depend on regulatory readiness, reproducibility, and the ability to fit into existing digital ecosystems.
Recent product launches and clearances underscore how quickly the application frontier is moving. Multi-material monolithic denture solutions and flexible removable partial denture resins have moved from development to commercial availability, signaling that the market is expanding into higher-value restorative and prosthetic use cases. These milestones matter because they change the conversation from "can we print it" to "can we print it with validated performance for a specific clinical indication." For competitors, that raises the stakes on material development, regulatory strategy, and clinical evidence generation.
Future Trends to Watch Over the Next 3 to 5 Years
One defining trend will be the continued expansion of printable, clinically validated applications. As material portfolios grow and more indications secure regulatory clearance, printing is likely to displace portions of workflows that previously relied on subtractive fabrication or manual layering. This expansion will not be uniform; it will concentrate first in applications where reproducibility, turnaround, and labor savings offer clear operational advantages. Manufacturers and laboratories that prepare for multi-application flexibility, rather than optimizing for a single workflow, will be better positioned to capture value as indications diversify.
A second trend is the deepening integration of design, printing, and post-processing into more automated, enterprise-ready workflows. The market is moving toward solutions that reduce hands-on steps, standardize output quality, and provide better traceability for clinical and quality assurance purposes. This is particularly relevant for group practices and larger laboratories seeking consistent outputs across multiple sites. The commercial opportunity lies in bundled workflows, training, and support models that reduce the operational burden of digital adoption, rather than selling hardware as a standalone commodity.
Metal 3D Printer Market
A third trend is regional divergence in adoption pace and reimbursement maturity. Markets with more advanced digital restoration reimbursement frameworks and established clinical digital infrastructure are likely to lead in volume and application breadth, while other regions will adopt more gradually as laboratory capabilities, clinician familiarity, and reimbursement clarity improve. For companies and investors, this means that go-to-market strategies should be calibrated to local workflow readiness and regulatory context rather than assuming a single global rollout curve. The uncertainty lies in how quickly reimbursement and clinical guidelines evolve, and whether material and workflow validation can keep pace with clinical demand in each region.
Dental CBCT Market
These trends intersect with a clear commercial opportunity: the market is transitioning from early adoption of models and temporary appliances toward broader restorative, surgical, and orthodontic production. That transition rewards players who can reduce integration complexity, offer validated materials for specific indications, and support customers through the change-management aspects of digital workflow adoption. The principal risk is over-indexing on hardware capability without sufficient attention to material validation, regulatory timing, and real-world workflow fit, which can slow adoption regardless of technical merit.
Strategic Actions for Decision-Makers
For Manufacturers and Workflow Providers
Focus investment on application-specific validation and workflow integration rather than broad, undifferentiated hardware portfolios. Clear regulatory positioning, robust material documentation, and reliable post-processing pathways will increasingly differentiate suppliers in a market where buyers weigh clinical confidence and operational stability alongside print quality. Consider where open versus closed material strategies create the most value for your target customer base, and build support models that reduce downtime and rework across multiple sites.
For Investors
Evaluate opportunities through the lens of application depth and workflow fit rather than headline printer volumes. Segments with stronger reimbursement alignment, higher labor savings, and clearer regulatory pathways are likely to scale faster. Pay attention to companies that combine material development, clearance strategy, and regional support capabilities, because those Attributes often determine whether a product moves from pilot to routine clinical use. Monitor consolidation signals and partnership activity, as ecosystem alignment is becoming a competitive differentiator.
For Procurement and Clinical Leaders
Approach capital decisions as workflow investments rather than equipment purchases. Assess total cost of ownership across material availability, validation coverage for your target indications, integration with existing design and scanning pipelines, and the reliability of service and training. Prioritize solutions that demonstrate clearance for the specific applications you intend to produce, and request evidence of consistent output quality and post-processing requirements before scaling volume. A phased rollout that validates workflow fit in a limited setting can reduce risk before committing to broader deployment.
The dental 3D printing market is entering a phase where clinical validation, workflow integration, and reimbursement alignment matter as much as print resolution. Decision-makers who align their strategies with these realities will be better positioned to capture the next wave of growth. For a more detailed view of segmentation dynamics, regional readiness, material and application trajectories, and company-level strategic positioning, the full research report provides deeper segmentation data and tailored recommendations to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Dental 3D Printer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


