



Slewing Bearings Market: Why 5.95% CAGR and Asia Pacific Demand Reshape Growth

The Slewing Bearings Market: Strategic Trends and Commercial Opportunities Through 2032
The slewing bearing market has evolved from a niche mechanical component sector into a critical enabler of industrial mobility, renewable energy infrastructure, and precision machinery. With global revenue climbing from approximately 331.45 million in 2020 to 438.27 million in 2025, the trajectory signals sustained expansion driven by capital-intensive infrastructure projects and technological maturation in heavy equipment. The forecast period through 2032 projects continued growth, approaching 652.66 million by the end of the decade, representing a compound annual growth rate of 5.95 percent. This expansion trajectory is not merely a function of population growth or broad industrial output; it reflects deliberate capital allocation toward higher-precision rotational systems that can withstand increasingly demanding operational environments.
Despite the positive momentum, the market is navigating a series of structural inflection points that will separate resilient operators from those reliant on legacy cost models. Fluctuating costs of specialty steel and rare earth elements have emerged as a persistent margin compression factor, forcing manufacturers to reconsider material sourcing strategies and engineering tolerances. At the same time, the competitive landscape remains moderately fragmented, with the top three manufacturers accounting for 24.6 percent of revenue and the top five reaching 32.1 percent. This concentration leaves ample room for both consolidation and niche specialization, depending on how companies position themselves along the value chain. Below, the structural dynamics shaping the slewing bearings market are examined through the lens of strategic decision-making.
Market Landscape and Core Challenges
The slewing bearing market has demonstrated consistent revenue growth over the historical period, with the pace accelerating notably as capital expenditures in renewable energy and heavy construction equipment gained traction. The 2025 base of 438.27 million serves as a foundation for the projected climb toward 652.66 million by 2032, a trajectory that implies steady year-over-year expansion rather than sudden spikes. This pattern reflects the capital-intensive nature of end-use sectors, where procurement cycles are long, specification requirements are rigorous, and replacement cycles are extended. The market's resilience during periods of broader industrial volatility underscores the relatively inelastic demand for high-load rotational components that are integral to project continuity.
One of the most significant challenges confronting manufacturers and end users alike is the volatility of raw material inputs. Slewing bearings are steel-intensive components, and fluctuations in alloy steel such as 42CrMo directly influence manufacturing costs and the fatigue life of the raceway. When specialty steel pricing shifts unpredictably, manufacturers face a difficult trade-off between absorbing costs to preserve customer relationships and passing increases through to a market that may already be sensitive to project budgets. This dynamic is particularly acute for producers serving multiple regions with varying procurement standards, as material substitution options are often limited by certification requirements and performance guarantees.
A second challenge lies in the regulatory environment, which is becoming more prescriptive across multiple jurisdictions. Standards such as ISO 16123:2025 now specify design, manufacture, and acceptance requirements for slewing bearings in marine cranes operating at ambient temperatures not lower than −40 °C. While such standards enhance safety and interoperability, they also raise the compliance burden for suppliers who must document design parameters, material traceability, and testing protocols with greater rigor. Simultaneously, the European Union has introduced new guidelines emphasizing reduced carbon footprints and enhanced recycling practices within bearing manufacturing processes. These requirements are reshaping procurement criteria, particularly for projects funded through public institutions or multinational operators with explicit sustainability mandates.
PW Consulting
A third structural challenge is the widening divergence between standardized commodity-grade products and highly customized engineered solutions. As end-use applications grow more specialized, the value proposition increasingly shifts toward tailored geometries, surface treatments, and integrated drive systems. Manufacturers that rely heavily on high-volume standard production may find margin erosion as customers migrate toward suppliers capable of delivering application-specific performance. Conversely, those that over-index on customization without disciplined cost control risk becoming uncompetitive for broader market segments.
Key Drivers Shaping Market Dynamics
Technology Innovation and Engineering Breakthroughs
The shift toward higher precision and greater load capacity continues to redefine product expectations. Manufacturers are investing in design methodologies that balance material efficiency with fatigue resistance, recognizing that even marginal improvements in raceway geometry or heat treatment can extend service life in demanding applications. Thin-section and slewing ring bearings have gained particular traction in sectors such as aerospace, robotics, and medical equipment, where spatial constraints and stringent performance criteria demand compact yet robust solutions.
Silverthin Bearing Group's release of a comprehensive catalog for thin section and slewing ring bearings in July 2025 illustrates this trend in practice. Targeting applications across space, aerospace, defense, robotics, medical, oil and gas, and semiconductor industries, the catalog reflects a deliberate move toward cross-industrial diversification. Rather than relying solely on traditional heavy machinery demand, the company is positioning precision slewing solutions as enablement components for high-value, technology-intensive sectors. This type of portfolio expansion signals a broader industry shift: slewing bearings are increasingly viewed not merely as mechanical parts but as engineered subsystems that influence the performance envelope of the equipment they support.
Policy and Regulatory Environments
Regulatory developments are reshaping both product specifications and procurement practices. The introduction of ISO 16123:2025 establishes clearer design and acceptance parameters for slewing bearings used in marine crane applications under extreme temperature conditions. This standard is likely to influence procurement requirements beyond marine environments, as operators in adjacent heavy-lift and offshore sectors adopt similar performance benchmarks to reduce risk across their equipment fleets.
At the same time, sustainability-oriented regulations are introducing new considerations into the manufacturing process. The European Union's emphasis on reduced carbon footprints and enhanced recycling practices is altering supplier evaluation criteria, particularly for OEMs and project developers with public sustainability commitments. For manufacturers, compliance is no longer a peripheral concern; it is becoming a competitive differentiator that can determine eligibility for certain contracts. Companies that proactively integrate material traceability, energy-efficient production methods, and end-of-life recycling pathways into their operations are better positioned to meet evolving procurement requirements.
Demand-Side Shifts in End-Use Sectors
Renewable energy remains a central driver of slewing bearing demand, as wind turbine installations and related infrastructure continue to expand globally. The rotational precision and durability required for turbine yaw and pitch systems make slewing bearings integral to long-term operational reliability. Construction and transit equipment also continues to contribute substantial demand, as excavators, cranes, and material handling systems rely on slewing components for controlled multi-directional movement. Mining operations, particularly in regions undergoing expanded extraction and processing investments, further reinforce demand for heavy-duty slewing solutions capable of withstanding abrasive environments and high-cyclic loading.
Beyond these established sectors, a gradual broadening of application scope is becoming evident. Precision slewing rings are increasingly integrated into automation systems, robotics platforms, and specialized industrial machinery where smooth torque transmission and compact form factors are critical. This diversification reduces dependence on any single end-use cycle and creates opportunities for suppliers who can adapt their engineering capabilities to smaller-volume, higher-specification orders.
Bearings Market
Supply Chain and Cost Structure Evolution
Material cost volatility remains a defining feature of the supply chain environment. The reliance on alloy steel and specialty materials means that manufacturing costs are closely tied to commodity markets that can shift rapidly in response to trade dynamics, production disruptions, and demand fluctuations across unrelated sectors. For slewing bearing producers, this translates into ongoing pressure to optimize material utilization, negotiate long-term supply agreements, or explore alternative formulations that maintain performance while mitigating price exposure.
External Tooth Slewing Bearing Market
The operational footprint of manufacturers is also evolving. thyssenkrupp rothe erde USA's announcement in May 2026 to consolidate operations in Aurora, relocating from Kentucky, illustrates a broader pattern of operational rationalization aimed at improving efficiency and reducing logistical complexity. Such moves are not purely cost-driven; they also reflect strategic decisions to align production capacity with key customer clusters and streamline engineering and service support. As supply chains continue to adjust, proximity to end markets and the ability to deliver integrated solutions, including drives and gears, will increasingly influence supplier selection.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of globally recognized engineering firms and specialized manufacturers with strong regional or application-specific positioning. SKF operates as a broad-line manufacturer of standard and customized slewing bearings with outside diameters ranging from 0.1 to 18 meters, giving it the capability to serve a wide spectrum of industrial applications. Kaydon Bearings has established a notable presence in wind energy applications, supplying slewing ring bearings and thin section bearings that align with the precision and reliability requirements of renewable energy infrastructure.
Thyssenkrupp Rothe Erde maintains a leadership position in large-diameter slewing bearings up to 25,000 millimeters, supported by facilities across Asia, Europe, and the Americas. This global footprint and specialization in very large components create a strong competitive moat in sectors such as heavy construction, mining, and industrial machinery where extreme load capacity is non-negotiable. Scheerer Bearing Corporation and SlewPro focus more intensively on high-quality slewing ring bearings, drives, and custom-engineered rings for OEM and U.S. industrial customers, emphasizing precision manufacturing and direct engineering collaboration.
In Europe, TGB Group and QCB provide slewing rings, drives, and thin section bearings across a broad diameter range, with QCB covering sizes from 100 millimeters to over 10,000 millimeters. Silverthin Bearing Group has carved out a distinct position in precision thin section and slewing ring bearings for aerospace, robotics, and industrial uses, reflecting a strategy oriented toward high-value niche applications rather than volume-driven heavy machinery.
In Asia, LDB Bearing and Fenghe Slewing Bearing represent the growing capability of Chinese manufacturers to serve heavy machinery, cranes, and OEM/ODM markets. Fenghe's positioning as a custom manufacturer capable of replacing SKF and Kaydon equivalents highlights the ongoing shift in cost-competitive sourcing options, particularly for applications where performance equivalence can be demonstrated and certification pathways are accessible. Xuzhou Wanda Slewing Bearing Co., Ltd.'s participation at CONEXPO-CON-AGG 2026 and LDB Bearing's exhibition at bauma CONEXPO INDIA 2026 further illustrate how manufacturers are using major trade events to strengthen visibility and build relationships within key end-use markets.
The strategic positioning within this landscape tends to fall into several distinct patterns. Large-diameter specialists leverage engineering depth and global service networks to defend high-load segments. Precision and thin-section players pursue diversification into high-technology sectors where specification rigor and customization create barriers to entry. Cost-competitive manufacturers expand their OEM and ODM footprint by offering functional equivalents to established Western brands, often backed by flexible production and growing certification capabilities.
Looking ahead, the market is likely to experience both consolidation and continued fragmentation, depending on segment and geography. In heavy-duty and large-diameter segments, scale advantages and integrated service offerings may encourage consolidation as customers seek reliable single-source partners for complex projects. In precision and specialized segments, fragmentation may persist as new applications emerge and smaller, agile suppliers develop domain expertise. The presence of multiple manufacturers investing in trade shows, catalogs, and operational consolidation suggests an industry in transition rather than one approaching maturity-driven stagnation.
Future Trends and Commercial Implications
Over the next three to five years, several trends are likely to shape the slewing bearings market in ways that directly influence commercial strategy. The first is the deepening integration of slewing bearings with drive systems and precision control components. As equipment designs become more compact and performance expectations rise, suppliers that can deliver coordinated bearing-plus-drive solutions will be better positioned to capture value at the subsystem level rather than competing solely on component pricing. This trend favors manufacturers with engineering capabilities that extend beyond the raceway and rolling elements into gearbox integration, lubrication management, and application-specific mounting configurations.
A second trend is the growing importance of compliance-driven differentiation. As standards become more detailed and sustainability requirements more explicit, suppliers that can provide documented traceability, validated operating envelopes, and environmentally aligned manufacturing practices will gain an advantage in procurement processes where risk mitigation and regulatory conformance carry significant weight. This does not mean every contract will hinge on sustainability credentials, but in sectors with public funding, multinational operators, or offshore and marine applications, the compliance profile of a supplier is increasingly part of the evaluation framework.
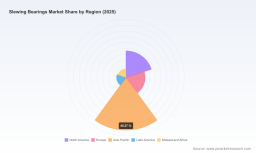
A third trend is geographic rebalancing of demand and production capacity. Asia Pacific remains a substantial revenue contributor, reflecting both industrial expansion and a growing base of regional OEMs and project developers. At the same time, trade show participation by Asian manufacturers in North American and Indian markets indicates a deliberate effort to build direct relationships and expand export-oriented sales channels. For established Western manufacturers, this creates opportunities to differentiate through advanced engineering, certified compliance, and integrated service, while also requiring vigilance regarding cost-competitive substitution in price-sensitive applications.
These trends translate into commercial opportunities for companies that align their product strategies with where value is shifting. Manufacturers that invest in precision-grade portfolios, integrated drive offerings, and documentation-ready compliance processes can access higher-margin segments. Procurement leaders that engage suppliers early in the specification process can optimize total cost of ownership by balancing upfront pricing against fatigue life, maintenance intervals, and regulatory alignment. Investors evaluating the sector should pay attention to manufacturers demonstrating both application diversification and operational efficiency, as these characteristics are likely to support resilience across procurement cycles.
Potential risks remain, particularly around raw material cost volatility and the pace at which regulatory requirements propagate across regions. If alloy steel and specialty material pricing remain unstable, margin management will continue to test operational discipline. If sustainability and performance standards diverge between regions, manufacturers serving multiple markets may face added complexity in maintaining compliant product lines without excessive cost overhead. These uncertainties do not negate the growth trajectory, but they do underscore the need for strategic flexibility and a clear view of where cost and compliance exposures are concentrated.
Strategic Actions for Decision Makers
For manufacturers and product leaders, the priority is to determine where to compete along the precision-versus-volume spectrum. A balanced approach may involve maintaining standardized offerings for high-volume industrial applications while building dedicated engineering capacity for thin-section, aerospace-adjacent, or integration-heavy applications. Supplier development should also account for material cost exposure, whether through long-term alloy sourcing agreements, design-for-manufacturability initiatives that reduce material waste, or alternative process investments that preserve fatigue performance under cost constraints. Participation in major industry events and proactive catalog or specification updates can strengthen visibility and shorten the sales cycle in markets where equipment builders are actively evaluating suppliers.
For investors and strategic planners, the focus should be on identifying operators with durable competitive advantages in the segments most likely to sustain margin integrity. Large-diameter specialists with global service networks, precision players with diversified high-technology exposure, and cost-competitive manufacturers with credible OEM/ODM relationships each represent distinct risk-return profiles. Evaluating these profiles requires attention to revenue mix, engineering capability, compliance readiness, and operational footprint decisions such as capacity consolidation or regional expansion. Companies that can demonstrate the ability to serve demanding specifications while managing material and regulatory exposure are better positioned to capture value as the market progresses toward the 2032 horizon.
For procurement and engineering leaders in end-use industries, the strategic imperative is to treat slewing bearing selection as a total-cost and risk-management decision rather than a transactional purchase. Engaging suppliers during the design phase can reveal trade-offs between standard catalog options and custom configurations, allowing project teams to weigh initial cost against service life, maintenance requirements, and compliance alignment. As standards such as ISO 16123:2025 and evolving sustainability guidelines become embedded in procurement expectations, supplier documentation and process transparency will become increasingly valuable in reducing downstream operational risk. Building a supplier base that includes both broad-capability and specialized partners can provide flexibility across different equipment classes and project constraints.
The slewing bearings market is moving along a growth path shaped by engineering sophistication, regulatory maturation, and broadening application scope. For decision makers who need detailed segmentation data, regional breakdowns, competitor benchmarking, and customized scenario analysis, a comprehensive research report can provide the granular evidence required to translate these strategic themes into operational plans. Access to that level of detail supports more precise capital allocation, supplier selection, and product roadmap decisions as the market continues its trajectory toward 2032.
For detailed analysis of this topic, please visit the official page: Slewing Bearings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


