



Treadmill Machines Market Outlook: Why the 6.8% CAGR Trajectory Reshapes Strategy

The Treadmill Machines Market: Strategic Shifts and Commercial Opportunities Through 2032
The global treadmill market has entered a phase of steady, compounding growth. Valued at approximately 80.0 million USD in 2020, the sector expanded to 101.0 million USD by 2025, translating into a compound annual growth rate of 6.8 percent for the 2020–2025 period. Forward projections extend through 2032, with revenue expected to approach 159.0 million USD. This trajectory reflects more than incremental demand; it signals a structural recalibration of how fitness equipment is designed, distributed, and integrated into daily routines. For manufacturers, investors, and procurement leaders, the treadmill segment now operates at the intersection of consumer health behavior, technological convergence, and supply chain recalibration. Understanding where value is created—and where margins are threatened—requires moving beyond headline growth figures and examining the underlying dynamics shaping competitive positioning.
Market Landscape and Structural Pressures
Size, Pace, and Concentration
The market’s progression from 80.0 million USD in 2020 to 159.0 million USD by 2032 indicates a maturing but still expanding category. Growth is not uniform across the decade; the acceleration from 2028 onward suggests that earlier adoption cycles are giving way to sustained replacement demand, commercial retrofitting, and emerging geographic penetration. The competitive field remains moderately concentrated, with the top three players capturing roughly 45 percent of revenue and the top five approaching 58 percent. This concentration does not imply a closed market; rather, it highlights the presence of established brands with durable channel relationships, service networks, and engineering reputations, alongside meaningful room for differentiated entrants who can align product architecture with specific use cases.
Key Challenges and Inflection Points
Three structural pressures are redefining how treadmill machines move through the market. First, spatial constraints in urban and apartment living are reshaping purchase logic. High-quality treadmills require substantial dedicated floor space, which acts as a persistent barrier for households in smaller residences. This constraint is pushing both product design and purchasing decisions toward compact footprints, foldable mechanisms, and multi-use home environments where equipment must coexist with living areas rather than dominate them.
Second, cost volatility and logistics friction are compressing margins and altering sourcing strategies. Tariff increases on imported steel and aluminum in mid-2025 triggered a sharp rise in shipping costs for household appliances, including a documented overcharge incident affecting a U.S.-based fitness equipment maker across 1,000 units of treadmills and stationary bikes manufactured in China. This episode underscores how commodity exposure, freight routing, and country-of-origin decisions can materially affect landed costs and pricing flexibility. Companies that rely on rigid supply chains without regional diversification or hedging strategies face greater vulnerability to these shocks.
Third, regulatory expectations are expanding beyond traditional safety and electrical standards. The European Union approved new regulations on the energy efficiency of fitness equipment with the aim of reducing energy consumption by 20 percent by 2030. At the same time, connected fitness equipment manufacturers face increasing regulatory demands relating to cybersecurity and personal data protection for EU market access, as demonstrated by recent cybersecurity certification activity in the sector. These requirements are not peripheral compliance items; they influence product architecture, software development cycles, documentation, and go-to-market timing, especially for brands seeking to scale across multiple regulatory jurisdictions.
Core Drivers Reshaping the Treadmill Category
Technological Innovation and Connected Functionality
Technology is shifting treadmills from mechanical exercise platforms to integrated wellness nodes. Incline and decline capabilities, shock-absorption engineering, and adaptive resistance curves have moved from premium niches into mainstream expectations. More importantly, connectivity is becoming a decisive differentiator. Interactive training, digital coaching, and seamless integration with broader fitness ecosystems are increasingly tied to purchase decisions and long-term retention. The launch of the Peloton Pro Series commercial equipment line, including the Tread+ Pro treadmill designed for hotels, residential gyms, and corporate wellness centers, illustrates how connected treadmill platforms are extending beyond individual home use into shared and institutional environments. This expansion creates new demand pools, but it also raises the bar for reliability, serviceability, and software continuity across diverse operating contexts.
PW Consulting Automotive & Machinery Research Center
Policy, Regulation, and Energy Efficiency
Policy developments are actively reshaping product roadmaps. The EU’s energy efficiency framework for fitness equipment signals a longer-term shift toward lower-power motors, improved standby management, and more efficient drive systems. Manufacturers that treat energy performance as a compliance afterthought risk rework costs and delayed market entry. Conversely, brands that design for efficiency from the outset can position efficiency as a commercial benefit, particularly in commercial facilities where equipment runs for extended hours and energy costs accumulate quickly. Regulatory momentum also intersects with data governance. As connected devices collect usage metrics and user preferences, cybersecurity and privacy expectations are becoming integral to market access rather than optional enhancements. The result is a dual pressure: hardware must be more efficient, and digital layers must be more secure and transparent.
Demand-Side Behavior and Use-Case Diversification
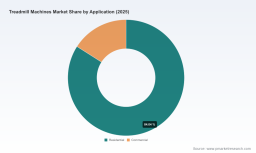
Consumer and institutional behavior continues to broaden the treadmill’s role. Home fitness demand remains anchored by convenience, but it is increasingly mediated by space limitations, budget sensitivity, and expectations for digital engagement. At the same time, commercial and institutional buyers are re-evaluating equipment portfolios in response to wellness programs, hospitality standards, and facility upgrades. Treadmills are being considered not only for traditional gym floors but also for corporate wellness centers, hotel fitness rooms, and multi-purpose residential gyms. This diversification changes the purchase criteria. Residential buyers may prioritize footprint, noise, and interactive features, while institutional buyers focus on durability, service contracts, throughput, and total cost of ownership. Recognizing that these are not identical markets—and that product strategies should not treat them as interchangeable—is essential for aligned forecasting and channel planning.
Worldwide Low Speed Rehabilitation Treadmill Market
Supply Chain and Cost Structure Reconfiguration
Supply chain reconfiguration is a central driver of margin and timing outcomes. Material costs for steel, aluminum, and electronics remain subject to geopolitical, trade, and logistics variables, while freight cost swings can rapidly alter the economics of imported equipment. This environment rewards manufacturers with flexible sourcing, regional production options, and disciplined inventory planning. It also rewards procurement teams that can negotiate with visibility into component exposure and lead-time risk. Beyond direct materials, the increasing importance of software, sensors, and connected services means that the cost structure is shifting from purely mechanical fabrication toward a blend of hardware engineering and digital development. Companies that can balance these cost pools without overinvesting in either direction will have a stronger competitive position as product complexity rises.
Competitive Landscape and Strategic Positioning
Established Leaders and Differentiated Playbooks
The competitive field includes companies with distinct positioning across commercial, residential, and hybrid use cases. Life Fitness designs and manufactures commercial and home treadmills, including the Club Series+ and Atmos models for gyms, fitness centers, and residential use. Its profile suggests a dual-market approach with emphasis on institutional credibility and home-grade accessibility. TRUE Fitness manufactures commercial-grade treadmills such as the Launch and Stryker series, serving gyms and fitness facilities, and operates as the largest privately held U.S. producer in this space. This positioning supports a focus on commercial durability, facility relationships, and long service cycles. SOLE Fitness produces durable home and light commercial treadmills, including the F80, F85, and TT8 series, with lifetime warranties on key components. This warranty-forward strategy reinforces a value proposition centered on longevity and reduced total cost of ownership for home and light commercial buyers.
Precor specializes in premium commercial treadmills with features such as the Breakaway slat-belt design, primarily for fitness facilities and health clubs. Its emphasis on specialized engineering for high-use environments points to a premium commercial niche where performance, user experience, and facility reputation matter. NordicTrack manufactures high-performance home treadmills such as the X16 and Commercial 1750/2450 series, known for incline technology and interactive training. Its commercial-labeled home lines indicate an effort to bridge commercial-grade features with residential adoption, particularly where interactive training and incline capability are central purchase drivers. Johnson Fitness & Wellness operates as a retailer and provider of treadmills manufactured by its parent Johnson Health Tech, including models from its Horizon Fitness subsidiary for home and commercial applications. This retail-plus-manufacturing structure highlights the role of channel reach, brand architecture, and multi-tier product distribution in capturing demand across segments.
Market Evolution: Consolidation, Segmentation, and New Entrants
Market evolution is not following a single path. Consolidation continues to reward brands with strong service networks, institutional contracts, and recognizable commercial reputations. At the same time, segmentation is intensifying. Treadmill offerings increasingly diverge by use environment, connectivity level, footprint, and durability class. This creates an opening for specialized players who can serve a well-defined buyer group more effectively than broad-line competitors. New entrants and adjacent brands are also entering through connected fitness, commercial hospitality packages, and home-first product designs. The presence of recent product expansions into corporate wellness and hospitality settings suggests that the category is extending beyond traditional gym and home boundaries. For incumbents, this means defending institutional relationships while keeping pace with digital and design expectations. For newer entrants, it means identifying a clear buyer profile, a defensible sourcing or software advantage, and a service model that can sustain the promise made at point of sale.
Forward Outlook: Three Trends Defining the Next Three to Five Years
Trend One: Space-Smart and Hybrid-Use Product Architectures
As urbanization and housing constraints persist, treadmill designs that minimize footprint without sacrificing stability, noise control, or user experience will gain share. Hybrid-use architectures—equipment that transitions cleanly between home, light commercial, and shared wellness environments—will become more relevant. This trend is not only a design challenge; it is a commercial one. Products that can serve multiple contexts with minimal compromise open broader addressable markets, but they also require careful engineering, clear positioning, and realistic warranty and service planning. The opportunity lies in creating equipment that fits real living and working environments rather than idealized exercise rooms.
Trend Two: Efficiency, Compliance, and Connected Security as Commercial Factors
Energy efficiency and data protection will increasingly act as market access conditions and competitive levers. The EU’s efficiency targets and the broader regulatory attention to cybersecurity are likely to influence specifications across regions, even where formal rules differ. Manufacturers that treat these requirements as design inputs rather than end-stage adjustments will reduce time-to-market risk and improve credibility with institutional buyers. For connected devices, cybersecurity and privacy readiness will become part of purchasing due diligence, especially in commercial and hospitality deployments where multiple users, multiple devices, and centralized management intersect. The commercial opportunity emerges for brands that can present efficiency and security as integrated product attributes, supported by clear documentation and certification where applicable.
Worldwide Leg Press Machines Market
Trend Three: Commercial and Institutional Channels as Growth Multipliers
While residential demand remains substantial, commercial and institutional deployments offer recurring value through volume purchasing, service contracts, and longer lifecycle relationships. Recent product activity targeting hotels, residential gyms, and corporate wellness environments indicates that treadmills are increasingly evaluated as part of broader experience and wellness strategies. This shifts the conversation from unit price to total cost of ownership, uptime, user retention, and brand alignment. The upside is meaningful for manufacturers that can build reliable commercial support, standardized procurement pathways, and equipment suited to high-traffic or multi-user settings. The risk is equally clear: overcommitting to residential-only designs limits exposure to these higher-volume, service-intensive opportunities, while premature commercial expansion without adequate service capacity can damage reputation and margins.
Actionable Guidance for Decision-Makers
For manufacturers, the immediate priority is aligning product architecture with the environments where treadmills are actually used. That means serious investment in compact and hybrid-use designs, disciplined energy and security engineering, and supply chain flexibility that reduces exposure to material and freight shocks. Brands should also separate residential and commercial strategies where buyer criteria diverge, rather than forcing a single narrative across all channels. Clear warranty terms, service readiness, and software continuity will matter as much as hardware specifications in differentiating against competing offerings.
For investors, the focus should be on identifying companies that demonstrate a coherent response to the market’s structural pressures. Indicators of resilience include diversified sourcing, credible commercial or hybrid-use positioning, and the ability to integrate connectivity without overpromising on software complexity. It is equally important to assess regulatory readiness and margin discipline in the face of tariff and commodity volatility. The most compelling opportunities are likely to appear where product differentiation is tied to real usage constraints—space, durability, efficiency, and data governance—rather than to superficial feature inflation.
For procurement and facility buyers, treadmill selection should be evaluated through total cost of ownership and operational fit. Residential buyers should weigh footprint, noise, and digital engagement against long-term durability expectations. Commercial and institutional buyers should prioritize service contracts, uptime, multi-user durability, and compliance documentation, especially where energy efficiency and cybersecurity requirements affect procurement eligibility. In both cases, purchasing decisions benefit from clearer visibility into warranty scope, service response times, and the realistic cost of ownership over the equipment’s intended lifecycle.
Conclusion
The treadmill machines market is expanding with measured momentum, but the most important developments are structural rather than purely quantitative. Spatial constraints, material and logistics volatility, energy and cybersecurity expectations, and the broadening of use cases are redefining what buyers value and how manufacturers must compete. Companies that align product design, supply chain strategy, and channel focus with these realities are better positioned to capture durable demand across residential and commercial environments. As the category moves toward 2032, the winners will be those who treat treadmills not as isolated exercise hardware, but as integrated components of space-constrained homes, high-usage facilities, and connected wellness ecosystems.
For decision-makers seeking deeper segmentation data, regional demand patterns, and customized strategic recommendations, a comprehensive analysis of the treadmill machines market provides the next layer of detail needed to translate these market-level insights into specific product, sourcing, and investment choices. Readers interested in that level of granularity can consult the full PW Consulting report on the treadmill machines market for a more detailed breakdown of demand drivers, competitive positioning, and actionable next steps tailored to specific business objectives.
For detailed analysis of this topic, please visit the official page: Treadmill Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


