



Home Appliances Market: How 6.98% CAGR and Regional Shifts Redefine Growth Through 2032

Navigating the Home Appliances Market: Strategic Trends and Commercial Opportunities Through 2032
The global home appliances market has entered a phase of sustained expansion, reflecting deep structural shifts in how households and commercial enterprises consume, manage, and upgrade essential equipment. From 2020 through the base year of 2025, the sector demonstrated consistent upward momentum, with revenues climbing steadily as consumption patterns evolved and product categories matured. Current market size figures sit at 938.5 million USD, and forward projections indicate the base year will be followed by continued compound annual growth averaging 6.98 percent through the 2026 to 2032 forecast horizon. By the close of that period, revenues are expected to reach 1,495.2 million USD. This trajectory is not merely a function of population growth or replacement cycles. It reflects a convergence of technological advancement, regulatory recalibration, supply chain repositioning, and shifting consumer expectations that together reshape competitive dynamics and redefine where value is created.
For executives, strategists, and investors evaluating the home appliances sector, the headline growth rates tell only part of the story. The more consequential questions revolve around which segments will capture disproportionate share, how regulatory and trade environments will alter cost structures and sourcing strategies, and what operational or partnership models will separate resilient operators from those exposed to margin compression. Understanding these dynamics requires moving beyond aggregate figures and examining the forces that are actively redirecting capital, innovation, and market positioning across the industry.
Market Snapshot and Core Challenges
The home appliances market has grown from 743.2 million USD in 2020 to a base year valuation of 938.5 million USD, with the pathway from 2021 through 2024 showing steady annual increases that reflect both recovering post-pandemic demand and gradual upgrades in product portfolios. The forecast period from 2026 onward projects a market expanding to 979.21 million USD, then accelerating through subsequent years to reach 1,495.2 million USD by 2032. This growth cadence suggests that demand is broadening rather than merely rebounding, with new product categories, connectivity features, and commercial applications contributing incremental revenue streams alongside traditional residential replacements.
Beneath these aggregate trends, several structural challenges and inflection points are reshaping how companies plan for the coming years. The first is the intensifying friction between trade policy and manufacturing economics. Recent tariff adjustments on steel and aluminum imports, along with derivative duties affecting certain non-electric domestic cooking appliances, stoves, ranges, and washing machines, have introduced new cost volatility. Import volumes face downward pressure while domestic production costs rise, forcing manufacturers to weigh localized assembly against margin preservation. The second challenge lies in product safety and compliance risk. Regulatory warnings and recalls across categories such as small room tower heaters, steam cleaners, and hair dryers underscore the scrutiny facing manufacturers as appliance functionality becomes more electrified and digitally integrated. Failure to anticipate compliance requirements or to maintain rigorous quality controls can disrupt product pipelines and erode consumer confidence. The third inflection point is the widening divergence between traditional mechanical appliance performance and the expectations set by connected, AI-assisted, and energy-responsive products. Companies that treat smart features as additive accessories rather than core design parameters risk ceding premium positioning to competitors who embed intelligence into user workflows and service ecosystems from the outset.
Key Growth Drivers
Technological innovation continues to be the most visible engine of differentiation. Advances in kitchen automation, personalized guidance features, and cordless cleaning technologies illustrate how manufacturers are translating computational capability into tangible user benefits. Recent product introductions have showcased AI-driven cooking assistance integrated into connected home ecosystems, alongside premium cordless stick vacuums leveraging advanced filtration and micro-cleaning mechanisms. These launches signal a broader shift from standalone appliance functionality toward integrated experiences that reduce friction in daily routines and provide actionable feedback on usage patterns. The commercial implication is clear: differentiation increasingly depends on software architecture, sensor integration, and post-purchase service models as much as on mechanical durability or energy efficiency ratings.
Policy and regulatory environments are simultaneously reshaping cost structures and competitive boundaries. Tariff frameworks targeting steel, aluminum, and derivative articles have introduced meaningful uncertainty into sourcing strategies. The expansion of tariff inclusions to cover additional derivative appliances, portable non-electric cooking devices, and related components means that import-dependent supply chains face both direct duty exposure and indirect cost pass-through effects. At the same time, regulatory bodies are heightening safety expectations across multiple categories, reinforcing the need for proactive compliance management. For manufacturers with significant cross-border component flows, the strategic response involves mapping exposure across the bill of materials, evaluating domestic or near-shore production alternatives, and aligning product design with evolving tariff classifications to avoid unintended duty escalation.
On the demand side, consumer and commercial behavior alike are shifting toward efficiency, convenience, and resilience. Households are prioritizing appliances that reduce energy consumption, simplify maintenance, and integrate smoothly with broader smart home environments. The appetite for connected functionality is no longer confined to premium niches; it is expanding as users become more comfortable with app-based controls and automated scheduling. Commercial buyers, meanwhile, are evaluating appliances through the lens of operational continuity, compliance, and total cost of ownership rather than sticker price alone. This dual pressure pushes manufacturers to design products that perform reliably under varied usage patterns while providing data that supports predictive maintenance, service optimization, and energy management.
Supply chain and cost structure dynamics complete the driver set. Component availability, freight volatility, and regional manufacturing capacity all influence how quickly companies can scale new models or adjust to regulatory shifts. Investments in U.S. manufacturing expansion, including commitments exceeding 3 billion USD over a five-year horizon, highlight the strategic priority of domestic capability for certain product lines, including vertical zoneline air conditioners and demand-response electric water heaters. Such capital deployment does more than mitigate tariff risk; it positions companies to respond faster to localized demand, adapt product specifications to market-specific requirements, and reduce dependency on long, multi-tier logistics networks. The broader implication is that supply chain resilience is increasingly a competitive attribute rather than a back-office operational concern.
Worldwide Energy-efficient Household Appliance Market
Competitive Landscape and Leading Strategies
The market remains moderately concentrated, with a small group of large incumbents commanding a substantial share of revenues. This concentration creates a landscape where scale advantages in procurement, distribution, and brand recognition coexist with intense competition on product innovation and regional positioning. Leading players span major appliance specialists, diversified consumer electronics groups, and premium brand portfolios, each pursuing a distinct strategic emphasis. Some companies lean on broad brand families and deep installed bases in core categories such as refrigerators, washers, dryers, and ranges. Others differentiate through premium engineering, ecosystem integration, and brand equity in high-end segments. Chinese manufacturers continue to expand their global footprints, combining scale production with increasingly sophisticated feature sets and aggressive geographic diversification.
Recent developments illustrate how these companies are attempting to tilt the competitive balance. A premium appliance group launched an AI-driven kitchen guidance feature within a connected home application and introduced new cordless stick vacuums with advanced cleaning technology for the North American market. These moves reflect a focus on post-purchase engagement and differentiated cleaning performance, areas where incremental improvements can strengthen brand loyalty and support premium pricing. Another major domestic manufacturer announced a collaboration centered on specialty baking equipment, signaling a willingness to target niche usage patterns with tailored solutions and co-branded partnerships that elevate category relevance. The same company also disclosed a large multi-year investment program to expand U.S. manufacturing capacity, explicitly tied to air conditioning and demand-response water heater models that align with energy and grid-interaction trends. A separate strategic partnership between a European appliance group and a large Chinese manufacturer aims to accelerate growth and innovation in North America, illustrating how cross-border alliances are being used to combine engineering capabilities, scale, and regional market access.
These actions point to several evolving dynamics. Consolidation and partnership activity are increasing as companies seek to pool technology, share development costs, and access distribution pathways that would be slower to build organically. At the same time, segmentation is sharpening: premium brands are doubling down on connected experiences and specialized performance, while scale manufacturers are optimizing cost structures and expanding into adjacent categories. New entrants and niche innovators are finding opportunities not by challenging incumbents across the entire product spectrum, but by targeting specific workflows, unmet consumer preferences, or commercial applications where incumbent portfolios are less dense. The strategic question for incumbents is whether they can sustain differentiation as feature sets converge and as tariffs and compliance costs reshape the economics of global sourcing.
Forward-Looking Trends and Commercial Implications
One of the most consequential trends over the next three to five years is the deepening integration of intelligence and connectivity into mainstream appliance portfolios. AI-assisted guidance, usage personalization, and ecosystem interoperability are moving from premium differentiators to expected baseline features in key categories. The commercial opportunity lies in designing products where software and sensors create measurable improvements in cooking precision, laundry efficiency, cleaning performance, or energy management, and in building service models that leverage device data for predictive maintenance and customer retention. The risk is that intelligence becomes a commodity if multiple competitors adopt similar platforms without meaningful differentiation in user experience or service reliability.
Worldwide Domestic Appliances Market
A second trend is the reconfiguration of trade, sourcing, and manufacturing footprints in response to tariff and compliance pressures. As duties on steel, aluminum, and derivative articles affect cost structures, companies will continue to evaluate localized production, supplier diversification, and design adjustments that reduce exposure to tariff classifications. This creates opportunities for manufacturers with flexible production networks and for suppliers positioned in regions that benefit from trade realignment. The uncertainty to monitor is the pace and scope of future policy adjustments; abrupt changes can disrupt sourcing plans, alter margin assumptions, and shift the relative attractiveness of import-based versus domestic assembly models.
A third trend is the expansion of commercial and specialty applications as growth contributors. Demand-response electric water heaters, vertical zoneline air conditioners, and niche baking or cleaning solutions indicate that appliances are increasingly evaluated for their role in broader energy systems, operational efficiency, and targeted consumer experiences. Companies that can align product design with grid-interactive capabilities, commercial compliance requirements, or specific user workflows stand to capture value beyond traditional replacement cycles. The counter-risk is execution complexity: commercial specifications, certification demands, and service expectations can differ sharply from residential models, and misjudging these requirements can lead to costly market-entry setbacks.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to treat connectivity, compliance, and sourcing strategy as integrated design constraints rather than separate workstreams. Product roadmaps should account for tariff exposure across derivative components, embed intelligence that delivers measurable user value, and align manufacturing footprints with the markets where demand and policy dynamics are most volatile. Building post-purchase engagement through data-driven service, personalized guidance, and ecosystem interoperability can strengthen retention and support premium positioning. At the same time, quality and safety controls must be calibrated to heightened regulatory scrutiny, particularly in categories with elevated recall or hazard risk.
For investors, the focus should be on identifying companies with durable differentiation in a market where concentration is high and feature convergence is accelerating. Favor operators that demonstrate credible pathways to margin resilience under shifting tariff regimes, that invest in domestic or near-shore capacity where it aligns with demand and policy trends, and that can translate smart features into service-based revenue or stronger brand loyalty. Pay close attention to partnership structures and cross-border alliances, as these can accelerate access to technology and regional markets but also introduce integration and execution risk. Monitor recall patterns and safety compliance as leading indicators of operational discipline and reputational exposure.
For procurement and commercial buyers, the emphasis should shift from unit cost to total cost of ownership, energy performance, compliance assurance, and service responsiveness. Appliances that support demand-response capabilities, reduce maintenance downtime, and integrate cleanly into existing operational or smart home environments can deliver value that outweighs initial price premiums. Vendor evaluation should include assessments of manufacturing resilience, sourcing transparency, and readiness to adapt to evolving regulatory requirements, particularly where procurement volumes make tariff exposure and recall risk material.
PW Consulting Health Care Research Center
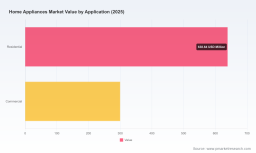
The home appliances market is evolving along multiple fronts simultaneously: technology is reshaping user expectations, policy and trade frameworks are altering cost and sourcing logic, and demand is broadening across residential, commercial, and specialty applications. Navigating this environment requires granular insight into segment dynamics, regional exposures, competitive moves, and the operational implications of regulatory change. Detailed breakdowns of segmentation, regional trajectories, competitive benchmarking, and scenario analysis are available through the full market research report, where deeper data and tailored recommendations can support planning for specific categories, geographies, and strategic objectives.
For detailed analysis of this topic, please visit the official page: Home Appliances Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


