



Crude Heparin Market: How 7.47% CAGR and Surgical Demand Reshape Industry Profits

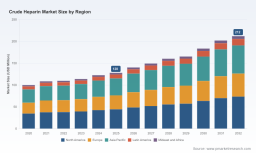
Navigating the Crude Heparin Market: Strategic Trends and Commercial Opportunities (2026–2032)
The global crude heparin market has entered a period of measured but steady expansion, with revenue projected to climb from 128.0 million USD in 2025 to 212.0 million USD by 2032, sustained by a compound annual growth rate of 7.47 percent. This trajectory reflects a market that is simultaneously maturing and reconfiguring. Demand anchored in cardiovascular applications and surgical procedures continues to provide a reliable base, while supply-side dynamics, regulatory scrutiny, and geographic rebalancing introduce new layers of complexity. For executives, investors, and procurement leaders, the central question is no longer whether the market will grow, but how participants can position themselves to capture value amid shifting competitive and compliance landscapes.
Market Snapshot and Structural Realities
The current market size of 128.0 million USD in 2025 represents more than incremental growth; it signals a market that has absorbed years of consolidation, quality standardization, and regional capacity adjustments. Over the historical window from 2020 through 2025, revenue moved from 100.0 million USD to its present level, reflecting resilience despite periodic supply interruptions and evolving regulatory expectations. Looking ahead, the forecast window from 2026 through 2032 points toward a consistent upward path, with annual figures crossing 140.32 million USD in 2026 and reaching 212.0 million USD in 2032.
A defining structural feature of this market is its fragmentation. The top three players account for roughly 24.5 percent of revenue, and the top five capture approximately 29.8 percent. Such concentration levels indicate that no single entity dominates the value chain outright, leaving room for regional specialists, vertically integrated producers, and downstream consumers to exert meaningful influence. This fragmented structure also means that differentiation tends to emerge through operational reliability, traceability credentials, and the ability to meet stringent quality requirements rather than through sheer scale alone.
Beyond the headline numbers, the market is navigating a series of inflection points. First, geographic demand is increasingly dispersed, with multiple regions contributing materially to overall volume and revenue. This dispersion complicates supply planning but also creates opportunities for producers with flexible sourcing and multi-region distribution capabilities. Second, the raw material base remains heavily tied to porcine intestinal mucosa, which continues to dominate global crude heparin output because of its high yield and comparatively lower disease transmission risk. That dependence creates efficiency advantages but also exposes the market to animal health disruptions that can ripple through supply availability. Third, the interplay between volume growth and regulatory stringency is tightening. Compliance is no longer a back-office function; it has become a commercial differentiator that influences procurement decisions, partnership formation, and market access.
For decision-makers, these structural realities translate into a simple imperative: growth will accrue to participants who can align capacity, quality assurance, and geographic agility while maintaining cost discipline. Operators and buyers alike need to treat crude heparin not as a commodity input but as a strategically managed resource with compliance, continuity, and traceability as core value drivers.
Key Drivers Shaping the Market
Several interlocking forces are propelling the crude heparin market forward while simultaneously reshaping how participants compete.
- Technological innovation and manufacturing precision are raising the bar for quality and consistency. Advances in extraction, purification, and analytical verification are helping producers standardize output across batches, reduce variability, and support downstream conversion into active pharmaceutical ingredients and low molecular weight heparin. These improvements matter because reproducibility directly affects supplier qualification, regulatory confidence, and ultimately commercial reliability.
- Regulatory and policy dynamics are redefining acceptable sourcing and documentation practices. Recent updates to heparin importation rules require specific analytical data, including species origin and contaminant testing for every shipment of crude heparin. Alongside this, active guidance on monitoring crude heparin for oversulfated chondroitin sulfate and ruminant material contaminants has reinforced the need for mandatory supplier qualification and lot testing. The practical effect is clear: documentation, traceability, and analytical rigor now function as market entry requirements rather than supplementary best practices.
- Demand-side behavior is becoming more risk-aware and procurement-disciplined. Cardiovascular applications remain a substantial and steady anchor for consumption, while surgical procedures provide additional procedural demand. At the same time, procurement teams are increasingly prioritizing supply continuity, validated quality records, and multi-source resilience over spot pricing alone. This shift is encouraging longer-term supplier relationships and more rigorous qualification processes.
- Supply chain and cost structures are being tested by animal health dynamics and regional capacity conditions. Industry reporting has highlighted ongoing outbreaks affecting a significant share of the global crude heparin supply associated with Chinese production, underscoring how animal disease can create bottlenecks and prompt buyers to diversify sourcing. At the same time, producers with vertically coordinated operations and established traceability are better positioned to absorb volatility and maintain reliable delivery.
These drivers are not operating in isolation. Innovation improves the ability to meet regulatory expectations; regulation raises the value of traceable sourcing; demand-side caution rewards continuity; and supply-side risks make diversification and integrated operations more commercially attractive. The net result is a market in which reliability and transparency are becoming as important as volume and price.
Competitive Landscape and Leading Strategies
The competitive field is defined by players with distinct strategic stances, each aligning capabilities to different parts of the value chain. Understanding these positions makes it easier to anticipate where partnerships, capacity investments, and procurement decisions are likely to flow.
Strategic Positioning of Key Players
Bioiberica has built a reputation around heparin molecule production, commercialization, and research, with an international footprint spanning multiple production sites. Its emphasis on pharmaceutical-grade crude porcine heparin for active pharmaceutical ingredients and low molecular weight heparin reflects a strategy oriented toward quality consistency and lifecycle engagement with the molecule. Participation in major industry events to mark corporate milestones and unveil refreshed branding suggests an ongoing effort to reinforce visibility and credibility within the pharmaceutical supply community.
Darling Ingredients, through its heparin operations, has focused on fully traceable crude porcine heparin extracted from hydrolyzed mucosa for pharmaceutical use as starting material for active pharmaceutical ingredients and low molecular weight heparin. Traceability is not merely a compliance checkbox here; it functions as a strategic asset that supports qualification, risk management, and buyer confidence. The company’s emphasis on profitable growth through strategic planning, including discussions of its heparin operations at investor events, signals an intent to treat heparin as a value-creating segment within a broader ingredients portfolio rather than a standalone volume play.
Shenzhen Hepalink operates as a multinational pharmaceutical company with a clear focus on heparin sodium active pharmaceutical ingredient and enoxaparin sodium active pharmaceutical ingredient production from crude sources. Its continued emphasis on these product lines through interim reporting indicates a strategy anchored in downstream conversion and product-level execution. By concentrating on active pharmaceutical ingredients, the company aligns itself with the value-added stages of the chain, where differentiation often depends on process control, regulatory standing, and consistent supply to formulation and finished-product markets.
Heparin Market
Hebei Changshan Biochemical Pharmaceutical specializes in research, development, production, and sales of heparin sodium active pharmaceutical ingredient and low molecular weight heparin, with a complete industrial chain extending from crude heparin products. Vertical integration across the chain can provide advantages in cost management, quality oversight, and responsiveness to demand fluctuations. Inclusion in recognized stock exchange indices has also drawn attention to the company, illustrating how market recognition and financial visibility can complement operational strategy in a fragmented competitive field.
Sanofi represents a different role in the landscape as a major consumer of crude heparin for low molecular weight heparin production, notably within its Clexane franchise and broader anticoagulant portfolio. For large downstream users, the crude heparin market is less about producing the molecule and more about securing dependable inputs that support branded and portfolio-level commercial commitments. This consumer-side perspective matters because major buyers can influence supplier qualification standards, specification expectations, and long-term supply commitments.
How the Landscape Is Evolving
The market is undergoing a nuanced evolution rather than a simple consolidation wave. On one hand, traceability, documentation maturity, and quality assurance are raising barriers for suppliers that cannot meet increasingly rigorous expectations. On the other hand, the relatively modest concentration levels leave space for regional specialists and integrated players to compete on operational excellence rather than market dominance alone. This environment favors strategies that combine reliable capacity, regulatory readiness, and transparent sourcing. It also creates openings for partnership models in which producers and downstream users align on qualification, continuity, and product-specific requirements.
PW Consulting
For investors and executives, the practical takeaway is that competitive advantage in this market is increasingly multidimensional. Scale matters, but so do traceability systems, animal-health risk management, analytical compliance, and the ability to serve downstream conversion with consistency. Companies that can demonstrate these attributes are better positioned to secure long-term relationships and withstand disruption.
Forward-Looking Trends and Commercial Opportunities
Looking ahead three to five years, several trends are likely to shape how value is created and captured in the crude heparin market.
- Regulatory and quality requirements will continue to deepen as standard practice. Importation rules requiring species-origin and contaminant data, together with ongoing guidance on oversulfated chondroitin sulfate and ruminant contaminant monitoring, point toward a future in which analytical documentation is integrated into commercial workflows rather than treated as a periodic checkpoint. Producers and suppliers that can deliver standardized, verifiable data with each shipment will strengthen their qualification standing and reduce friction in procurement cycles.
- Geographic diversification and supply resilience will become more prominent in sourcing strategies. Animal health disruptions affecting a large share of supply associated with Chinese production have reinforced the importance of not concentrating sourcing too narrowly. Over the forecast period, buyers and producers alike are likely to place greater value on multi-region capability, flexible logistics, and contingency planning. This trend favors operators with diversified sourcing, transparent traceability, and the ability to maintain continuity when regional conditions shift.
- Downstream alignment and product-focused value creation will gain importance. Because cardiovascular applications and surgical procedures provide a durable demand base, participants that connect crude heparin supply more tightly to downstream active pharmaceutical ingredient and low molecular weight heparin production can capture more stable demand relationships. Vertical integration, long-term supply agreements, and product-specific quality alignment are likely to be rewarded as buyers seek to reduce variability and protect continuity for essential anticoagulants.
These trends create commercial opportunities for operators that can combine reliable production with compliance maturity and geographic flexibility. There is also opportunity in supplier qualification services, documentation systems, and analytical capabilities that help market participants demonstrate species origin, contaminant controls, and lot-level consistency. For downstream consumers, the opportunity lies in building qualified multi-source networks that reduce concentration risk without sacrificing quality or cost efficiency.
Risks and Uncertainties to Monitor
Despite the constructive growth path, several uncertainties warrant attention. Animal health events remain a persistent risk factor because of the market’s reliance on porcine intestinal mucosa. Regulatory expectations can evolve further, increasing documentation and testing burdens or adjusting qualification requirements. Concentration risk persists where sourcing is overly narrow, while over-diversification without strong quality assurance can introduce new variability. Currency and cost dynamics, regional capacity adjustments, and the pace of downstream demand growth can also influence margins and availability. Participants should treat these factors as variables to manage actively rather than external conditions to simply accept.
Strategic Actions for Decision-Makers
The current market environment rewards deliberate, differentiated action rather than passive participation. The right moves depend on a company’s position in the value chain, but several priorities apply broadly.
- For manufacturers and producers, investment in traceability, analytical documentation, and multi-region sourcing flexibility should be treated as core commercial capabilities. Aligning production with verifiable species-origin data, contaminant testing, and lot-level quality records can strengthen supplier qualification outcomes and improve resilience during regulatory or supply disruptions. Where feasible, vertical coordination or strategic partnerships that link crude heparin output to downstream active pharmaceutical ingredient and low molecular weight heparin needs can create more stable demand relationships and reduce exposure to spot-market volatility.
- For investors, the market’s fragmented structure and moderately concentrated leadership field suggest that value can be created through operational differentiation, compliance maturity, and disciplined growth planning rather than through scale alone. Emphasis on companies with transparent traceability, validated quality systems, and credible strategies for managing animal-health and supply continuity risks may align with the market’s evolving requirements. At the same time, monitoring how major downstream consumers structure sourcing and qualification can provide early signals about where supply relationships are heading.
- For procurement and supply chain leaders, the priority is to balance cost, continuity, and compliance in a way that reflects the market’s risk profile. Qualifying multiple suppliers, verifying documentation standards, and building contingency plans around animal-health and regulatory developments can reduce exposure to disruption. It is also important to treat supplier qualification as an ongoing process, given that importation rules and guidance on contaminants continue to shape acceptable sourcing practices. Long-term partnerships with suppliers that can demonstrate consistent analytical data and reliable delivery may offer more commercial stability than short-term price optimization alone.
Across these roles, the common thread is that crude heparin is increasingly evaluated through a lens that combines quality assurance, traceability, and continuity with traditional commercial considerations. Companies that internalize this lens are better positioned to navigate the forecast growth path from 128.0 million USD in 2025 toward 212.0 million USD by 2032 while managing the operational and regulatory risks that accompany it.
For decision-makers seeking a more detailed view of regional and application-level dynamics, sourcing patterns, and company-specific strategic paths, the full PW Consulting research report provides deeper segment data and tailored recommendations. It is designed to support scenario planning, supplier evaluation, and investment prioritization with the granularity required for operational and strategic decisions.
Heparin Sodium Market
For detailed analysis of this topic, please visit the official page: Crude Heparin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


