



MOF Market 2026: Beyond the 20.6% CAGR—Shifting Demand & Regional Dynamics

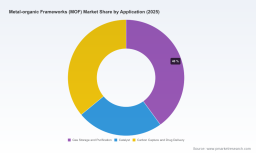
The Metal-Organic Frameworks Market: Strategic Trajectories and Commercial Opportunities
The metal-organic frameworks (MOFs) market has transitioned from laboratory curiosity to industrial relevance at a pace that few materials markets have matched. Over the past half-decade, commercial activity has shifted decisively from gram-scale research supply toward multi-ton production runs, signaling that the inflection point between pilot validation and commercial deployment has arrived. Market revenue expanded from $0.65 billion in 2020 to $1.25 billion in 2025, and forward projections track sustained momentum through 2032, with expected revenue reaching $4.68 billion. The compound annual growth rate of 20.6 percent across the 2026 to 2032 forecast window reflects not merely incremental adoption but a structural reordering of how separation, storage, and purification functions are engineered across industrial value chains.
This growth trajectory helps explain why executives and investors are paying closer attention to MOFs. The materials class offers tunable pore architectures, high surface-area-to-volume ratios, and chemical specificity that conventional adsorbents struggle to replicate. Yet scale-up has historically been the binding constraint. The market is now demonstrating that manufacturing pathways are maturing quickly enough to support industrial demand, particularly in carbon capture, gas purification, and selective catalysis. Understanding where the market stands, what is driving it, and how competitive positioning is evolving provides a practical basis for strategic planning.
PW Consulting
Market Landscape: Growth Context and Core Challenges
The MOF market's expansion over 2020 to 2025 reflects a compound effect of technology readiness, commercialization activity, and rising demand from applications where selectivity and energy efficiency carry direct economic value. Revenue grew from $0.65 billion to $1.25 billion across that period, with the 2025 base year setting up a forecast period in which demand scales rapidly. The forward path suggests that by 2032, annual market revenue could approach $4.68 billion, implying that the later years of the forecast period will be defined by broader commercial adoption rather than early-stage experimentation.
This trajectory is meaningful because it points to a market that is no longer constrained primarily by scientific promise, but by manufacturing economics, application validation, and integration into existing industrial processes. That shift changes the strategic question for decision-makers. The issue is no longer whether MOFs can perform; it is whether companies can produce them consistently, cost-effectively, and at volumes that match operational requirements.
Scaling Production Without Compromising Performance
One of the most important challenges in the market has been moving from batch synthesis to continuous or semi-continuous manufacturing while preserving material consistency. MOF performance depends heavily on crystallinity, pore uniformity, and functionalization quality. In research environments, these attributes can be controlled with precision, but industrial-scale production introduces variability that can affect adsorption capacity, cycle stability, and downstream integration. The challenge is not simply producing more material; it is producing more material that behaves predictably under real operating conditions.
This matters because industrial buyers are unlikely to adopt materials that require extensive re-validation for every batch. For market participants, the strategic implication is clear: process control, quality assurance, and reproducible synthesis are becoming as important as the chemistry itself. Companies that can demonstrate repeatable performance at scale are positioned to capture commercial demand more effectively than those that rely on promising lab results alone.
Application-Specific Validation and Integration Risk
MOFs are not a single product category; they are a materials platform that must be matched to specific separation, storage, or catalytic requirements. That flexibility is an advantage, but it also creates a validation burden. End users need evidence that a particular MOF formulation will perform in their operating environment, often under cyclic conditions, exposure to impurities, and long-term thermal or pressure stress. For gas storage and purification, for example, performance expectations extend beyond capacity to include regeneration energy, lifetime durability, and compatibility with existing process equipment.
The commercial consequence is that adoption cycles can lengthen even when the materials are technically capable. Buyers may require pilot testing, on-site verification, or multi-phase qualification before committing to larger volumes. This dynamic favors suppliers that can support application engineering, not just material supply. It also means that early adoption is likely to remain concentrated in use cases where performance advantages are easiest to quantify and where integration risk can be managed through modular or retrofitted systems.
Cost Structure and Competitive Positioning Against Established Adsorbents
A third challenge is cost competitiveness relative to incumbent materials. Conventional adsorbents and separation technologies benefit from mature supply chains, well-understood manufacturing costs, and extensive operational history. MOFs must demonstrate that their performance advantages translate into total-cost advantages, whether through lower energy consumption, higher selectivity, reduced footprint, or longer service life. If the value case depends only on technical superiority without a clear economic pathway, adoption will remain limited to premium applications or highly regulated environments.
This cost dynamic is shaping the competitive landscape. Suppliers are increasingly focused on process efficiency, raw material selection, and manufacturing methods that can lower unit costs without sacrificing performance. The market is therefore evolving in a direction where production methodology, not just material design, determines commercial viability.
Key Drivers Shaping the MOF Market
Technical Innovation and Manufacturing Process Maturation
The most consequential driver in the MOF market is the convergence of material innovation and manufacturing readiness. Recent activity shows that scale-up is no longer theoretical. BASF achieved a milestone by becoming the first company to produce MOFs on a multi-ton production scale for carbon capture, a development that signals a shift from limited batch output to industrially meaningful volumes. That kind of production achievement matters because it reduces the perception risk that MOFs cannot be manufactured at relevant scale.
In parallel, other companies are advancing cost-oriented production pathways. Decarbontek launched commercial production and sale of its DCF-1 MOF, a low-cost, high-performance material available at kilogram scale for carbon capture. The emphasis on lower cost and commercial availability reflects a broader trend: suppliers are moving beyond performance demonstrations to pricing and availability strategies that can support real procurement decisions. Meanwhile, Promethean Particles fulfilled its largest-ever order of four tonnes of MOF for commercial applications, and later demonstrated MOF carbon capture technology in a high-profile showcase, reinforcing the growing visibility of MOFs in practical deployment contexts.
These developments point to a market in which process innovation is becoming a competitive differentiator. Continuous-flow synthesis, scale-up expertise, and the ability to deliver consistent material at commercial volumes are increasingly central to winning demand. For buyers, this means that supplier selection is shifting from pure material specifications to manufacturing reliability and supply assurance.
Policy, Regulatory Pressure, and Decarbonization Mandates
Policy and regulatory pressures are reinforcing demand for high-performance separation and capture materials. Carbon capture, gas purification, and emissions-related applications are increasingly influenced by compliance requirements, corporate decarbonization targets, and operational standards that make lower-energy, higher-selectivity technologies attractive. MOFs are well suited to applications where selectivity and regeneration efficiency can reduce operating cost or enable capture pathways that are otherwise impractical.
The strategic importance of this driver is that policy momentum can accelerate adoption timelines, especially in sectors where emissions performance or gas purity carries direct financial or regulatory consequences. In such environments, MOFs can gain traction faster because the value case includes compliance and risk reduction, not just process efficiency. This does not remove the need for cost competitiveness, but it widens the set of conditions under which MOFs can be commercially justified.
Demand-Side Shifts Toward Higher-Selectivity, Lower-Energy Solutions
Demand is also being shaped by operational priorities across end-use sectors. Companies managing gas streams, industrial emissions, or purification processes are increasingly focused on energy intensity, footprint constraints, and separation precision. In many cases, conventional methods involve trade-offs among capacity, energy use, and operational complexity. MOFs offer a different value proposition: materials that can be engineered for targeted molecular interactions, which can translate into more efficient separation or storage performance.
This demand-side shift favors suppliers that can communicate application-specific value rather than generic material properties. Key commercial questions now include how a MOF performs in a particular stream composition, how often it must be regenerated, what downstream effects it has on process design, and whether it can reduce total operating expense. As a result, the market is moving toward solution-oriented selling, where material performance is tied directly to operational outcomes.
Supply Chain Evolution and the Push Toward Cost-Effective Production
Supply chain dynamics are changing as well. The market is seeing greater attention to reproducible manufacturing, sourcing strategies, and the economics of moving from specialized chemical synthesis to more scalable production modes. Leadership and organizational changes in commercial-stage companies reflect this shift. For example, Promethean Particles appointed its first Chief Financial Officer to support the scale-up of MOF manufacturing, a signal that financing, cost management, and operational scaling are becoming central concerns as companies transition from development to growth.
This evolution is important because the cost of MOFs is not determined solely by chemistry. It is influenced by production throughput, yield consistency, quality control, and the ability to serve customers without excessive customization costs. As suppliers improve these dimensions, the market becomes more accessible to broader industrial adoption. For decision-makers, the implication is that the supply base is becoming more commercially structured, which can improve availability but also increase the importance of supplier differentiation.
Competitive Landscape and Leading Strategies
The competitive environment in the MOF market is shaped by a mix of established chemical manufacturers, specialized material developers, and application-focused suppliers. The market remains moderately concentrated, with a limited set of players holding substantial share, but it also includes a range of firms pursuing differentiated positions across production scale, application focus, and geographic reach.
BASF occupies a distinctive position through its commercial MOF offering for industrial-scale CO2 capture and sustainability applications. Its recent multi-ton production achievement reinforces a strategy centered on scaling proven chemistry into industrial supply. This positions BASF as a supplier capable of supporting large-volume demand where consistency and manufacturing credibility are critical. For buyers in carbon capture and related applications, that scale-up capability can be a decisive factor in procurement decisions.
Promethean Particles has built a position around cost-effective MOF production using a patented continuous-flow process, with applications spanning carbon capture, biogas upgrading, and atmospheric water harvesting. Its recent order fulfillment and executive scaling investments indicate a deliberate move toward commercial growth and operational maturity. The company's strategy illustrates how process technology can differentiate a supplier in a market where cost and repeatability are increasingly central.
Framergy emphasizes coordination polymer MOFs for oil and gas purification and selective adsorption, suggesting a more application-specific focus on industrial gas handling. NuMat Technologies provides custom MOF adsorbents for gas separation, catalysis, and energy applications, highlighting a flexible, customer-tailored approach. MOFapps and NovoMOF similarly concentrate on gas purification, separation, and industrial carbon capture, each with its own angle on performance, cost, or optimization.
On the research and specialty side, Strem Chemicals supplies high-purity MOF powders and research-grade materials, supporting academic and industrial development work. ACSYNAM manufactures custom MOFs for separation, purification, and specialty applications, reinforcing the role of bespoke synthesis in the market. Mosaic Materials and Decarbontek focus on proprietary or low-cost MOF adsorbents for carbon dioxide capture and gas separations, reflecting the growing emphasis on carbon-related applications and cost-sensitive commercialization.
Differentiation Strategies Among Leading Players
Across these companies, several strategic approaches stand out. One is scale-oriented commercialization, where the priority is demonstrating multi-ton production, reliable supply, and compatibility with industrial procurement. Another is cost and process differentiation, where continuous manufacturing or proprietary synthesis methods are used to lower unit costs and improve competitiveness against established adsorbents. A third is application specialization, where suppliers concentrate on particular use cases such as carbon capture, gas purification, biogas upgrading, or selective adsorption, building expertise and customer relationships in targeted segments.
A fourth strategy is customization and service depth, where suppliers position themselves as partners in application engineering rather than straightforward material vendors. This approach can be especially valuable in a market where performance depends heavily on operating conditions and integration requirements. Companies pursuing this model often compete on technical support, testing, and the ability to adapt material properties to customer needs.
How the Competitive Landscape Is Evolving
The market is likely to continue evolving along several lines. First, there is room for consolidation as successful scale-up creates advantages in supply credibility, cost management, and customer confidence. Larger or better-capitalized players may seek to strengthen their positions through partnerships, acquisitions, or expanded production capacity. Second, differentiation is expected to sharpen, because the market is moving from early technology validation toward commercial competition on price, reliability, and application outcomes. Third, new entrants may continue to appear, particularly where novel synthesis methods, lower-cost formulations, or unique application fit create an opening.
For decision-makers, this evolving landscape means that supplier selection should account for both current capability and trajectory. A company with strong research pedigree may not be the best fit if it lacks production scale, while a company with impressive scale-up progress may still be narrowing its application focus. The most relevant evaluation criteria will increasingly include manufacturing maturity, quality consistency, commercial availability, and the supplier's ability to support the buyer's specific operational environment.
Forward Outlook: Trends and Commercial Opportunities
From Pilot Adoption to Broader Industrial Deployment
Over the next three to five years, one of the most important trends is likely to be the shift from pilot and early commercial use toward broader industrial deployment in selected applications. The recent scale-up events and large-order fulfillment activity suggest that the supply side is becoming more capable of supporting commercial demand. As production becomes more routine, adoption can expand beyond niche or demonstration settings into operational environments where MOFs are evaluated on long-term economics and reliability.
This trend creates opportunity for suppliers that can provide not only material but also integration support, regeneration strategy, and performance assurance. It also creates opportunity for end users that can identify high-value separation or capture problems where MOFs offer measurable advantages. The commercial winners are likely to be those who can link material performance to measurable operational improvement in a way that justifies procurement and integration.
Cost Reduction as a Determinant of Market Breadth
A second trend is the growing centrality of cost reduction. As more companies pursue scalable production, competition around price and manufacturing efficiency will intensify. This is likely to widen the addressable market by making MOFs viable in a broader set of applications where cost thresholds previously limited adoption. Low-cost, high-performance materials are especially relevant in carbon capture and gas separation, where operating scale can make even modest efficiency gains economically significant.
The commercial implication is that cost leadership may become as important as performance leadership. Suppliers that can deliver acceptable performance at lower manufacturing cost, or that can tailor cost-performance trade-offs to specific applications, will have a stronger position in commercial negotiations. Buyers, in turn, should expect a wider range of pricing and performance options, which can improve procurement flexibility but also increase the need for careful technical evaluation.
Application Clustering Around Carbon Capture, Gas Purification, and Selectivity-Driven Use Cases
A third trend is likely to be application clustering around use cases where MOFs provide the clearest value. Carbon capture, gas purification, and related separation applications are already prominent in commercial activity, and these areas are well aligned with both performance advantages and external pressures for efficiency and decarbonization. Drug delivery and other specialized applications also remain part of the broader market picture, but industrial gas handling and capture appear particularly well positioned for near-term commercial expansion.
This clustering matters because it suggests that growth may be uneven across application areas. Some segments may scale faster due to stronger demand signals, clearer economic justification, or more favorable integration pathways. For investors and manufacturers, this points to the value of focusing on application environments where the path from material performance to commercial adoption is shortest and most measurable.
Zeolite Molecular Sieves Market
Risks and Uncertainties to Monitor
Despite the positive trajectory, several uncertainties remain. Production consistency and long-term material durability under real operating conditions will continue to be critical validation points. Supply chain constraints, raw material availability, and manufacturing bottlenecks could affect the pace of commercialization if demand grows faster than production capacity. In addition, the market's expansion will depend on whether MOFs can maintain a compelling economic case against established technologies, especially if incumbent solutions also improve or if regulatory and cost conditions shift.
There is also the risk of overconcentration in a small number of application narratives. If carbon capture or related areas dominate attention, other viable uses may receive less investment and slower adoption, even if they offer strong long-term potential. Decision-makers should therefore monitor both the momentum in leading applications and the emergence of differentiated use cases that could broaden the market over time.
Multifunctional Polyhedral Oligomeric Silsesquioxane Poss Market
Strategic Implications for Decision-Makers
For Manufacturers and Material Suppliers
Manufacturers should prioritize reproducible scale-up, quality consistency, and application-specific validation. The market is increasingly rewarding suppliers that can combine material performance with manufacturing reliability. Investing in process control, continuous or semi-continuous production methods, and customer-facing application support can strengthen competitive positioning. It is also important to define a clear value proposition by application rather than relying on broad claims about MOF performance. Suppliers that can demonstrate measurable benefits in target use cases are more likely to convert interest into commercial contracts.
For Investors
Investors should assess companies on manufacturing readiness, cost trajectory, and application fit, not just technical promise. The market is advancing quickly, but differentiation will increasingly come from execution: production scale, supply reliability, and the ability to serve commercial buyers with consistent material and usable solutions. When evaluating opportunities, it is useful to consider which companies are best positioned for the next phase of commercialization, where demand is likely to scale first, and how sustainable a supplier's cost advantage may be. Portfolio decisions should account for the possibility that market leadership will consolidate around players that can deliver both performance and commercial scalability.
For Procurement and End-User Organizations
Procurement teams should evaluate MOF suppliers with a strong focus on operational fit and total cost impact. Key questions include how the material performs in the specific gas stream or process environment, what regeneration and lifetime requirements look like, and whether the supplier can support pilot testing or phased deployment. It is also wise to compare options not only on material specifications but on supply assurance, quality consistency, and the supplier's ability to adapt to changing operational needs. In markets where performance advantages can translate into energy savings, footprint reduction, or compliance benefits, a structured evaluation can reveal value that is not apparent from product claims alone.
Getting the Full Picture
The MOF market is entering a phase in which commercial decisions matter as much as technical potential. Revenue growth, scale-up milestones, and expanding application activity all point to a market that is becoming more operationally significant, but also more complex to evaluate. Differences in manufacturing approach, application focus, cost structure, and supplier maturity are now central to understanding who is likely to capture demand and where adoption will scale fastest.
For organizations making decisions in this space, the most useful next step is to move from general market awareness to a detailed view of segment dynamics, application economics, regional variation, and supplier-specific positioning. A comprehensive report can provide that level of detail, including deeper segmentation data, competitive profiling, and tailored guidance aligned to specific strategic objectives. For executives, planners, and investors who need to act on the market rather than simply observe it, that granularity is where the real strategic value lies.
For detailed analysis of this topic, please visit the official page: Metal-organic Frameworks (MOF) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


