



SSD Market: Why the 19.9% CAGR Trajectory Changes Everything

The Solid State Drive Market: Strategic Shifts and Commercial Opportunities in an Era of Scarcity
The solid state drive market has evolved from a performance upgrade story into a foundational infrastructure play. Over the 2020–2025 historical window, global SSD revenue expanded from approximately 10.0 billion USD to 21.41 billion USD, reflecting a steep acceleration driven by data center expansion, AI workload migration, and the declining relevance of mechanical storage in performance-sensitive deployments. Forward projections estimate the market will reach 76.27 billion USD by 2032, translating to a compound annual growth rate of 19.9 percent across the 2026–2032 forecast period. This trajectory is not merely a function of unit volume growth; it reflects a structural re-pricing of storage as compute-intensive workloads demand higher throughput, larger capacities, and more efficient data movement. The market is large, growing fast, and increasingly constrained by supply-side dynamics that will define competitive outcomes over the next several years.
Yet rapid expansion does not guarantee smooth sailing. The SSD industry is entering a phase where demand signals, technology roadmaps, and supply chain realities are pulling in different directions. Enterprise and cloud customers are locking in capacity for AI and high-performance computing projects, while component availability and pricing power are shifting toward upstream manufacturers. For strategic planners and investors, the central question is no longer whether the SSD market will grow, but how value will be captured amid tightening supply, evolving interfaces, and a concentrated competitive field.
Market Snapshot: Scale, Structure, and Concentration
The revenue trajectory outlined above reflects a market that has already crossed an inflection point. In the historical period, SSD revenue grew from 13.97 billion USD in 2021 to 18.19 billion USD in 2023, then continued to 18.42 billion USD in 2024 before reaching 21.41 billion USD in 2025. The forecast period extends this climb steadily upward, with revenue projected at 25.96 billion USD in 2026, 37.02 billion USD in 2028, 54.23 billion USD in 2030, and 76.27 billion USD in 2032. These figures are presented in USD billions and reflect a market that is scaling at a pace rarely seen in mature semiconductor storage categories.
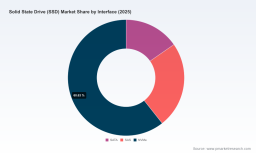
Beneath the headline growth, the revenue mix reveals where value is concentrating. NVMe has emerged as the dominant interface category, reflecting its alignment with low-latency, high-throughput enterprise and data center workloads. SATA and SAS retain meaningful positions, but their relative share reflects legacy deployment patterns and specific enterprise compatibility requirements rather than performance leadership. On the capacity dimension, the market is increasingly balanced across mid-range and high-capacity segments, with above-2TB and 1TB–2TB categories representing substantial revenue pools. This distribution signals that buyers are no longer purchasing SSDs primarily as capacity replacements for hard drives; they are investing in storage tiers that support faster data pipelines, larger model training datasets, and more aggressive inference workloads.
Market concentration further underscores the strategic stakes. The top three players account for approximately 68 percent of revenue, while the top five extend that share to roughly 76 percent. Such concentration matters because it shapes pricing dynamics, supply negotiation leverage, and the pace at which new technology transitions are adopted. In a market where high-density NAND capacity is increasingly scarce, concentrated leadership can translate into stronger control over allocation, roadmaps, and customer commitments.
Key Challenges and Inflection Points
The SSD market faces a set of interlocking challenges that will separate resilient strategies from reactive ones.
- Supply tightness and capacity allocation. High-density NAND availability is becoming a strategic bottleneck. Many downstream manufacturers and module producers are operating with limited inventory buffers, and major cloud providers are securing capacity for AI-related projects well in advance. This creates a market where lead times, prepayment structures, and long-term agreements increasingly determine who can fulfill large enterprise orders.
- Interface and form factor transition friction. As workloads migrate toward higher performance tiers, customers must navigate transitions from legacy interfaces to NVMe-centric designs and from traditional form factors to more space-efficient enterprise footprints. The transition is not purely technical; it affects system design, thermal management, compatibility, and total cost of ownership calculations.
- Regulatory and geopolitical pressure on advanced production. Export controls and related restrictions on advanced semiconductor manufacturing equipment and related items continue to shape where and how leading-edge NAND production can expand. For global supply chains, this introduces uncertainty around capacity addition timing, regional diversification, and the cost of maintaining access to advanced process technologies.
These challenges are not isolated. Tight supply amplifies the strategic importance of interface choices, while regulatory constraints complicate efforts to add capacity quickly. The result is a market where planning horizons are lengthening and competitive advantage is increasingly tied to supply security, technology readiness, and customer relationships rather than short-term pricing maneuvers.
Core Drivers Reshaping the SSD Landscape
Technology Innovation and the Push to Higher Density
Technology leadership is now expressed less in incremental speed gains and more in capacity density, interface efficiency, and workload-specific optimization. Recent product activity illustrates this shift clearly. In mid-2025, Kioxia announced the industry's first 245.76 TB NVMe SSD in 2.5-inch and E3.L form factors, designed for generative AI applications and moved into sampling with select customers. That same year, Micron entered the customer sample stage for its 6550 ION PCIe Gen5 NVMe SSD up to 61 TB in an E3.S form factor targeting high-capacity NVMe workloads. Earlier in the year, Solidigm extended a multi-year agreement with Broadcom for high-capacity SSD controllers supporting AI and data-intensive workloads.
These developments point to a clear pattern: the frontier is moving toward very large-capacity NVMe devices built for data center and AI environments, supported by controller and NAND technology advances that make high-density storage viable at scale. For enterprises, this means the conversation is shifting from "how much storage do we need?" to "how do we architect storage to keep pace with model training, inference, and massive dataset movement?" Higher-capacity SSDs can reduce the number of drives required for a given footprint, simplify rack-scale design, and improve data locality, but they also demand careful validation around endurance, thermal behavior, and controller reliability.
Policy and Regulatory Environment as a Strategic Variable
Regulatory dynamics are increasingly embedded in SSD supply planning. Export controls on advanced semiconductor manufacturing equipment and related items have been implemented in a way that restricts access for certain entities, affecting the trajectory of advanced NAND production expansion. While these measures are not specific to SSDs alone, they influence how quickly leading-edge capacity can be added and where it can be located.
For business planners, the implication is that regional sourcing strategies and supplier diversification are no longer optional risk mitigations; they are core to capacity assurance. Organizations that rely on a single geography or a narrow supplier base may face greater exposure to policy-driven disruptions and allocation decisions. The broader effect is a market in which long-term supply commitments, contractual flexibility, and multi-region sourcing become differentiators in securing critical storage capacity.
PW Consulting
Demand-Side Change: AI, Cloud, and Workload Re-Architecting
Demand is being reshaped by the growth of AI infrastructure and the associated re-architecture of data pipelines. Generative AI and large-scale analytics workloads place unusual stress on storage subsystems because they require high throughput for checkpointing, dataset loading, and rapid access to large volumes of training and inference data. This is encouraging cloud and enterprise buyers to prioritize NVMe-based solutions and larger individual drive capacities, especially where reducing the number of devices per rack or improving data movement efficiency can translate into meaningful operational gains.
At the same time, demand is not uniform across all segments. Consumer and gaming markets continue to value speed and form factor convenience, while enterprise environments prioritize reliability, capacity, and predictable performance under sustained loads. This divergence is pushing vendors to tailor product lines more carefully, with enterprise-focused SSDs emphasizing density and endurance while consumer and prosumer offerings emphasize latency, reliability, and platform compatibility.
Supply Chain and Cost Structure Pressures
The supply side story is becoming as important as the demand side. NAND flash availability is increasingly constrained, with much of the 2026 capacity already committed and high-density NAND effectively allocated to major projects. Inventory at several module manufacturers is expected to last only through early 2026, with stockouts beginning in March and more widespread shortages anticipated after the second quarter. In response, some major NAND foundries have sought three-year cash prepayments from certain customers, a signal that supply leverage has shifted materially upstream.
These conditions change the economics of SSD procurement and production. Buyers face longer commitment horizons and less flexibility to delay purchases without risking allocation. Manufacturers face pressure to secure raw material access, manage pricing carefully, and maintain credibility with enterprise customers who need predictable delivery. In such an environment, the ability to negotiate multi-year supply agreements becomes a competitive advantage. Western Digital and SanDisk, for example, signed multi-year supply agreements lasting up to five years for SSDs and HDDs to align with AI and data center demand. This type of arrangement reflects a broader strategic turn toward supply certainty in a market where capacity is not easily created on demand.
Competitive Landscape and Leadership Strategies
The competitive field in SSDs is concentrated and technically demanding. Samsung Electronics continues to lead in high-capacity data center and enterprise SSDs, with products such as the PM9D3a achieving read speeds up to 12,000 MB/s. SK hynix provides enterprise and high-performance SSDs powered by 321-layer QLC NAND, emphasizing advanced process technology as a differentiator. Micron Technology supplies high-capacity PCIe Gen5 NVMe SSDs, including the 6550 ION and 6600 ION families with capacities reaching up to 61 TB and 245.76 TB respectively, targeting large-scale data center deployments. Kioxia Corporation has pushed the capacity frontier with the LC9 Series and BiCS5 NAND-based drives, including what it describes as the industry's first 245.76 TB NVMe SSD.
Western Digital Corporation and its SanDisk brand continue to play a broad role across enterprise and high-performance SSDs, including the WD Black SN series and SanDisk-branded enterprise and portable products. Seagate Technology serves enterprise NVMe SSD needs for data centers and hyperscale applications. Solidigm focuses on high-capacity QLC PCIe SSDs for AI and data center workloads, exemplified by the D5-P5336 at 122 TB. In adjacent segments, Corsair produces high-performance gaming and M.2 NVMe SSDs such as the MP700 Pro XT; Kingston Technology emphasizes reliable consumer and enterprise offerings with a focus on speed and dependability; Crucial offers value-oriented NVMe and SATA SSDs with PCIe Gen5 options; Apacer Technology targets industrial and embedded applications; ADATA Technology produces gaming and portable SSDs across USB and NVMe form factors; ATP Electronics manufactures compact NVMe PCIe Gen4 SSDs with broad supply chain control; and Phison Electronics supplies enterprise SSD controllers and reference designs that enable other manufacturers to build competitive products.
Strategic Positioning and Differentiation
These companies are not competing on identical terms. Some differentiate through leading NAND process technology and capacity scaling; others through controller ecosystems, form factor specialization, or vertical integration across the supply chain. A few have built strong positions in enterprise density and AI-oriented workloads, while others concentrate on gaming, industrial, or value-oriented consumer markets. The most strategically resilient players tend to combine several of the following advantages:
- Capacity and technology leadership. Early moves into very large-capacity NVMe SSDs and advanced NAND layers can create credibility with data center customers who need to plan for multi-year workload growth.
- Supply assurance and contractual commitment. Long-term agreements and prepayment arrangements can secure allocation in a tight market, which is increasingly valuable when shortages are expected to persist into the second half of 2026 and beyond.
- Controller and ecosystem influence. Companies that shape controller designs or provide reference platforms can influence performance, reliability, and time-to-market across a broader manufacturing base.
- Segment focus. Clear positioning in enterprise, industrial, gaming, or consumer markets helps avoid direct head-to-head competition across every product tier and allows tailored validation and support.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The market is likely to evolve along two parallel tracks. On one hand, concentration among top players supports scale advantages in capacity procurement, R&D investment, and enterprise customer relationships. On the other hand, specialized niches remain open for companies that serve industrial, embedded, gaming, or regional market needs with distinct form factors, durability profiles, or price-performance trade-offs. New entrants and smaller specialists can still win by addressing workload-specific requirements or by providing critical components such as controllers and reference designs that broader manufacturers integrate into their own products.
At the same time, the supply environment may accelerate consolidation behavior. When high-density NAND is scarce and prepaid commitments are required, smaller players with weaker balance sheets or limited supply access may find it harder to sustain large enterprise programs. Conversely, well-positioned specialists can benefit if larger customers seek additional sourcing options to reduce dependency risk.
Future Outlook: Three Strategic Trends for the Next 3–5 Years
Trend 1: Capacity Density Becomes the Central Battleground
Over the next several years, the most consequential competition will center on high-capacity NVMe SSDs designed for data center and AI environments. As model sizes, dataset scales, and inference demands grow, organizations will seek storage that minimizes the number of devices, simplifies rack design, and supports sustained throughput. This favors products that combine advanced NAND, efficient controllers, and validated enterprise reliability. The commercial opportunity lies in architecting storage solutions that reduce operational complexity while meeting performance and endurance requirements. The risk is that capacity claims outpace real-world reliability or thermal management, especially in dense deployments.
Trend 2: Supply Security Becomes a Strategic Procurement Priority
Given the current NAND shortage dynamics and the expectation that shortages may persist through the third quarter of 2026, procurement strategies will increasingly emphasize multi-year commitments, diversified sourcing, and early alignment with manufacturers. Organizations that wait for spot availability may face both price and allocation disadvantages. The commercial opportunity here is not simply buying earlier; it is building procurement relationships and contract structures that balance flexibility with security. The risk is over-committing to a single supplier or technology path before workload requirements are fully validated.
Worldwide SSD Memory Card Market
Trend 3: Interface and Platform Standardization Will Shape System Design
As NVMe continues to dominate new enterprise and data center deployments, system architects will place greater emphasis on form factor choices, thermal design, and integration with broader platform roadmaps. The transition toward compact enterprise form factors and higher-throughput interfaces will reward vendors that can demonstrate dependable performance in real deployment conditions, not just benchmark highlights. The commercial opportunity lies in helping customers navigate migration paths from legacy interfaces and larger device counts to fewer, higher-capacity NVMe devices. The risk is that migration introduces unforeseen compatibility or validation costs, particularly in mixed environments where older systems coexist with newer deployments.
Strategic Recommendations for Decision-Makers
For Manufacturers and Component Suppliers
Prioritize supply resilience and technology credibility. In a market where high-density NAND is heavily committed and prepayments are becoming more common, securing capacity through partnerships, long-term agreements, and disciplined inventory planning is essential. Equally important is validation: large-capacity enterprise SSDs must demonstrate endurance, thermal stability, and consistent performance under sustained workloads. Companies that can pair capacity leadership with reliable customer sampling, clear roadmap communication, and flexible sourcing options will be better positioned to retain enterprise trust.
For Investors
Focus on companies with defensible positions in capacity scaling, controller ecosystems, or specialized segments where technical barriers and customer relationships create durable advantages. The concentration of revenue among a small group of leaders suggests that scale and supply access matter, but specialized players can still outperform if they serve underserved workloads or provide critical enabling technologies. Monitor signals such as multi-year supply agreements, sampling progress for very large-capacity NVMe devices, and any shifts in prepayment or allocation practices, as these often precede changes in competitive leverage.
For Enterprise Buyers and Procurement Leaders
Treat storage capacity as a strategic input rather than a commoditized purchase. Where AI, analytics, or high-throughput data pipelines are central to operations, plan for multi-year supply alignment and evaluate vendors on the basis of capacity roadmaps, validation rigor, and ability to support migration from legacy interfaces. Diversify sourcing where feasible, and avoid relying on short-term availability assumptions in a market where NAND inventory buffers are thin and shortages are expected to extend through much of 2026. Balance commitment with flexibility by structuring agreements that protect against allocation risk without locking in unfavorable technology choices.
Closing Perspective
The SSD market is entering a phase where growth, scarcity, and technology transition intersect. Revenue is expanding rapidly, but the practical challenge for most organizations is not accessing a market that is obviously growing; it is securing the right capacity, at the right performance level, with enough supply certainty to support multi-year infrastructure plans. The companies and buyers that succeed will be those who treat SSDs as part of a broader data architecture strategy, align procurement with technology roadmaps, and prepare for a supply environment in which allocation and relationships matter as much as specifications.
Radiation-Hardened SSD Market
Detailed segmentation data, company-level assessments, and scenario-based guidance can help translate these strategic themes into operational decisions. PW Consulting's full research report provides deeper breakdowns across regions, interfaces, capacities, and competitive profiles, along with tailored recommendations for manufacturers, investors, and enterprise procurement teams seeking to navigate a market defined by both rapid growth and persistent supply constraints.
For detailed analysis of this topic, please visit the official page: Solid State Drive (SSD) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


