



Solder Resist Ink Market Beyond 6.8% CAGR: The Core Drivers Powering the PCB Industry

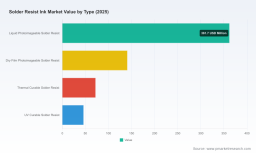
The Solder Resist Ink Market: Strategic Trends and Commercial Opportunities Through 2032
The solder resist ink market has entered a phase of steady, technology-driven expansion. Valued at approximately 450.0 million in 2020, the market reached an estimated 620.0 million by 2025 and is projected to approach 983.0 million by 2032, advancing at a compound annual growth rate of 6.81 percent. This trajectory reflects a sector that is no longer defined solely by incremental PCB manufacturing demand, but by the convergence of advanced packaging, stricter chemical regulations, and ongoing shifts in material supply chains. For executives and investors evaluating the electronics materials landscape, the next seven years will reward those who understand how formulation innovation, regional capacity dynamics, and compliance requirements reshape competitive positioning.
Beneath the headline growth figures lie structural pressures that will determine which players capture margin expansion and which face commoditization. The market is consolidating around a small group of specialty chemical and advanced materials firms, yet the pace of technological change in substrate design and packaging architectures continues to test traditional product roadmaps. At the same time, environmental mandates and end-customer specifications are forcing a reevaluation of resin systems, curing methods, and process compatibility. These dynamics create both risk and opportunity, but only for organizations that can align product development with the operational realities of PCB fabricators and semiconductor package manufacturers.
Market Landscape and Core Challenges
The market's expansion from 2020 through 2025 was driven by a combination of downstream electronics demand and gradual replacement of legacy coating processes with more precise photopatternable alternatives. The forecast period through 2032 suggests continued momentum, though the composition of growth is likely to shift. Revenue is increasingly tied to applications that require tighter registration, finer line resolution, and stronger thermal and mechanical durability. This shifts the competitive focus from volume-based commodity supply to performance-based differentiation, where formulation stability, process window, and end-use reliability matter more than price per liter.
Several challenges define the current inflection point. First, regulatory pressure on chemical content is compressing the allowable design space for traditional epoxy-based systems. Limits on volatile organic compounds, halogen content, and specific bisphenol compounds are no longer optional compliance checkpoints; they are becoming baseline requirements for supply approval in major Original Equipment Manufacturer ecosystems. Second, raw material cost volatility is disrupting margin planning. Tariffs, logistics friction, and geopolitical disruptions in chemical feedstocks have introduced unpredictable cost swings that ripple through ink pricing, inventory strategy, and customer negotiations. Third, the widening gap between high-performance applications and cost-sensitive mainstream PCB production is fragmenting the buyer base. Manufacturers serving advanced semiconductor packaging or high-density interconnect boards face different performance thresholds than those producing standard rigid boards, and a single product strategy rarely serves both effectively.
Solder Paste Market
Together, these challenges push the market toward a more segmented competitive structure. Incumbents with broad formulation portfolios and established qualification networks gain an advantage, while smaller players must choose between niche specialization and aggressive cost positioning. The firms that succeed will be those that can translate regulatory constraints into product advantages rather than treating them as mere compliance burdens.
Key Drivers Reshaping the Market
Technological innovation remains the most direct engine of market change. The shift toward thinner insulation layers, finer pitch routing, and advanced interconnect structures demands solder resist materials that can deliver high-resolution imaging, strong adhesion on low-flow substrates, and reliable thermal stability during reflow and assembly. Liquid photoimageable formulations continue to dominate where pattern precision and process flexibility are critical, while dry film alternatives maintain relevance in applications that benefit from uniform thickness control and simplified handling. At the same time, UV-curable and thermally curable systems are being refined for specific process windows, especially where throughput, energy consumption, or substrate compatibility dictate a particular curing approach. Innovation is increasingly measured not just by resolution or adhesion, but by how well a formulation integrates into automated lines, reduces defect rates, and withstands stricter chemical restrictions.
Policy and regulatory environments are becoming equal drivers of formulation strategy. Environmental regulations promoting low-VOC and water-based inks are accelerating adoption of eco-friendly solder resist systems across multiple production regions. In parallel, European manufacturers have introduced bio-based inks with full halogen-free certification, signaling that sustainability claims are moving from marketing narratives to product specifications with measurable chemical boundaries. On the OEM side, stringent regulated substances specifications have imposed tight limits on bisphenol chemicals in epoxy resin-based solder resist inks, effectively forcing formulators to qualify alternative chemistries or risk exclusion from major supply chains. Combined with broader chemical registration frameworks that restrict certain substances, these rules are reshaping the ingredient landscape and rewarding companies with strong regulatory intelligence and rapid reformulation capability.
Demand-side changes are also restructuring the market. The growth of advanced semiconductor packaging and high-complexity PCB designs is expanding the share of applications that require materials with superior dimensional stability, lower thermal stress, and enhanced protection against electrochemical migration. LED packaging and specialized electronic assemblies contribute additional demand for materials that balance optical, mechanical, and insulating properties. More broadly, electronics manufacturers are seeking supply partners that can reduce process variability and support qualification cycles faster. This creates a demand environment where technical service, documentation quality, and consistent lot-to-lot performance increasingly influence purchasing decisions alongside unit pricing.
Supply chain and cost structure changes form the fourth major driver. Raw material price fluctuations tied to trade measures and global conflicts have made feedstock planning more complex, particularly for resin systems, photoactive compounds, and specialized additives. Manufacturers are responding by adjusting inventory strategies, qualifying secondary sources, and redesigning formulations to reduce exposure to volatile inputs without sacrificing performance. This environment favors companies with diversified supplier networks, transparent cost structures, and the ability to communicate value beyond base material price. It also raises the importance of regional production planning, as local formulation and finishing capabilities can reduce exposure to freight volatility and improve responsiveness to customer requirements.
Competitive Landscape and Leading Strategies
The competitive structure is concentrated, with a core group of Japanese, American, Taiwanese, Korean, and Chinese firms controlling a substantial share of revenue. Japanese companies remain prominent through deep formulation expertise, strong presence in high-resolution PCB and advanced packaging applications, and long-standing qualification relationships with major electronics manufacturers. Their portfolios typically span liquid and dry film photoimageable solder resists, with differentiation rooted in process reliability, specialty mask solutions, and materials engineered for semiconductor substrates and rigid or flexible boards. Western firms contribute complementary strengths, particularly in epoxy-based formulations, broader electronics chemistry portfolios, and channel reach across multiple PCB and substrate ecosystems. Taiwanese and Korean manufacturers emphasize dry film and photoimageable materials tailored to PCB and IC substrate production, while Chinese players have expanded rapidly in liquid photoimageable solder resist supply, often competing on process compatibility, regional service, and cost efficiency.
Leading strategies in this market increasingly revolve around three pillars: formulation adaptability, qualification speed, and regional responsiveness. Companies that can reformulate quickly to meet halogen-free, low-VOC, or bisphenol restriction requirements while maintaining electrical insulation and solder resistance gain a durable advantage. Those that invest in application support and process optimization help customers reduce defect rates and shorten trial cycles, which strengthens stickiness in a market where switching costs can be high once a material is qualified into a production line. Recent company activity reinforces this focus. One Japanese leader expanded its visibility through exhibition presence with solder resist masks, signaling continued engagement with downstream manufacturing communities. Another launched a research and development center focused on next-generation semiconductor package technology under a consortium framework, underscoring the shift toward advanced packaging as a growth frontier. Taiwanese and other materials suppliers have showcased advanced polymer and UV technologies at major trade events, alongside durable resins and low-VOC solutions, reflecting the dual priorities of performance and environmental compliance.
The market is evolving toward a hybrid structure of consolidation at the top and fragmentation at the application level. Large incumbents are likely to strengthen their positions through portfolio breadth, regulatory readiness, and integration with broader electronics materials offerings. Mid-tier and regional suppliers may find room to grow by focusing on specific curing technologies, substrate types, or regional service models. New entrants will face a steep qualification barrier, but targeted innovation in niche performance areas or cost-optimized formulations can still create entry points, especially where downstream manufacturers are seeking alternative sources to manage supply risk. The key differentiator is no longer simply whether a company can produce solder resist ink, but whether it can deliver the right balance of resolution, chemical compliance, cure flexibility, and total cost of ownership for a given application.
Solder Market
Future Trends and Commercial Opportunities
Over the next three to five years, the market is likely to be shaped by a stronger alignment between material chemistry and regulatory endpoints. Eco-friendly formulations will move from optional upgrades to default expectations in many customer audits, particularly where low-VOC, halogen-free, and restricted-substance compliance intersect. This trend creates commercial opportunities for suppliers that can offer validated alternative chemistries with documented performance equivalence, along with the technical support needed to facilitate line integration. It also opens space for product bundling strategies that pair solder resist materials with complementary process chemicals, training, and qualification assistance.
A second trend is the continued expansion of high-value applications in advanced packaging and complex PCB architectures. As interconnect density rises and substrate materials become more diverse, demand for solder resist systems that maintain insulation integrity under thermal cycling, mechanical stress, and finer patterning will grow. This favors companies with formulation platforms that can be tuned for different substrate classes and process conditions. Commercial opportunity lies in developing application-specific variants rather than relying on a single generic product, and in building the testing and documentation infrastructure needed to support faster customer qualification.
A third trend is the growing importance of supply resilience and regional production strategy. Cost volatility and trade-related uncertainty are pushing buyers to consider not only price, but also lead-time stability, local technical support, and reduced exposure to long logistics chains. Suppliers that can offer predictable fulfillment, flexible inventory arrangements, and regionally aligned service models may capture preference even where their base pricing is not the lowest. The commercial opportunity here is operational as much as technical: manufacturers that invest in supply chain transparency and customer-facing responsiveness can convert disruption pressure into differentiated value.
Risks remain significant. Regulatory specifications may tighten further, forcing additional reformulation cycles and potentially raising the cost of compliance. Raw material volatility could persist, compressing margins for suppliers that lack hedging strategies or alternative feedstock options. In addition, if advanced packaging growth slows or PCB demand patterns shift faster than anticipated, revenue expectations for certain product segments may need reassessment. Companies that rely on a narrow product range or a single region for growth could face disproportionate exposure. The most resilient strategies will combine formulation flexibility with diversified application coverage and disciplined cost management.
Actionable Guidance for Decision-Makers
For manufacturers and material suppliers, the priority is to treat regulatory and performance requirements as a combined design constraint rather than separate workstreams. This means investing early in alternative resin systems and additive packages that can meet low-VOC, halogen-free, and restricted-substance expectations without undermining insulation, adhesion, or image resolution. It also means building formal qualification support into the product lifecycle, so that customers can evaluate new formulations with clear test data, process guidance, and lot consistency evidence. Companies that can reduce the time and uncertainty of material swaps will strengthen their position as preferred suppliers in a market where qualification friction remains a major barrier.
For investors, the value lies in distinguishing between volume-driven commodity exposure and performance-driven specialty exposure. Businesses with strong formulation IP, active regulatory monitoring, and a track record of adapting to OEM specifications are better positioned to sustain margins through compliance cycles and input cost swings. Portfolio exposure should also be evaluated against application mix, since advanced packaging and high-complexity PCB demand can support higher-value positioning, while cost-focused mainstream segments remain more price-sensitive. Monitoring recent R&D launches, trade show activity, and regional expansion signals can provide early indications of where competitive advantage is being built.
For procurement teams and end-product manufacturers, the strategic focus should shift from unit price to total process impact. Solder resist selection affects defect rates, rework, qualification cycles, and compliance risk, all of which influence downstream cost and schedule reliability. Evaluating suppliers on documentation quality, chemical compliance readiness, cure flexibility, and technical support can reduce hidden costs that are not visible in initial quotations. Maintaining a qualified second source for critical materials is also prudent, given ongoing raw material volatility and the possibility of supply disruption. Procurement strategies that incorporate performance testing, regulatory documentation review, and regional service capability will likely produce more resilient sourcing outcomes than those based primarily on price ranking.
PW Consulting
The market's trajectory through 2032 points toward continued growth, but with a clear premium on differentiation, compliance readiness, and application-specific performance. Organizations that align product strategy with these realities will be better placed to capture value as the market matures. For decision-makers seeking a deeper look at segment-level dynamics, regional revenue splits, application growth paths, and company-specific positioning beyond the overview presented here, the full PW Consulting market analysis provides detailed breakdowns and customized strategic recommendations to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Solder Resist Ink Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


