



Industrial Mixer Market 2026: Why a 6.98% CAGR Trajectory Signals Fundamental Shifts in Processing

Industrial Mixer Market: Navigating Strategic Shifts and Commercial Opportunities Through 2032
Market Snapshot: Growth Trajectory and Structural Realities
The industrial mixer market has demonstrated consistent expansion over the past half-decade, reflecting the sector's foundational role in manufacturing, processing, and materials transformation. Revenue reached approximately 215.0 million USD in 2025, building on a compound annual growth rate of 6.98 percent projected through 2032. The trajectory from 2020 to 2025 shows a market that recovered from pandemic-era disruptions, stabilized around 193.68 million USD in 2023, and accelerated toward 206.19 million USD in 2024 before settling at current levels. Forward projections indicate the market will cross 227.79 million USD in 2026 and approach 344.8 million USD by 2032, signaling steady demand despite macroeconomic headwinds.
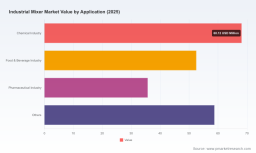
This growth is not uniform across geographies or end-use verticals. Regional revenue distribution is concentrated in North America (67.82 million USD), Asia Pacific (70.02 million USD), and Europe (46.47 million USD), with Latin America and the Middle East and Africa contributing 20.66 million USD and 10.03 million USD respectively. Application-wise, the chemical industry anchors demand at 68.12 million USD, followed by food and beverage (52.47 million USD), pharmaceuticals (35.68 million USD), and other sectors (58.73 million USD). By equipment type, solid-solid systems lead at 84.41 million USD, solid-liquid configurations account for 51.7 million USD, liquid-gas setups represent 43.38 million USD, and liquid-liquid variants cover 35.51 million USD. Market concentration remains moderate, with the top three players holding 24.6 percent share and the top five reaching 26.2 percent, indicating room for both established incumbents and agile newcomers.
Two structural tensions define the current landscape. First, the market sits at the intersection of mature industrial demand and emerging technology-driven specifications, creating pressure on suppliers to balance cost efficiency with performance customization. Second, regulatory shifts and trade policy volatility are reshaping procurement logic, pushing buyers to weigh domestic sourcing incentives against global cost arbitrage. These dynamics are not transient; they are restructuring how mixer manufacturers position their offerings and how end-users evaluate total cost of ownership.
Key Challenges and Inflection Points
Three challenges warrant immediate attention from operators and investors alike.
- Supply chain fragility and raw material cost volatility. Industrial mixer fabrication depends heavily on stainless steel, specialty alloys, and precision components. Price swings in these inputs directly compress margins and disrupt lead-time reliability. Manufacturers that rely on just-in-time procurement or single-source relationships face amplified exposure, while buyers encounter uneven availability and unpredictable pricing across contract cycles.
- Regulatory recalibration and compliance complexity. Recent legislative changes in the United States have introduced tax incentives for domestic machinery investment, including full cost expensing for qualifying equipment and expanded Section 179 deductions. At the same time, safety standards, code compliance, and certification requirements continue to tighten across chemical, pharmaceutical, and food processing verticals. Suppliers must navigate a patchwork of regional requirements while maintaining standardized quality, and buyers must align procurement decisions with compliance audits and operational safety mandates.
- Demand fragmentation across applications and form factors. While chemical processing remains the largest application driver, growth is increasingly distributed across food and beverage, pharmaceuticals, construction materials, and high-performance material processing. Each segment imposes distinct mixing profiles, throughput requirements, and sanitation or containment standards. The result is a market where batch mixers, planetary systems, high-shear units, dispersers, and agitators compete not as commodities but as engineered solutions tailored to specific process windows.
Core Growth Drivers
The market's expansion is propelled by a convergence of technology, policy, demand behavior, and cost structure evolution.
Technology Innovation and Performance Differentiation
Advances in mixing geometry, drive systems, and control architecture are redefining what industrial mixers can achieve. High-shear and multi-shaft configurations enable finer dispersion and more uniform blending in viscous or multiphase media, while planetary and intensive mixer designs support demanding applications in ceramics, refractories, and concrete processing. Custom engineering has become a competitive necessity rather than a premium add-on, as end-users seek equipment that fits existing vessel footprints, meets specific shear rates, and integrates with automation layers. Control systems with certified safety logic and process monitoring capabilities reduce downtime and improve repeatability, which matters increasingly in pharmaceutical and food applications where batch consistency carries regulatory and quality implications.
Policy and Regulatory Incentives
The policy environment in 2025 and 2026 has shifted the calculus for domestic equipment investment. Tax incentives tied to U.S.-made machinery purchases—encompassing full cost expensing and Section 179 deductions—lower the effective capital outlay for qualifying buyers and create a timing advantage for procurement decisions made in the near term. Simultaneously, compliance expectations around U.S. codes, safety standards, and UL-certified control systems are becoming baseline requirements rather than differentiators. For manufacturers, this means domestic production and documented compliance are not just operational choices but commercial positioning tools. For buyers, it introduces a trade-off between short-term price advantages from imported equipment and longer-term benefits from localized support, faster lead times, and incentive eligibility.
Demand-Side Behavior and Application Expansion
End-user behavior is shifting from lowest-price procurement to risk-adjusted sourcing. Chemical processors continue to drive baseline demand, but food and beverage operators are investing in equipment that supports stricter sanitation, faster changeovers, and consistent batch quality. Pharmaceutical manufacturers prioritize validated processes and traceable control systems. Construction and materials processors are expanding capacity for concrete, ceramic, and refractory production, where intensive and planetary mixers play a central role. This diversification broadens the addressable market and increases the value of application-specific engineering, while also raising the bar for after-sales support, spare parts availability, and lifecycle service.
Supply Chain and Cost Structure Evolution
Cost structures are being reshaped by raw material dynamics, domestic sourcing incentives, and logistics constraints. Stainless steel and alloy price fluctuations directly affect manufacturing expenses, and suppliers that can stabilize input costs through forward contracts, diversified sourcing, or localized production gain margin resilience. For buyers, the total cost view increasingly includes lead time reliability, installation support, compliance documentation, and service responsiveness. The net effect is a market where domestic manufacturers with shorter lead times and transparent compliance records are gaining traction, especially where policy incentives and supply chain disruptions amplify the cost of delays or non-compliance.
PW Consulting
Competitive Landscape and Strategic Positioning
The competitive field blends established U.S. manufacturers with international suppliers capable of scaling specialized equipment. Several players illustrate the divergent strategies shaping the market.
Charles Ross & Son Company has built its positioning around U.S.-built mixing equipment with custom engineering for food, chemical, pharmaceutical, and battery applications. Its product range—ribbon blenders, planetary mixers, high-shear mixers, and multi-shaft systems—targets segments where process control and code compliance carry significant weight. Recent commentary from the company highlights the advantages of domestically produced equipment during periods of supply chain disruption, tariffs, and regulatory change, while pointing to tax incentives under the One Big Beautiful Bill Act of 2025 for machinery purchases. The company's emphasis on U.S. code alignment and UL-certified control systems reinforces a compliance-forward value proposition that resonates with buyers who need documented safety and regulatory adherence.
INDCO focuses on industrial mixers, dispersers, and tank agitators with an emphasis on domestic raw materials and short lead times for chemical, food, pharmaceutical, and paint industries. This model addresses a practical buyer concern: the risk of delays and input cost volatility. By maintaining domestic material sourcing and streamlined production, the company positions itself as a reliability option in a market where supply continuity is increasingly valued alongside price.
Dynamix Agitators specializes in custom-configured large- and mid-size industrial batch mixers and agitators for mining, oil and gas, chemical, pharmaceutical, and distillery applications. Its strength lies in tailoring equipment to demanding process environments where throughput, containment, and mechanical robustness are non-negotiable. Customization at scale allows the company to serve sectors with higher specification requirements while maintaining a flexible engineering posture.
Worldwide Industrial Kneader Market
CO-NELE Mixer, based in China, manufactures planetary concrete mixers, intensive mixers, granulators, and refractory mixers for construction, chemical, ceramic, and high-performance material processing. The company's participation in major trade events, such as the UK Concrete Show 2026, signals a push into international markets where concrete and materials processing demand remains active. Its offering illustrates how international manufacturers compete on specialization and demonstration-driven engagement, targeting verticals where application-specific design and on-site visibility matter.
Concrete Mixers Market
Market Evolution Trends
The competitive structure is evolving along three directions. Consolidation pressure is building among mid-tier players who lack economies of scale in custom engineering or who face rising compliance and sourcing costs; some will partner, be acquired, or exit niche segments. Differentiation is intensifying as manufacturers separate into compliance-centric domestic builders, customization-focused specialists, and international suppliers competing on application breadth and demonstration strength. New entrants are likely to emerge around niche applications—such as battery materials mixing or advanced ceramics—where process requirements are stringent and service expectations are high. The net result is a market where breadth of product line matters less than depth of application expertise, lead-time reliability, and the ability to document compliance and support lifecycle needs.
Outlook: Trends Shaping 2026–2032
Three trends are likely to define the next cycle.
- Domestic investment acceleration backed by incentives. Policy incentives for U.S.-made machinery will encourage procurement timing shifts and expand the addressable base for compliant domestic equipment. Buyers evaluating capital projects in 2026 and beyond will increasingly factor incentive eligibility, code alignment, and support proximity into the decision, not just sticker price. Suppliers with documented domestic production and certified control systems are positioned to capture a disproportionate share of this shift.
- Application-specific engineering as the default expectation. As demand spreads across chemical, food, pharmaceutical, construction, and high-performance materials, generic mixer specifications will lose share to engineered configurations that match shear profiles, sanitation needs, containment demands, and integration requirements. The commercial opportunity lies in bundling equipment with validated process parameters, control architecture, and service agreements that reduce operational risk.
- Supply chain resilience becoming a priced attribute. Raw material volatility and logistics constraints will keep lead-time reliability and input cost stability in focus. Manufacturers that secure material availability, diversify sourcing, and offer transparent lead times will earn premium positioning, while buyers will increasingly pay for predictability and reduced downtime risk. This trend reinforces the value of regional production footprints and documented compliance, particularly where disruptions and policy changes intersect.
These trends carry uncertainty. Incentive frameworks may be revisited, altering the timing advantage for domestic purchases. Raw material markets can shift quickly, affecting margin planning on both sides of the transaction. Application demand may concentrate in select verticals if broader industrial investment slows, leaving other segments to compete for incremental growth. Buyers and suppliers alike should model these contingencies rather than assume a linear path.
Strategic Implications for Decision Makers
Manufacturers should prioritize compliance documentation, domestic material sourcing where feasible, and application-specific engineering capabilities. Investing in certified control systems and U.S. code alignment is no longer optional for players targeting regulated verticals; it is a market-access requirement and a sales enablement tool. Companies that can demonstrate short lead times, stable input sourcing, and validated process performance will differentiate against commodity-priced alternatives and capture demand from buyers who value predictability.
Investors should look for manufacturers with clear application focus, resilient cost structures, and a credible domestic or compliance-forward positioning. Businesses that combine customization capacity with reliable delivery and documented safety standards are better placed to sustain margins through raw material cycles and policy shifts. Exposure to high-growth applications—such as battery materials, advanced ceramics, and pharmaceutical processing—offers incremental upside, but only when paired with engineering depth and service infrastructure to support those segments.
Procurement and operations leaders should rebalance total cost models to include incentive eligibility, compliance risk, lead-time reliability, and lifecycle support. Domestic equipment with certified controls and documented code alignment may present a higher initial price but lower total risk in regulated environments, especially where tax incentives and supply chain disruptions alter the cost of delay. For international sourcing, buyers should stress-test lead times, spare parts availability, and compliance documentation to ensure that short-term savings do not create operational or audit exposure later.
The industrial mixer market is entering a phase where policy incentives, compliance expectations, and supply chain realities interact with application-specific demand to reshape buying and selling logic. Players who treat these forces as strategic variables—rather than background conditions—will be better positioned to capture growth through 2032. For detailed segmentation data, regional breakdowns, company-level benchmarks, and customized scenario analysis, the full research report provides the granularity needed to translate these trends into specific investment and procurement decisions.
For detailed analysis of this topic, please visit the official page: Industrial Mixer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


