



Consumer Pressure Washers: 4.8% CAGR Growth and Where the Market Is Moving

Strategic Shifts and Commercial Opportunities in the Consumer Pressure Washers Market
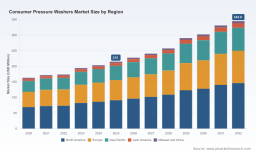
The consumer pressure washers market has demonstrated resilient growth over the past half-decade, transitioning from a mature, cyclical segment to one characterized by technological differentiation and evolving regulatory pressures. Market valuation reached approximately 215 million USD in 2025, expanding from roughly 163 million USD at the start of the historical review period in 2020. The trajectory suggests a steady advance toward 345 million USD by 2032, underpinned by a compound annual growth rate of 4.8 percent across the forecast window. This expansion is not merely a function of population growth or disposable income trends; it reflects a structural recalibration in how consumers and light commercial operators approach surface maintenance, driven by convenience expectations, sustainability mandates, and rapid iteration in motor and battery architecture.
Despite the positive top-line momentum, the sector confronts several inflection points that will separate agile operators from those constrained by legacy product architectures or static distribution assumptions. First, regulatory tightening at the municipal and national levels is beginning to reshape allowable use cases, particularly where water consumption, runoff management, or electrical safety standards intersect with consumer-grade equipment. Second, the cost and availability dynamics of core components—particularly lithium-ion cells, rare-earth motors, and polymer composites—are pressuring margin structures and forcing manufacturers to reconsider bill-of-materials strategies. Third, competitive intensity at the consumer end of the spectrum is elevating customer acquisition costs while compressing the window for product lifecycle differentiation, as feature parity spreads across mainstream retail channels. These forces collectively demand a more granular approach to product positioning, regional go-to-market planning, and risk mitigation.
Electricity, Autonomy, and the Redefinition of Consumer Utility
Technological innovation remains the primary engine of market evolution, with the most consequential advances unfolding in electric powertrain design and battery integration. Gas-powered units continue to hold meaningful share, particularly among users who prioritize high continuous output and portability in off-grid settings, but electric architectures are capturing incremental share among urban and suburban consumers who value quieter operation, lower maintenance burdens, and indoor storage compatibility. The broader trend is not a simple substitution of power sources; rather, it reflects a segmentation of use cases. High-cycle residential cleaning tasks, such as driveway and siding maintenance, increasingly favor electric platforms that can be deployed without fuel handling or combustion-related ventilation concerns. Meanwhile, battery-powered models are expanding the boundary of convenience by eliminating cord constraints, though their adoption remains tied to runtime improvements, charge-cycle durability, and price thresholds that make premium battery packs accessible to mainstream buyers.
Within this context, manufacturers are investing in horizontal series architectures and modular accessories that simplify assembly, reduce service friction, and create cross-sell pathways. Companies that have emphasized compact electric lines for home and garden applications are aligning product roadmaps with the expectation that consumers will favor equipment that is easy to store, quick to start, and straightforward to maintain. This shift is also reshaping purchasing behavior: buyers are increasingly comparing total cost of ownership rather than sticker price alone, weighing factors such as filter replacement intervals, pump life, and the availability of replacement nozzles or hoses. The practical implication is that innovation is no longer measured solely by pressure output or flow rate; it is increasingly defined by ecosystem completeness and the degree to which a unit integrates with the user’s existing cleaning routines.
PW Consulting
Regulatory Signals and the Rebalancing of Adoption Pathways
Policy and regulatory developments are introducing both constraints and catalysts. In several jurisdictions, water conservation rules are narrowing the permissible frequency or scope of aesthetic pressure washing, which can dampen repeat purchases for non-essential cleaning while simultaneously elevating demand for high-efficiency nozzle designs, flow-restriction features, and equipment that performs effectively at lower water volumes. These constraints are prompting manufacturers and retailers to rethink product messaging, shifting emphasis from raw power toward precision, water management, and compliance-friendly operation. Where local ordinances increasingly target runoff or noise, equipment that can satisfy municipal expectations while maintaining perceived effectiveness gains a structural advantage in retail placement and consumer trust.
Safety regulation is simultaneously sharpening the focus on electrical integrity and component certification. Recalls tied to missing ground-fault protection or inadequate insulation have underscored the importance of rigorous design validation, particularly for corded electric models that operate in wet environments. These events reinforce a broader truth for the category: consumer confidence in electric pressure washers depends heavily on perceived reliability and clear safeguards. Manufacturers that standardize on integral protection mechanisms, transparent labeling, and traceable quality controls are better positioned to insulate their brands from reputational and liability exposure. In practice, regulatory risk is becoming a design input rather than a post-market afterthought, and companies that embed compliance into product architecture early are likely to face lower retrofitting costs and fewer market interruptions.
Demand-Side Evolution and the New Purchasing Calculus
On the demand side, the market is being reshaped by a blend of practical maintenance needs and discretionary cleaning behavior. Home exterior cleaning remains the largest application context, driven by the visibility of surface wear, seasonal grime accumulation, and the growing preference for DIY approaches that avoid service-call expenses. Car washing and garden or patio maintenance form the next tier of demand, with consumer preferences increasingly influenced by time savings, storage limitations, and the desire for equipment that can transition between tasks without extensive reconfiguration. This multi-purpose expectation is encouraging manufacturers to optimize for quick accessory swaps, adjustable pressure settings, and ergonomic handling, since a single unit that can address multiple surfaces expands its perceived value within the household.
High Pressure Washers Market
Behavioral shifts are also evident in how consumers evaluate and purchase equipment. Retail visibility, digital research, and post-purchase service access increasingly influence brand choice as much as baseline specifications. Buyers are comparing warranty terms, parts availability, and online tutorial support alongside motor type and pressure rating. In this environment, the ability to provide clear guidance on safe operation, appropriate chemical use, and routine upkeep becomes a competitive lever. The commercial opportunity lies in packaging equipment with educational content, maintenance kits, and accessible replacement parts, thereby transforming a transactional sale into a longer-term relationship that reduces premature abandonment of the product and supports repeat purchases of consumables and accessories.
Supply Chain and Cost Structure Pressures
Cost structures across the value chain are being recalibrated by component availability, freight variability, and the capital intensity of battery technology. Electric and battery-powered models are particularly sensitive to cell pricing and electronics supply, which can create uneven margin profiles across product tiers. In response, manufacturers are pursuing design simplification, supplier consolidation, and regional assembly strategies that reduce exposure to single-source dependencies. There is also a growing emphasis on standardizing pumps, motors, and hose interfaces across multiple product lines, which allows firms to aggregate procurement volume and streamline inventory management. The strategic implication is clear: cost competitiveness in this market is increasingly derived from platform discipline and supply chain flexibility rather than from marginal negotiation on individual parts.
At the same time, logistics and after-sales service networks are gaining strategic importance. Because pressure washers are used infrequently but critically, consumers expect timely access to replacement components and practical troubleshooting support. Distributors and retailers that can offer efficient parts fulfillment and knowledgeable service guidance are better positioned to defend margin and foster loyalty. This dynamic is nudging the market toward tighter coordination between manufacturers, channel partners, and service providers, particularly in regions where residential ownership is concentrated and seasonal demand spikes place pressure on inventory and support capacity.
Competitive Landscape and Strategic Positioning
The competitive environment is moderately concentrated, with leading players commanding a combined share that leaves ample room for differentiated challengers and regional specialists. Headquartered in Germany, Alfred Kärcher SE & Co. KG has built recognition around compact electric lines for home and garden use, emphasizing accessibility in entry-level series and an expanding family of horizontal-format models that appeal to storage-conscious consumers. The company’s approach illustrates how a brand can anchor its consumer offering in ease of use, familiar design cues, and a product ladder that bridges routine household cleaning with light hobbyist applications. By maintaining a clear focus on the residential use case, the firm reinforces a reputation for practical reliability and broad retail availability.
Greenworks Tools, based in North Carolina, has strengthened its presence by leaning into battery-powered and electric pressure washers distributed through major retail channels. The company’s strategy highlights the value of aligning product design with the purchasing habits of DIY consumers who expect cordless flexibility, straightforward assembly, and compatibility with broader outdoor power equipment ecosystems. This orientation supports cross-category brand exposure and gives retailers a cohesive narrative around backyard maintenance. In practice, the company’s positioning demonstrates how battery platform consistency and retail accessibility can translate into a recognizable consumer identity, especially among buyers who prefer a unified tool ecosystem over standalone appliances.
FNA Group, operating under Simpson Cleaning in Wisconsin, has carved out a premium residential and commercial electric pressure washer offering that emphasizes durability and a higher-performance perception. The brand’s presence in both consumer and light commercial contexts allows it to borrow credibility from professional-grade expectations while still addressing the home market. This dual orientation is strategically useful because it supports a tiered narrative: entry-level electric units capture convenience-driven buyers, while premium electric models provide a pathway for users who anticipate heavier use or demand more robust construction. The result is a portfolio that can span multiple price points without diluting the core promise of electric reliability.
Mi-T-M Corporation, headquartered in Iowa, has focused on residential and commercial pressure washers that include hot water options and a broader equipment ecosystem. By incorporating temperature control into select offerings, the company addresses use cases where grease removal or Winter-related cleaning tasks benefit from heated flow, differentiating its lineup from standard cold-water consumer units. This specialization illustrates how a manufacturer can expand perceived utility by targeting specific cleaning challenges, thereby creating a reason for consumers and light business operators to choose a more capable machine even at a higher price point.
The landscape is evolving through a combination of consolidation, specialization, and channel-driven new entry. Larger players are expanding their reach by standardizing platforms and acquiring complementary brand equity, while smaller firms are competing through niche features, regional distribution depth, and specialized service arrangements. Trade activity continues to serve as a visible pulse point for the category. Major outdoor product demonstrations and new product showcases, such as the POWERCLEAN® 2026 event scheduled for late 2026, provide a recurring forum where manufacturers introduce refinements in nozzle technology, pump assemblies, and cordless platforms. Similarly, appearances at events like the PPC Pro Show allow suppliers to test market reaction to equipment variations and gauge interest from both retail and light commercial buyers. These gatherings are not merely promotional; they function as timing markers for product launches, channel negotiations, and competitive benchmarking.
Differentiation is increasingly determined by the integration of product design, regulatory readiness, and channel experience. Brands that can offer clear safety certifications, intuitive controls, efficient water usage, and easy parts access are better equipped to command shelf space and sustain consumer confidence. At the same time, the market is not consolidating uniformly; regional preferences, purchasing channels, and use-case priorities create pockets where specialized offerings can thrive. For new entrants, the most viable path is often to identify an underserved combination of power source, accessory ecosystem, or service promise rather than to race directly into the most crowded price segments.
Future Trends and Commercial Implications
Over the next three to five years, one dominant trend will be the continued rebalancing between gas, electric, and battery-powered architectures, shaped less by total displacement than by use-case segmentation. Electric models will strengthen their foothold in semi-urban and suburban households where storage constraints, noise sensitivity, and maintenance simplicity matter, while gas units retain relevance for longer-duration tasks and locations with limited electrical access. Battery-powered lines will expand as runtime and charge-cycle performance improve, but their growth will depend on the ability to lower effective ownership cost through standardized packs, interchangeable batteries across product families, and retail programs that make premium battery hardware accessible. The commercial opportunity lies in designing product families that let consumers upgrade from entry-level electric to battery-capable configurations without replacing the entire system.
A second trend will be the normalization of compliance-oriented feature design. As water conservation rules and electrical safety standards become more visible in local markets, equipment that demonstrates efficient flow, integral protection mechanisms, and clear usage guidance will gain a reputational and practical edge. This creates an opportunity for manufacturers and channel partners to lead with transparency: product materials that explain appropriate use cases, maintenance expectations, and local regulatory compatibility can reduce returns, limit liability exposure, and strengthen retail trust. In markets where aesthetic pressure washing is being restricted, compliant efficiency becomes a selling point rather than a concession.
A third trend will be the shift toward multi-purpose household cleaning systems. Consumers increasingly prefer units that can move between home exteriors, vehicles, and patio or garden surfaces with minimal setup change. This favors designs with quick-connect accessories, adjustable pressure regulation, and accessories that address a range of soils and surfaces. The strategic reward for companies that solve this versatility challenge is higher basket value, stronger repeat purchase potential for attachments and consumables, and reduced competitive vulnerability to single-feature rivals. The uncertainty to watch is the risk of over-engineering: adding features that complicate storage, increase weight, or obscure the core cleaning task can erode the convenience advantage that drives consumer adoption in the first place.
Strategic Guidance for Decision Makers
Manufacturers should prioritize platform discipline and compliance integration as part of the core product roadmap rather than treating them as downstream adjustments. Standardizing pumps, motors, and accessory interfaces across a coherent family of electric and battery-capable models can reduce procurement fragmentation, improve inventory turnover, and make after-sales support more efficient. At the same time, embedding safety and water-efficiency considerations early in the design process can limit retrofit cycles and create a clearer value proposition in regulated markets. Companies that align product messaging with real household use cases—storage footprint, quick setup, maintenance simplicity, and multi-surface versatility—will be better positioned to capture share from generic commodity competition.
Investors evaluating exposure to this market should focus on the companies and segments that demonstrate platform leverage, retail channel strength, and a credible response to regulatory and safety dynamics. Battery platform compatibility, parts accessibility, and the ability to cross-sell accessories are indicators of durable consumer relationships, while reliance on a narrow feature set or a single distribution chute increases vulnerability to competitive pressure and regulatory shifts. Due diligence should also examine how a company manages component cost volatility and whether its product roadmap reflects a realistic balance between performance, safety, and user convenience. Opportunities are likely to accrue to firms that can articulate a differentiated use-case story and execute on service and parts fulfillment as part of the brand experience.
Pressure Washers Market
Procurement and channel leaders should approach sourcing and assortment decisions with an eye toward total cost of ownership and compliance readiness. Evaluating suppliers on the basis of electrical safety design, ease of maintenance, availability of replacement components, and clarity of operating guidance can reduce downstream friction and improve customer satisfaction. Where local water-use restrictions or safety recalls have altered purchasing expectations, assortment plans that emphasize efficient, well-documented equipment can strengthen retailer credibility and reduce exposure to non-compliant products. Building relationships with manufacturers that provide transparent documentation and reliable parts supply will pay dividends during seasonal demand peaks and in post-purchase support scenarios.
The convergence of technology, regulation, and consumer behavior means that the most actionable intelligence is highly segmented and forward-looking. Detailed product-level data, regional demand profiles, and scenario-based forecasts are essential for translating these broad dynamics into specific sourcing, launch, and investment decisions. PW Consulting’s Consumer Pressure Washers Market research report provides that deeper layer of granularity, including segment performance, regional breakdowns, and competitive benchmarking tailored to decision-critical questions. For executives, planning teams, and investors seeking to move beyond market-level overviews into actionable strategy, the full report offers the detailed structure needed to align product, channel, and capital decisions with the trajectory of the market.
For detailed analysis of this topic, please visit the official page: Consumer Pressure Washers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


