



Diesel Fuel Injection Systems Market Gains 5.5% CAGR Amid Regional Power Shifts

Diesel Fuel Injection Systems Market: Navigating the Tipping Point Toward Sustainable Efficiency
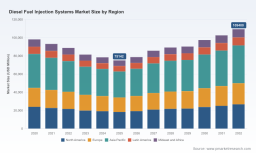
The diesel fuel injection systems market is currently navigating a complex period of structural adjustment. Drawing from historical data spanning 2020 to 2025 and a forecast period extending to 2032, the market exhibits a clear narrative of recent contraction followed by a projected recovery. In 2020, the market revenue stood at approximately $98,208 million. Over the subsequent five years, the sector experienced a steady decline in revenue, reaching a base year valuation of $75,142 million in 2025. This contraction reflects the lingering effects of global supply chain disruptions and the initial phases of regulatory pressure on internal combustion engines.
However, the trajectory shifts markedly from 2026 onward. The market is expected to rebound, growing at a compound annual growth rate (CAGR) of 5.5% through 2032. By the end of the forecast period, revenue is projected to surpass $109,400 million. This growth is not merely a return to pre-pandemic levels but indicates a maturing market where value is derived from higher-performance, precision-engineered systems rather than volume alone. The market remains moderately fragmented, with a top-three concentration ratio of 25.4% and a top-five concentration ratio of 30.5%, suggesting that while dominant players hold significant sway, there is ample room for specialized competitors and niche innovations to capture value.
PW Consulting
These macroeconomic figures provide the backdrop for a deeper investigation into the operational realities facing executives and investors. The following analysis dissects the core challenges, driving forces, and competitive maneuvers defining this sector, offering a strategic lens for decision-making in a transforming landscape.
Market Landscape: The Contraction-Recovery Paradox
The revenue decline observed from 2020 to 2025 masks a critical underlying dynamic: the qualitative evolution of the product mix. While unit volumes may have faced headwinds due to economic fluctuations and the gradual transition toward electrification in light-duty segments, the revenue erosion was partially mitigated by the increasing adoption of high-pressure common rail technologies. As legacy systems are phased out, the average value per unit in the installed base shifts toward more sophisticated injection architectures capable of meeting stringent efficiency and emission targets.
This period of contraction has forced a recalibration of expectations. Market participants who previously relied on steady volume growth are now focusing on margin preservation and technological differentiation. The recovery projected for 2026 and beyond suggests that the market has absorbed the initial shocks of regulatory and economic volatility. The growth phase is driven by the need to retrofit and upgrade existing fleets, the expansion of commercial vehicle markets in high-growth regions, and the continuous push for thermal efficiency in heavy-duty applications where diesel remains the dominant power source.
Key Challenges and Inflection Points
Three critical challenges define the current operational environment and serve as inflection points for strategic planning:
- Regulatory Tightening as a Dual-Edged Sword: Emission standards continue to escalate, requiring precise control over fuel injection timing and quantity. While this drives demand for advanced systems, it also increases the complexity and cost of compliance. Manufacturers must balance the engineering requirements of meeting standards such as EPA and Euro norms with the commercial reality of price-sensitive end markets. Nonconformance penalties further raise the stakes, making reliability and validation paramount.
- Material and Supply Chain Pressures: The trend toward higher operating pressures—exceeding 2,000 bar in many common rail systems—demands components fabricated from high-performance steels and specialized alloys. These materials are subject to price volatility and supply constraints. Any disruption in the availability of critical raw materials can impact production schedules and cost structures, forcing manufacturers to rethink sourcing strategies and inventory management.
- The Electrification Cross-Pressure: The long-term shift toward electrification in passenger cars and light commercial vehicles creates a structural headwind for traditional diesel injection volumes in these segments. Manufacturers must determine how to allocate R&D resources between defending existing diesel markets with incremental improvements and investing in technologies that support alternative fuels or hybrid architectures.
Core Drivers of Market Dynamics
Understanding the recovery trajectory requires a granular look at the forces propelling change. The market is not growing simply due to macroeconomic recovery; it is being reshaped by specific technological, regulatory, and demand-side innovations.
Technological Innovation: The Push for Higher Pressure and Precision
The technical arms race in diesel fuel injection centers on pressure, speed, and control. Leading systems now operate at pressures exceeding 2,500 bar, with some architectures pushing toward 3,000 bar. This is not merely an engineering milestone but a functional necessity. Higher injection pressures improve atomization, leading to more complete combustion, lower particulate emissions, and better fuel economy.
Recent developments highlight this trajectory. For instance, innovations unveiled in 2026 demonstrate a focus on supporting future emissions standards through 500-bar-plus fuel injection capabilities and alternative fuel compatibility. This signals that the industry is preparing for a diversified fuel landscape where diesel injection technology must adapt to new energy carriers while maintaining performance benchmarks. Furthermore, the ability to achieve ultra-fast actuation in injectors allows for multiple injection events per cycle, giving engine control units finer granularity over combustion dynamics. These capabilities are essential for meeting the dual mandates of power output and emission compliance.
Regulatory and Policy Environment: Compliance as a Market Filter
Policy continues to be a primary determinant of market structure. Heavy-duty engines, in particular, are subject to rigorous standards that require optimized fuel injection timing and quantity, often in conjunction with aftertreatment systems. Regulations are not static; they evolve, imposing stricter limits on nitrogen oxides and particulates.
This regulatory environment acts as a filter. It raises the barrier to entry for manufacturers who cannot demonstrate consistent compliance and reliability. At the same time, it creates a sustained demand for upgrade kits and retrofit solutions. The introduction of modular common rail fuel system upgrade kits for legacy engines illustrates how regulators and market needs converge. By converting older high-pressure injection systems with newer components, manufacturers can extend the life of existing assets while achieving efficiency gains, such as the verified 5% improvement noted in recent upgrade initiatives. This trend underscores a market where service and upgrade revenue streams are becoming increasingly relevant alongside new equipment sales.
Diesel Engines Market
Demand-Side Shifts: Commercial Vehicles and Off-Highway Resilience
While passenger car volumes face long-term uncertainty, the demand profile for diesel injection systems is being bolstered by the commercial vehicle and off-highway segments. Heavy-duty trucks, mining equipment, and agricultural machinery rely on the torque, durability, and energy density of diesel power. In these applications, the operational imperative is efficiency and uptime, and advanced injection systems deliver tangible value by reducing fuel consumption and maintenance intervals.
The off-highway sector, in particular, benefits from the ruggedness of modern injection architectures. High-pressure systems designed for extreme operating conditions ensure that engines perform reliably in remote or demanding environments. As global infrastructure projects and mining activities expand, especially in Asia Pacific and other developing regions, the demand for high-performance engines equipped with advanced injection systems remains robust. This demand provides a stable revenue base that cushions the market against volatility in the light-duty segment.
Supply Chain and Cost Structure Evolution
The cost structure of diesel fuel injection systems is undergoing a transformation driven by material science and manufacturing efficiency. The reliance on specialized steels and alloys for components that withstand extreme pressures means that cost management is no longer solely about labor arbitrage. It involves securing resilient supply chains for critical raw materials and investing in advanced manufacturing processes such as precision machining and additive manufacturing for complex geometries.
Diesel Common Rail Injection System Market
Companies are increasingly looking at vertical integration and long-term supplier partnerships to mitigate risk. The ability to control the quality and supply of key components becomes a competitive differentiator. Moreover, as systems grow more complex, the integration of software and sensors adds a new layer to the cost and value equation. The shift from purely mechanical systems to electronically controlled, sensor-rich architectures means that value capture is moving toward intellectual property, calibration expertise, and system-level integration.
Competitive Landscape and Strategic Positioning
The market features a mix of global tier-one suppliers and specialized engine manufacturers with strong fuel system capabilities. The top players have carved out distinct positions based on technology focus, application coverage, and geographic reach.
Bosch remains a dominant force, leveraging its extensive portfolio of common-rail systems with piezo injectors capable of high pressures. Its strength lies in the breadth of coverage across passenger cars, light commercial, and heavy-duty vehicles, supported by a comprehensive fuel supply ecosystem. Bosch's ability to deliver full-system solutions, including pumps and rails, provides a holistic value proposition to OEMs seeking single-source reliability.
Denso Corporation has established itself through its i-ART common rail technology, which integrates advanced control capabilities. Its focus on medium- and large-sized vehicles, with pressures up to 2,500 bar and the integration of SCR and DPF controls, highlights a strategy centered on system-level emissions management. By linking injection performance directly to aftertreatment optimization, Denso offers a solution that addresses the full emission compliance chain.
BorgWarner has expanded its footprint through strategic acquisitions, such as the 2020 acquisition of Delphi Technologies. This move bolstered its portfolio with EUI and DFi7 injectors for heavy-duty and passenger segments, alongside PLD systems. BorgWarner's trajectory reflects a consolidation strategy, using scale to offer a wide array of injection technologies while maintaining the specialized engineering heritage of its acquired units.
PHINIA occupies a strong niche in light- and medium-duty engines, producing injector families and high-pressure pumps that support emissions standards through 3,000 bar operation. Its upcoming focus on 500-bar-plus innovations and alternative fuel support indicates a forward-looking stance, positioning the company to cater to OEMs preparing for evolving regulatory and fuel landscapes.
Cummins Inc. distinguishes itself with deep integration into heavy-duty and mining engines. Its common rail systems, including the Modular Common Rail Fuel System, feature ultra-fast actuated injectors and dual-stage pumps delivering up to 2,600 bar. Cummins emphasizes verified efficiency gains, such as the 5% improvement delivered by its MCRS upgrade kits. This focus on measurable performance outcomes appeals to fleet operators and OEMs in demanding applications where fuel cost and operational efficiency are critical.
Strategies of Leaders and Market Evolution
The strategies of these leaders reveal common themes. First, there is a clear push toward higher pressure and faster actuation, which serves as a technological moat. Second, integration is key; players that can offer injectors, pumps, rails, and control software as a coherent system reduce complexity for customers and lock in value. Third, the ability to support legacy engine upgrades and alternative fuel readiness is becoming a strategic imperative, extending the relevance of diesel injection technology beyond new engine production.
The market is likely to see continued consolidation among smaller players who cannot match the R&D investment requirements of high-pressure systems. At the same time, new entrants may emerge in the form of specialized component suppliers or software-centric firms focusing on injection control algorithms. The moderate concentration ratios suggest that while the leaders hold significant share, the market structure allows for competitive differentiation through niche technologies and regional expertise.
Future Trends and Commercial Opportunities
Looking ahead to the next three to five years, several trends are poised to shape the market and create actionable opportunities.
Trend 1: Retrofit and Upgrade Economy Gains Momentum
As regulations tighten and older fleets face compliance pressures, the market for retrofit solutions will expand. Upgrade kits that convert legacy inline pump systems to modern common rail architectures, increasing injection pressure and accumulator volume, will see growing demand. This trend offers commercial opportunities for manufacturers with strong aftermarket channels and technical support capabilities. It also appeals to operators seeking to extend asset life while meeting emission standards without full vehicle replacement.
Trend 2: Integration of Alternative Fuel Compatibility
Diesel injection systems are not disappearing; they are evolving. The push toward alternative fuels means that injection hardware and control strategies must adapt to different fuel properties. Innovations supporting alternative fuels alongside traditional diesel will become a key differentiator. Companies that develop flexible injection platforms capable of handling multiple fuel types will capture value in a transitioning energy landscape. This trend also opens opportunities for partnerships with fuel producers and alternative energy developers.
Trend 3: Software-Defined Injection and Data Analytics
As electronic control becomes more pervasive, the value of software in optimizing injection timing, quantity, and pressure profiles will grow. Advanced calibration and real-time adaptation based on sensor feedback will drive efficiency gains. This shift creates opportunities for firms that can provide sophisticated control algorithms, diagnostic tools, and data analytics services. The integration of injection data with broader fleet management systems could unlock new value streams, enabling predictive maintenance and performance optimization.
Risks and Uncertainties
Despite the positive outlook, risks remain. The pace of electrification in certain segments could accelerate, eroding long-term demand for diesel systems faster than anticipated. Raw material costs and supply chain disruptions could pressure margins. Regulatory shifts could introduce new compliance requirements that demand rapid redesign cycles. Additionally, geopolitical factors affecting trade and supply routes may impact the availability of critical components. Companies must maintain agility and diversify their technology portfolios to navigate these uncertainties.
Strategic Recommendations for Decision Makers
For executives, investors, and procurement leaders, the current market dynamics call for a proactive and nuanced approach.
For Manufacturers and Technology Developers
- Invest in High-Pressure and Multi-Fuel Platforms: Prioritize R&D in systems that exceed current pressure norms and can accommodate alternative fuels. This ensures relevance as emission standards tighten and energy sources diversify.
- Expand Aftermarket and Upgrade Capabilities: Develop modular upgrade kits and retrofit solutions that allow customers to modernize existing fleets. This creates a recurring revenue stream and strengthens customer relationships beyond the initial sale.
- Strengthen Supply Chain Resilience: Secure long-term agreements for critical materials and explore vertical integration where feasible. Diversify sourcing to mitigate the risk of disruptions in high-performance alloy supply.
For Investors
- Assess Technology Moats and System Integration: Evaluate potential investments based on their ability to deliver high-pressure solutions, integrated system architectures, and software-defined control. Companies with strong IP in piezo actuation or advanced control algorithms are well-positioned for sustained value creation.
- Monitor Retrofit and Commercial Vehicle Exposure: Companies with a strong footprint in commercial vehicles, off-highway applications, and aftermarket upgrade services may offer more stable growth profiles than those heavily reliant on passenger car volumes.
- Watch for Consolidation and Niche Disruptors: The market may see further consolidation among mid-tier players. Simultaneously, look for niche entrants with specialized technologies in areas such as alternative fuel injection or data-driven optimization.
For Procurement and Fleet Operators
- Evaluate Total Cost of Ownership, Not Just Unit Price: Advanced injection systems that offer verified efficiency gains and lower emission compliance costs can deliver significant long-term savings. Consider the impact of fuel savings, maintenance intervals, and regulatory compliance when selecting systems.
- Plan for Fleet Modernization and Retrofits: Assess the compatibility of existing engines with available upgrade kits. Proactive planning for retrofits can help manage compliance timelines and reduce downtime.
- Engage with Suppliers on Long-Term Support: Ensure that suppliers can provide ongoing technical support, calibration services, and parts availability. Strong supplier partnerships are critical for maintaining operational reliability in demanding applications.
As the diesel fuel injection systems market enters a phase of recovery and technological refinement, the landscape offers clear pathways for those who can align their strategies with the driving forces of efficiency, compliance, and adaptability. The interaction between regulatory demands, material science, and system integration continues to reshape value creation in this sector. Decision makers who maintain a close pulse on technology roadmaps, competitive moves, and regional demand shifts will be best positioned to capitalize on the opportunities ahead. For those seeking a comprehensive breakdown of segment trajectories, regional nuances, and granular competitive intelligence, the full suite of detailed research available through PW Consulting provides the depth required to inform precise strategic moves and tailored recommendations.
For detailed analysis of this topic, please visit the official page: Diesel Fuel Injection Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


