



Endoscopy Ultrasound Market: Why 7.1% CAGR Through 2032 Changes Everything

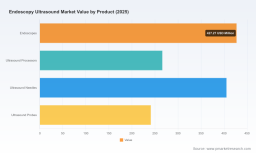
The Strategic Horizon of the Endoscopy Ultrasound Market: Growth, Innovation, and Competitive Positioning
The endoscopy ultrasound (EUS) market stands at a compelling inflection point. Valued at approximately $950 million in 2020, the space has grown to an estimated $1,340 million by 2025, reflecting sustained adoption across diagnostic and interventional gastroenterology. With a forecasted compound annual growth rate of 7.1 percent through 2032, the market is projected to surpass $2,170 million within the decade. This trajectory is not merely a function of clinical demand; it reflects structural shifts in how minimally invasive diagnostics are integrated into care pathways, how imaging hardware evolves, and how reimbursement and regulatory frameworks shape commercial viability. For executives, investors, and procurement leaders, the opportunity lies in recognizing which segments, geographies, and product architectures will compound value over the next five years, and which legacy assumptions are already eroding.
Market Landscape and Core Challenges
A Market Defined by Cross-Sectional Innovation and Procedural Convergence
The EUS ecosystem spans a deliberately integrated product set: echoendoscopes, ultrasound processors, biopsy needles, and specialized probes that together enable high-resolution imaging alongside tissue acquisition and therapeutic intervention. Over the historical period from 2020 to 2025, the market crossed the threshold from niche advanced endoscopy to a more mainstream procedural platform. Growth has been propelled by the convergence of diagnostic clarity and minimally invasive biopsy capabilities, particularly in oncology workups and complex gastroenterology cases. The hardware-software integration model has matured, with processors increasingly serving as the computational backbone that interprets signals from scopes and probes, while needles and accessories define the procedural throughput and clinical yield.
The market’s structure also reveals a concentrated competitive field, with a handful of multinational players holding significant share through established distribution channels, clinical training networks, and proprietary imaging pipelines. This concentration creates both stability and friction: incumbents benefit from installed-base economics and procedural familiarity, while smaller entrants must either differentiate on architecture, cost, or workflow simplification to gain traction.
Three Pressing Challenges Shaping the Near-Term Trajectory
Even as the market expands, several structural challenges are redefining how value is created and captured. The first is the tension between imaging fidelity and procedural efficiency. Clinicians are increasingly unwilling to trade scan time, learning curve, or setup complexity for marginal gains in resolution. The next generation of EUS systems is therefore being judged not only on image quality, but on how seamlessly they integrate into existing endoscopy workflows, how quickly specialists can achieve competency, and how reliably devices can be reprocessed between cases.
PW Consulting Health Care Research Center
The second challenge is the reimbursement and coding environment. EUS procedures rely on standard outpatient coding structures, with payments varying across regions and payer mix. While this provides a baseline pathway for utilization, it also means that adoption is sensitive to procedural coding shifts, outpatient site-of-service economics, and the relative cost burden of disposables versus capital equipment. Vendors and providers alike must navigate the operational reality that revenue generation depends on both clinical value and administrative predictability.
The third challenge lies in regulatory clearance and clinical validation cadence. New devices in this space typically require premarket notifications, and the bar for differentiation increasingly includes not just technical performance but infection-prevention compliance, reprocessing validation, and documented procedural support. This regulatory layer is not a barrier per se, but it does reshape time-to-market dynamics and raises the operational burden for companies introducing novel architectures or accessory ecosystems.
Key Drivers Reshaping the Market
Technology Innovation as the Core Value Multiplier
The most visible driver of market momentum is the continued refinement of imaging and procedural tools. Advanced ultrasound platforms are pushing higher resolution and more structured imaging outputs, while echoendoscopes and linear scopes are being engineered to improve navigation, durability, and image consistency across varied patient anatomies. At the same time, biopsy needles and accessories are evolving toward more reliable tissue acquisition, with designs that emphasize secure sampling and compatibility across procedural use cases. The practical implication is that EUS is increasingly positioned as a single procedural environment where diagnosis, sampling, and in certain cases intervention can be coordinated without disjointed device switching.
Recent product announcements illustrate this trajectory. In May 2026, Olympus introduced the Aplio i800 EUS Premium Ultrasound System in the United States through a partnership with Canon, signaling a continued push toward advanced imaging integration and cross-company engineering collaboration. The same period saw Olympus expand its visible EUS solution set at Digestive Disease Week 2026, reinforcing the message that the company is competing on platform breadth as much as individual hardware. Earlier, in September 2025, Fujifilm launched the Arietta 850 EUS processor alongside its 700 Series linear scopes, emphasizing enhanced image clarity for EUS applications. These moves are not isolated product launches; they are indicators of a competitive posture in which imaging clarity, processor capability, and scope architecture are being optimized together rather than in isolation.
Regulatory and Reimbursement Context as Commercial Architecture
Regulation and reimbursement form the structural scaffolding within which EUS adoption scales. On the regulatory side, new EUS devices typically move through FDA 510(k) clearance pathways, as exemplified by recent premarket notifications for systems such as Olympus’s EVIS EUS ENDOSCOPIC ULTRASOUND CENTER EU-ME3 and EndoSound’s Vision System. This clearance process is a predictable requirement, but it also means that innovation cycles must accommodate not only engineering milestones but documentation, validation, and post-clearance support. The practical effect is that companies with mature regulatory workflows and established quality systems can convert development progress into commercial availability more reliably than those still building compliance infrastructure.
On the reimbursement side, EUS procedures are generally covered under standard outpatient CPT codes, with Medicare national average payments providing a reference point for site-of-service economics. The nuance is that payment variability across payers and settings can influence how aggressively hospitals and ambulatory surgery centers adopt capital-intensive imaging platforms, especially when disposables such as needles add recurring cost. The business implication is that value propositions increasingly need to account for total procedural economics rather than device performance alone.
Demand-Side Shifts Toward Integrated, Minimally Invasive Workflows
Demand is being reshaped by the broader movement toward outpatient, minimally invasive diagnostics and the growing expectation that advanced imaging should support both detection and tissue acquisition. Oncology-related workups and gastroenterology procedures remain central to utilization, and clinicians are looking for platforms that reduce handoffs, shorten setup, and improve reproducibility across operators. This is a subtle but important shift: the purchase decision is increasingly anchored not just by image quality, but by the predictability of the entire procedural flow from insertion to sampling to reprocessing.
Training and on-site application support have become part of the value equation. The availability of certified clinical application specialists who provide EUS training and procedural optimization support is a differentiator for many institutions, especially as new platforms and accessories enter the workflow. In practice, the ability to shorten learning curves and standardize techniques contributes directly to adoption velocity and long-term utilization rates.
Supply Chain and Material Considerations
Behind the clinical narrative, supply chain and material choices are shaping product durability, cost structure, and differentiation. EUS biopsy needles rely on medical-grade materials such as nitinol with multi-layer sheaths to support secure tissue acquisition, and these material decisions influence both performance and unit economics. At the same time, companies that supply ultrasonic components for EUS probes and accessories occupy an important supporting role in the value chain, contributing to imaging consistency and manufacturing scalability. The broader implication is that competitive advantage is not solely defined by brand or platform; it is also shaped by the reliability of component supply, reprocessing compatibility, and the ability to manage recurring accessory economics.
Ultrasound Market
Competitive Landscape and Leading Strategies
Incumbents Competing on Platform Breadth and Ecosystem Integration
The market’s leadership tier is anchored by large, diversified players with the capacity to offer integrated portfolios spanning processors, echoendoscopes, needles, and accessories. Olympus Corporation remains a prominent reference point, with a comprehensive EUS portfolio that includes processors, echoendoscopes, miniature probes, biopsy needles, and advanced imaging systems. Its recent U.S. introduction of the Aplio i800 EUS Premium Ultrasound System in partnership with Canon, along with expanded EUS visibility at Digestive Disease Week 2026, illustrates a strategy centered on strengthening imaging capability while maintaining broad procedural coverage. For institutions already using Olympus ecosystems, this approach reinforces installed-base continuity and clinical training familiarity.
Fujifilm Holdings Corporation has taken a parallel but distinct path, focusing on processor-image clarity improvements and scope architecture. Its launch of the Arietta 850 EUS processor and 700 Series linear scopes at ACG 2025 reflects a design emphasis on high-resolution imaging and procedural consistency. This positions Fujifilm as a strong alternative for sites prioritizing image performance and processor evolution, particularly where imaging clarity is a decisive clinical or purchasing factor.
Boston Scientific Corporation, Medtronic plc, Pentax Medical, and Cook Medical each bring differentiated strengths to the market. Boston Scientific’s emphasis on EUS-guided biopsy systems, needles, and processors aligns with procedural efficiency and tissue acquisition workflows. Medtronic’s offering of EUS endoscopes, needles, and ultrasound-guided interventional tools builds toward a broader interventional orientation. Pentax Medical contributes echoendoscopes and processors for diagnostic and therapeutic applications, while Cook Medical’s portfolio of EUS endoscopes, needles, and stents supports GI intervention. These companies compete not only on product features but on how well their portfolios map to institutional procedure mixes and clinical priorities.
Specialists, Niche Entrants, and the Value of Workflow Disruption
Beyond the broad-portfolio players, the market includes specialists and newer entrants targeting specific friction points. EndoSound, Inc. has developed a Vision System that converts standard upper GI endoscopes into full EUS capability, a concept that directly addresses capital cost and equipment deployment flexibility. This kind of approach appeals to sites seeking to expand EUS access without committing to a fully new scope fleet, and it highlights a competitive dynamic in which software-assisted conversion and modular capability can challenge traditional hardware-centric purchasing.
Worldwide Ultra HD Endoscope Market
Other participants illustrate the breadth of the supporting ecosystem. ConMed Corporation and CONMED Corporation focus on EUS biopsy needles and accessories, where recurring consumable economics and procedural reliability matter. Medi-Globe Corporation, HUACO HEALTHCARE TECHNOLOGIES CO., LTD, and SonoScape Medical Corp. contribute EUS scopes, ultrasound systems, and accessories, expanding regional and value-tier options. B.Braun, Philips, and Smith & Nephew add further depth across needles, systems, and therapeutic products. Steris plc occupies a critical supporting role through endoscope reprocessing and sterilization, reinforcing the operational requirement that EUS devices must be validated for safe reuse. Downstream and upstream component suppliers such as NIHON DEMPA KOGYO CO., LTD also play a meaningful role in enabling probe and transducer performance. Limaca Medical rounds out the landscape with a precision EUS biopsy device concept, reflecting continued experimentation with tissue acquisition optimization.
Market Structure Dynamics: Concentration, Integration, and Selective Entry
With a substantial share concentrated among a limited set of large players, the market’s evolution is likely to be shaped by a mix of integration, selective acquisition, and targeted differentiation rather than uniform fragmentation. Large incumbents will continue to benefit from distribution scale, training infrastructure, and installed-base momentum. At the same time, the presence of companies pursuing modular or conversion-based architectures suggests that differentiation may increasingly come from reducing capital burden, simplifying scope management, or improving accessory economics. The competitive question for the next few years is whether the market rewards broad platform dominance, or whether workflow-specific innovations can carve out durable niches by solving procurement and operational constraints.
Future Trends and Commercial Opportunities
Trend One: Imaging and Procedural Platforms Will Be Judged as Integrated Systems
Over the next three to five years, EUS purchasing is likely to shift further from evaluating discrete components toward assessing how processors, scopes, needles, and support services function as a single procedural system. The practical opportunity for providers and manufacturers is to align product roadmaps with workflow continuity: faster setup, more consistent imaging across operators, and accessories that integrate cleanly into sampling workflows. Companies that can demonstrate measurable improvements in procedural predictability, training efficiency, and reprocessing compliance will have stronger positioning than those competing only on headline image quality.
A related commercial opportunity lies in total-cost and utilization framing. As sites balance capital equipment decisions against recurring disposable costs, vendors that offer transparent economics, reliable accessory supply, and on-site application support will be better positioned to influence long-term procurement. The risk to watch is over-indexing on advanced features without corresponding gains in ease of use or consumable efficiency, which can slow adoption in cost-sensitive outpatient settings.
Trend Two: Reimbursement Logic and Site-of-Service Economics Will Shape Adoption Patterns
Because EUS procedures are embedded in standard outpatient coding and payment structures, adoption will continue to be sensitive to site-of-service economics and payer mix. As more procedures move to ambulatory and outpatient environments, the relative economics of capital equipment, disposables, and procedural throughput will matter more than ever. This creates an opportunity for vendors and providers to develop more explicit value narratives that connect clinical outcomes with operational efficiency and reimbursement predictability.
The uncertainty here is that coding and payment environments are not static. Shifts in outpatient reimbursement practice, regional payment variation, and the cost profile of needles and accessories can influence how quickly new platforms are deployed or refreshed. Companies and buyers that monitor coding and payment dynamics closely will be better prepared to anticipate adoption cycles and plan capacity accordingly.
Trend Three: New Entrants Will Pressure Legacy Assumptions Around Capital and Access
The emergence of systems that convert standard scopes into EUS-capable platforms, alongside continued experimentation in biopsy device design, suggests that the market will see ongoing pressure to reduce capital intensity and broaden access. This does not eliminate the role of full-featured dedicated systems, but it does introduce more choice for institutions that want to expand EUS capability without full fleet replacement. For innovators, the opportunity is to prove that converted or modular approaches can deliver reliable imaging and sampling performance with predictable reprocessing and support requirements.
The associated risk is that performance, durability, and clinical confidence must be demonstrated consistently. New architectures that appear attractive on cost must still meet regulatory clearance expectations, reprocessing validation standards, and the clinical workgroup expectations that drive sustained utilization. The market will likely reward entrants that combine economic appeal with credible validation and visible procedural support.
Strategic Recommendations for Decision Makers
For Manufacturers and Platform Providers
Position product roadmaps around integrated procedural value rather than isolated specifications. That means aligning processor imaging, scope design, and needle/accessory performance with training, reprocessing, and support economics. Where possible, differentiate by shortening the learning curve, improving consistency across operators, and demonstrating total procedural efficiency. For companies with broad portfolios, reinforce installed-base continuity through clear upgrade paths and application support. For smaller or more specialized entrants, focus on a defined point of friction—such as capital reduction, modular capability, or accessory reliability—and build a credible evidence and support package around it.
For Investors and Strategic Allocators
Evaluate companies based on their ability to convert innovation into predictable commercial availability and repeat utilization. Regulatory competence, application support infrastructure, and supply chain reliability for consumables are not secondary details; they are part of the execution equation that determines whether a product gains traction. Pay attention to players that are strengthening imaging partnerships, expanding processor capabilities, or pursuing modular approaches, while also assessing the durability of their reimbursement and reprocessing assumptions. Diversification across the ecosystem—including processors, scopes, needles, and reprocessing support—can provide a more complete view of where value is likely to compound.
For Procurement Leaders and Clinical Administrators
Structure evaluation criteria around total procedural workflow, not just image performance or list price. Consider how a platform affects training timelines, reprocessing compliance, accessory availability, and the economics of recurring disposables. Where capital constraints are significant, assess whether modular or conversion-based solutions can deliver the required clinical capability with lower deployment burden, provided they meet clearance and validation requirements. Ensure that procurement decisions are linked to a clear plan for clinical application support and staff competency development, since adoption velocity often depends on these operational factors as much as hardware selection.
Closing Perspective
The endoscopy ultrasound market is expanding on the back of imaging refinement, procedural integration, and sustained demand for minimally invasive diagnostics, but the most valuable insights for decision makers lie in how these forces interact. Future advantage will belong to organizations that treat EUS as a workflow system, manage reimbursement and reprocessing realities with discipline, and differentiate in ways that are both clinically credible and operationally efficient. For executives and investors seeking deeper segmentation detail, competitive profiling, and customized commercial guidance, the full PW Consulting market report provides the granularity needed to translate these trends into precise, actionable strategy.
For detailed analysis of this topic, please visit the official page: Endoscopy Ultrasound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


