



Prostaglandin Market: Why 6.5% CAGR and Clinical Shifts Change Everything

Navigating the Prostaglandin Market: Strategic Trends and Commercial Opportunities in a Transforming Landscape
The prostaglandin market is entering a phase of structural transformation. Over the historical period from 2020 through 2025, global revenue expanded from approximately $3.3 billion to $4.47 billion, reflecting steady demand growth across therapeutic categories and geographic markets. Looking ahead to the 2026–2032 forecast window, the market is projected to continue its upward trajectory, reaching an estimated $6.9 billion by 2032 with a compound annual growth rate of 6.5 percent. This growth rate places prostaglandins above many traditional generic pharmaceutical segments and signals sustained commercial relevance for manufacturers, buyers, and investors alike.
Beneath these headline figures lies a market defined by concentration, regulatory friction, and rapid innovation in formulation and delivery. The top three competitors currently capture roughly 58.5 percent of total revenue, while the top five account for about 68.2 percent. Such concentration indicates that scale, supply reliability, and regulatory expertise remain powerful moats, yet it also suggests that targeted entrants with differentiated capabilities can still carve out meaningful positions. The next several years will reward organizations that can read the shifting demand signals, navigate cost pressures, and align product strategies with evolving clinical and reimbursement realities.
Market Context: What the Numbers Reveal and What They Conceal
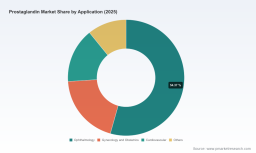
The size and trajectory of the prostaglandin market reflect more than incremental volume growth. The steady expansion from 2020 to 2025 was underpinned by consistent utilization in ophthalmology, ongoing demand in gynecology and obstetrics, and a mature but resilient cardiovascular segment. The projected climb toward 2032 indicates that the market is not merely catching up from a temporary slowdown but is benefiting from durable therapeutic relevance and incremental innovation in delivery formats.
At the same time, the concentration profile tells a story of distributed value chains. A relatively small group of large-scale players commands the majority of revenue, yet the broader ecosystem includes specialized API producers, formulation-focused companies, catalyst and intermediate suppliers, and reagent distributors. This structure creates both stability and vulnerability. Buyers benefit from multiple sourcing options, but the reliance on a concentrated set of suppliers for critical inputs introduces risk when regulatory, geopolitical, or operational disruptions occur.
Key Challenges and Inflection Points
Three challenges stand out as particularly consequential for market participants.
- Supply chain concentration and tariff exposure. A substantial share of global API production for prostaglandin analogs is concentrated in India and China, making Western manufacturers and distributors dependent on these sources. Recent tariff actions on Chinese pharmaceutical imports have raised landed costs and introduced new uncertainty around sourcing economics. Organizations that have not diversified or reconfigured their supply chains face margin pressure and continuity risk.
- Regulatory divergence across applications. Regulatory scrutiny is intensifying in specific use cases, particularly where prostaglandin analogs intersect with consumer-facing or semi-consumer products. A recent European Chemicals Agency opinion raised safety concerns around reproductive toxicity for cosmetic lash serums, creating reformulation requirements and channel-specific disruption. This illustrates how a single regulatory signal can cascade across supply chains, even when the core pharmaceutical indications remain unaffected.
- Reimbursement and access dynamics in high-value procedures. The introduction of new reimbursement pathways for certain intravitreal and intracameral delivery procedures demonstrates that payment policy can accelerate or delay adoption of advanced formulation technologies. While positive reimbursement updates can unlock volume, the timing and scope of coverage vary by market, creating uneven commercialization opportunities across regions.
Core Drivers Shaping the Market
The prostaglandin market is being reshaped by four interlocking drivers. Together, they determine which companies gain share, which supply chains remain resilient, and where the most attractive commercial opportunities emerge.
1. Technological Innovation in Production and Delivery
Innovation is advancing on two fronts: how prostaglandins are made and how they are delivered to patients. On the production side, recent scientific progress has demonstrated improved de novo synthesis of prostaglandin F2α from glucose using engineered microbial strains. This type of bioscience-driven manufacturing has the potential to complement traditional chemical synthesis, offering greater efficiency, reduced dependency on complex intermediate steps, and new options for scale. Even where fermentation-based routes are not yet the dominant commercial standard, the direction of travel is clear: manufacturability is increasingly tied to biological and process engineering capabilities.
On the delivery side, the most visible commercial momentum is coming from sustained-release and intracameral technologies in ophthalmology. Recent regulatory approvals supporting re-administration of intracameral implants, alongside new fixed-dose combination eye drops that pair prostaglandin analogs with beta-blockers, reflect a broader push toward convenience, adherence, and differentiated therapeutic positioning. These formats do more than add product variants; they redefine the value proposition by extending duration of action and simplifying treatment regimens. For manufacturers, the opportunity lies not only in active ingredient supply but in enabling technologies, formulation expertise, and compatible delivery systems.
2. Policy and Regulatory Environment
Regulatory policy is simultaneously a constraint and a catalyst. Tariff expansions on certain pharmaceutical imports have increased cost pressure on API sourcing, prompting manufacturers to reassess exposure to specific geographies and to evaluate alternative supply routes. At the same time, regulatory decisions in adjacent application areas can reshape demand quickly. The European Chemicals Agency’s position on cosmetic lash serums, for example, underscores that prostaglandin-related molecules are subject to broader scrutiny when used outside strictly controlled pharmaceutical contexts. Companies that treat regulatory risk as narrowly confined to approved drug indications may miss upstream and downstream consequences that affect raw material sourcing, labeling, distribution channels, and product strategy.
On the positive side, reimbursement developments can create meaningful access advantages. Updated payment policies for certain procedural codes associated with intracameral implants have supported the economics of advanced delivery approaches in specific settings. Such changes can improve adoption trajectories and make novel formulations more commercially viable, especially when aligned with favorable clinical outcomes and clear administration protocols.
3. Demand-Side Changes in Clinical and Commercial Behavior
Demand for prostaglandins continues to be driven by established therapeutic needs, but the nature of that demand is evolving. In ophthalmology, clinicians are increasingly focused on adherence, tolerability, and long-term management, which favors products that reduce dosing frequency or simplify combination therapy. In gynecology and obstetrics, prostaglandin utilization remains tied to well-defined procedural and therapeutic protocols, with demand influenced by clinical guidelines, training, and hospital procurement patterns. Across cardiovascular applications, the market reflects mature usage with ongoing reliance on prostaglandins in specific acute and specialized settings.
A broader demand-side shift is also visible in the way end users evaluate products. Buyers increasingly weigh supply resilience, regulatory clarity, and formulation differentiation alongside price. This is especially true in segments where procurement teams are managing multiple risk layers at once, from API availability to product-specific regulatory status. The practical implication is that value propositions are expanding beyond cost per unit to include reliability, documentation, and the ability to support downstream compliance and patient access.
4. Supply Chain and Cost Structure Transformation
Cost structures are being reshaped by geography, input availability, and the economics of advanced manufacturing. Because a large proportion of API production is clustered in India and China, global markets are exposed to both pricing advantages and concentration risk. Tariff actions have further complicated the cost equation for importers, making it more important to model landed costs realistically and to consider where value can be captured through process efficiency, vertical integration, or alternative sourcing.
At the same time, the cost frontier is shifting through innovation. Improved fermentation routes, catalyst optimization, and better intermediate management can alter unit economics over time, especially for high-volume or high-purity requirements. Companies that can integrate production steps more effectively, or that can secure dependable access to critical intermediates and catalysts, may be able to offset external cost pressures and improve margin stability. In a market where several players compete on similar active ingredients, cost structure and supply reliability can become decisive differentiators.
Competitive Landscape: Positioning, Differentiation, and Evolution
The prostaglandin market features a layered competitive structure. Large multinational pharmaceutical organizations participate through API manufacturing and formulation capabilities, while specialized producers focus on prostaglandin synthesis, analogs, APIs, and related intermediates or reagents. This mix creates multiple pathways to value, but it also means that competitive advantage depends heavily on the specific segment a company serves and the customer problems it solves.
Strategic Positioning Across the Value Chain
Several patterns emerge when looking at how leading participants position themselves.
PW Consulting
- Integrated API and formulation players tend to derive advantage from scale, quality systems, and the ability to support both human and veterinary applications. Companies with established manufacturing infrastructure can compete on reliability and breadth of capability, which is particularly valuable when buyers are seeking to consolidate suppliers or reduce qualification burden.
- Specialized synthesis and fine chemical producers compete on technical precision, purity, and the ability to serve demanding pharmaceutical and research requirements. For these firms, differentiation often comes from process know-how, consistent batch quality, and responsiveness to custom specifications.
- Catalyst and intermediate suppliers occupy a critical enabling role. While they may not be visible to end customers in the same way as API or formulated-product manufacturers, they influence cost, yield, and supply continuity across the value chain. Strong positions in this layer can create indirect competitive leverage.
- Regional and emerging-market manufacturers are increasingly relevant because of capacity, cost positioning, and growing technical competence. Their strategic importance is magnified by the concentration of global API production and by the need for diversified sourcing.
- Research and reagent suppliers serve a different but important demand pool, supporting R&D, quality testing, and preclinical work. This segment may be smaller in revenue terms, but it can shape downstream product development and reinforce technical ecosystems around prostaglandin use.
How the Landscape Is Evolving
Three forces are shaping the evolution of the competitive field. First, supply chain reconfiguration is encouraging a pragmatic mix of consolidation and diversification. Some buyers are seeking to reduce exposure to concentrated sourcing by qualifying additional suppliers or shifting portions of demand to alternative regions. Others are moving in the opposite direction by deepening relationships with suppliers that can demonstrate robust reliability and regulatory readiness. The net effect is a more selective market in which trust, documentation, and operational track record matter as much as price.
Second, product differentiation is becoming more important as the market matures. Fixed-dose combinations, sustained-release implants, and analog-based formulations illustrate how innovation can create space for competitive distinction even when the underlying molecule class is well established. Companies that can combine API or synthesis competence with formulation insight, delivery compatibility, and clinical-commercial alignment are better positioned to capture premium value.
Third, the entry and expansion dynamics are being influenced by cost pressures and capability gaps. New entrants and expanding players are likely to focus on niches where they can offer a clear advantage: specialized synthesis, cost-competitive API supply, unique intermediates, or targeted formulation support. Broad-based competition remains intense among established players, but the most attractive openings increasingly require a focused value proposition rather than undifferentiated capacity.
Worldwide Prostaglandins and Related Drugs Market
Looking Ahead: Three Trends to Watch Over the Next 3–5 Years
Based on current market dynamics, the following trends are likely to shape commercial outcomes through the end of the decade and into the early 2030s.
Trend 1: Supply Chain Realignment and Multi-Sourcing as Baseline Strategy
The combination of geographic concentration and tariff-related cost pressure is accelerating a shift toward deliberate multi-sourcing and regional diversification. Over the next few years, organizations are likely to treat supply resilience as a core commercial requirement rather than a contingency plan. This will favor suppliers that can demonstrate consistent quality, transparent sourcing, and the capacity to support qualified alternative routes. It may also encourage more regional manufacturing investment, or at least stronger contractual and operational integration with key upstream partners.
Commercial implication: supply reliability and regulatory readiness will increasingly be priced into relationships. Companies unable to support credible diversification will face growing procurement friction, while those that can document resilience and scale will gain negotiating leverage.
Trend 2: Formulation and Delivery Innovation as the Primary Growth Lever in Key Segments
While volume growth in mature indications provides a stable base, the most visible upside is coming from differentiated delivery and combination therapies, especially in ophthalmology. Sustained-release implants, intracameral approaches, and combination drops are examples of formats that can improve adherence and clinical convenience while creating new commercial entry points. As these formats become more widely adopted, demand for compatible APIs, formulation support, and delivery-enabling technologies will increase.
Worldwide Dienogest Market
Commercial implication: companies that remain focused solely on commodity-style active ingredient supply may see margin and differentiation erode. Those that can align with advanced delivery strategies—through synthesis quality, scale, formulation partnerships, or integrated offerings—will be better positioned to capture value from format-driven growth.
Trend 3: Regulatory Scrutiny Expanding Beyond Core Pharmaceutical Indications
The prostaglandin opportunity set is not confined to approved drug products, and regulatory attention is already extending into adjacent categories. Cosmetic and semi-consumer applications represent one visible area of scrutiny, but the broader lesson is that product classification, intended use, and supply chain labeling can affect market access and risk exposure. Over the next several years, this may lead to more conservative positioning in borderline applications, more rigorous documentation requirements, and greater emphasis on end-use clarity across the value chain.
Commercial implication: organizations operating across multiple application channels need to separate pharmaceutical and non-pharmaceutical strategies carefully, anticipate reformulation or channel restrictions, and avoid assumptions that regulatory outcomes in one segment will remain isolated from others.
Strategic Implications by Stakeholder Type
The prostaglandin market offers distinct strategic priorities depending on a company’s role in the value chain.
For Manufacturers and Suppliers
- Evaluate supply chain exposure honestly, especially where dependence on concentrated API sources or tariff-sensitive import routes creates cost and continuity risk. Model alternatives, qualify candidates, and stress-test continuity scenarios.
- Invest in process and formulation capabilities that support advanced delivery formats. Even when the core molecule is familiar, the ability to meet the quality, purity, and compatibility requirements of sustained-release or combination products can open higher-value positions.
- Clarify application-channel strategy. Where a company serves both pharmaceutical and adjacent categories, ensure that regulatory positioning, documentation, and end-use claims are aligned with evolving scrutiny and do not create unintended exposure.
For Investors
- Focus on companies with defensible cost structures and credible diversification strategies. In a market where external cost shocks and sourcing concentration create volatility, resilience is a meaningful indicator of long-term performance potential.
- Look for exposure to formulation and delivery innovation rather than assuming growth will come only from volume expansion in mature indications. Businesses connected to advanced delivery technologies and combination approaches may capture more durable value.
- Assess regulatory and reimbursement alignment as part of the investment thesis. Positive payment policy developments can accelerate adoption, while adverse regulatory signals in adjacent channels can affect demand and restructuring costs.
For Procurement and Commercial Buyers
- Prioritize supplier qualification on the basis of reliability, regulatory readiness, and the ability to support alternative sourcing if needed. In a concentrated but dynamically shifting market, the cheapest option is not always the lowest-risk option.
- Build transparency into specifications and end-use requirements. Clear documentation of intended use and quality expectations helps reduce downstream compliance risk and supports more predictable supplier relationships.
- Monitor reimbursement and clinical adoption signals in high-value segments. Changes in procedure-based payment policies and adoption of new delivery formats can materially affect volume trajectories and supplier demand patterns.
Why Now Is the Moment for Deeper Intelligence
The prostaglandin market is not simply expanding; it is reconfiguring around supply chain geography, regulatory pressure, and delivery-format innovation. That combination means the most valuable decisions are increasingly specific: which supplier relationships to deepen, which application channels to prioritize, how to position against tariff and sourcing risk, and where to invest in capabilities that support advanced formulations. Broad market sizing alone does not answer those questions.
Detailed segment-level data, supplier benchmarking, regional cost modeling, and scenario analysis can materially improve strategic planning in this environment. Organizations that rely on high-level aggregates risk missing the operational and regulatory nuances that determine margin, continuity, and competitive positioning. A more granular view also helps identify where concentration risk is manageable and where it is structural, as well as where emerging technologies and reimbursement changes are likely to alter demand faster than the base forecast implies.
For executives, strategists, and investors seeking to move from general market awareness to actionable planning, the next step is to connect these trends with company-specific exposure and opportunity. A comprehensive research report can provide the detailed segmentation, competitive profiling, and forward-looking scenarios needed to support procurement strategy, investment prioritization, and product-roadmap decisions. Given the pace of regulatory and supply chain change, the value of current, granular intelligence is highest before major sourcing or investment commitments are locked in.
For detailed analysis of this topic, please visit the official page: Prostaglandin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


