



Modified Starch Market Outlook: Why 3.5% CAGR and Food Demand Reshape Growth

Strategic Trends and Commercial Opportunities in the Modified Starch Market: A 2025 Perspective
Market Current State and Core Challenges
The modified starch market has established itself as a foundational ingredient segment across multiple industrial and consumer-facing sectors. Over the historical period from 2020 to 2025, the market expanded from approximately 10.5 billion USD to 13.7 billion USD, reflecting steady demand across food processing, paper manufacturing, textiles, and animal feed applications. Forward-looking projections through 2032 indicate continued growth, with revenue expected to reach 17.17 billion USD. The compound annual growth rate over the forecast horizon of 2026 to 2032 stands at 3.5 percent, a trajectory that signals resilience but also underscores the importance of strategic positioning in a maturing landscape.
Market structure reveals a moderately concentrated environment, with the top three players accounting for 35 percent of revenue and the top five capturing 45 percent. This concentration pattern suggests that incumbents enjoy meaningful scale advantages in sourcing, formulation expertise, and distribution networks, yet sufficient fragmentation remains to allow specialized or regional players to compete on functionality, price, or supply reliability. The regional distribution of revenue reflects a globally dispersed supply-demand matrix, with Asia Pacific contributing the largest share, followed by North America and Europe. Such geographic spread creates both opportunities for localized production strategies and vulnerabilities to regional supply disruptions.
Key Challenges and Inflection Points
The current market environment presents several structural challenges that demand strategic attention. First, raw material price volatility has intensified, particularly for tapioca starch, where continuous upward pricing trends and tightening supply were observed toward the end of 2025 and into early 2026, reaching 490 USD per ton. This dynamic pressures cost structures across applications that rely on tapioca-based modification and forces manufacturers to reconsider sourcing diversification and contract structures.
Second, regulatory evolution is reshaping formulation strategies. In the European Union, HS Code 35051090 for modified starches has been subject to CN refinements and duty adjustments effective in 2025, altering trade cost calculations for cross-border transactions. Simultaneously, 2025 updates to FDA labeling guidelines have increased demand for label-friendly modified starches that do not require an E-number or complex chemical name, pushing formulators toward cleaner ingredient narratives. Additionally, 2025 US tariffs on modified starch products have had a direct price impact on imports, creating cost asymmetries that favor domestic production or alternative sourcing corridors.
Corn Starch Market
Third, the market is approaching an inflection point in application mix. While food and beverages remain the dominant end-use category, industrial and non-food applications such as paper, textiles, and adhesives continue to absorb a significant share of modified starch volumes. The strategic question for participants is whether to deepen specialization in high-margin food-grade functionality or to build resilient industrial-grade supply chains that benefit from broader demand diversification.
Key Drivers of Market Change
Technological Innovation and Formulation Breakthroughs
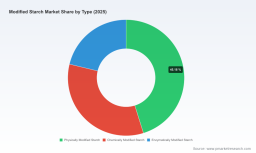
Innovation in modification techniques continues to expand the functional envelope of starch-based ingredients. Physical, chemical, and enzymatic modification pathways each offer distinct performance profiles, with physically modified starch currently commanding the largest share of the type segmentation, followed by chemically modified and enzymatically modified variants. Enzymatic approaches are gaining attention for their ability to produce cleaner ingredient profiles and more tailored functional outcomes, aligning with cleaner-label expectations in food applications.
Recent product-level developments illustrate the pace of innovation. In March 2025, Cargill highlighted a first-of-its-kind dent-corn modified starch designed to improve sauce color and texture, alongside a pectin replacer. This launch underscores a broader trend toward multifunctional ingredients that can replace more expensive or less label-friendly alternatives while preserving or enhancing sensory performance. For manufacturers, such innovations reduce formulation complexity and open opportunities to respond to consumer preferences for simpler ingredient lists without sacrificing product quality.
Policy and Regulatory Environment
Regulatory dynamics are acting as both a constraint and a catalyst. The EU CN refinements for modified starches influence duty structures and administrative compliance for exporters and importers, requiring closer attention to classification accuracy and trade documentation. In parallel, FDA labeling updates have elevated the importance of ingredient nomenclature, encouraging suppliers to develop modified starches that can be presented in a label-friendly manner. These regulatory shifts are not merely compliance issues; they affect product positioning, customer education, and the relative attractiveness of modified starches versus alternative thickeners, stabilizers, and texturizers.
Trade policy further complicates the landscape. Tariff actions on modified starch products have impacted import pricing, creating localized cost advantages for domestic producers and prompting re-evaluation of supply chain geography. Companies that can align sourcing, manufacturing, and distribution with the prevailing regulatory and tariff environment will be better positioned to manage margin pressure and maintain competitive pricing.
PW Consulting Health Care Research Center
Demand-Side Shifts in Consumer and Business Behavior
On the demand side, food and beverage manufacturers continue to drive the largest portion of modified starch consumption, reflecting the ingredient's versatility in thickening, stabilizing, and texturizing applications. Consumer preferences for cleaner labels, plant-based formulations, and improved texture have reinforced the relevance of modified starches as functional solutions that can meet multiple objectives simultaneously. In industrial contexts, paper and textile manufacturers rely on modified starches for binding, coating, and finishing functions, where performance consistency and cost efficiency remain decisive.
Trade show activity in late 2025 highlighted the intensity of demand-side engagement. SMS Corporation unveiled high-performance modified starch solutions at Fi Europe 2025 and, in November 2025, presented modified tapioca starch innovations while winning Plant-Based Manufacturing of the Year at Gulfood Manufacturing 2025. These developments indicate that suppliers are actively aligning product portfolios with plant-based and performance-driven demand, while also using industry events to validate innovation and build commercial relationships.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by raw material price movements and regional supply tightness. The tapioca starch price trajectory toward 490 USD per ton illustrates how concentrated supply conditions can rapidly alter input economics for modification producers. In parallel, U.S. potato starch export prices in 2025 ranged from 0.40 USD per kg to 5.74 USD per kg, reflecting wide variability tied to quality, grade, and destination market conditions. Such variability rewards suppliers with diversified feedstock portfolios and flexible formulation capabilities that can shift between corn, wheat, potato, tapioca, and pea sources depending on availability and economics.
The supply chain implications extend beyond raw material procurement. Logistics, trade compliance, and regional production footprints are increasingly important determinants of total delivered cost. Companies that invest in supply chain transparency, multi-source sourcing, and regional manufacturing capacity can mitigate exposure to single-commodity shocks and tariff-driven price distortions, while also improving responsiveness to customer demand cycles.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
The competitive field includes a mix of global ingredient corporations and specialized regional producers. Cargill, headquartered in Minneapolis, produces and supplies modified starches for personal care, food and beverage, and industrial applications, emphasizing grades with stable viscosity and functional benefits. Ingredion Incorporated, based in Westchester, Illinois, manufactures modified food starches and industrial starches for texturizing, thickening, and stabilizing across food, beverage, and non-food applications. Roquette Frères, located in Lestrem, France, is a global producer of native and modified starches from multiple sources including corn, wheat, potatoes, tapioca, and peas, offering over 300 modified starch variants. Tate & Lyle PLC, headquartered in London, supplies modified starches and starch derivatives for food and beverage, with clean-label and specialty portfolios. These global players derive competitive advantage from broad feedstock access, application laboratories, and established customer relationships across multiple sectors.
Regional and specialized manufacturers add important diversity to the landscape. Premier Starch, based in Bengaluru, India, manufactures modified starches, dextrins, and corrugation adhesives for packaging, paper, paints, abrasives, and mining industries. Angel Starch & Food Pvt. Ltd., also in India, produces modified starches for textile binders, thickeners, emulsifiers, stabilizers, and functional food ingredients. Jay Dinesh Chemicals, with over 50 years of experience in chemical modification processes, manufactures and exports modified starch from India. Vinayak Ingredients provides modified starches derived from maize, cassava, or potato for food additives and industrial use. SMS Corporation Company Limited, headquartered in Thailand, is a global manufacturer and distributor of premium modified tapioca starch for food, pharmaceutical, nutraceutical, paper, adhesive, construction, and textile applications. Grain Processing Corporation, located in Muscatine, Iowa, produces modified starches including acid-modified, oxidized, pregelatinized, and cationic types for industrial and food applications. AEBE U.A., based in the Netherlands, manufactures modified starches for food and industrial sectors. Global Bio-Chem Technology Group Company Limited, a Chinese producer, supplies modified starch products for food and industrial use. SPAC Starch Products India Private Limited manufactures advanced modified starches from maize, corn, and tapioca sources for industrial applications.
Strategic Differentiation and Competitive Evolution
Leading strategies in this market tend to cluster around three pillars: feedstock flexibility, application-specific functionality, and regulatory-aware formulation. Global incumbents leverage multi-source starch portfolios to balance cost and performance across regions, while also maintaining dedicated food-grade and industrial-grade lines. Specialist producers often compete by deepening expertise in particular applications or modification types, offering tailored solutions that address specific processing conditions, label requirements, or regional price dynamics.
The market is simultaneously experiencing consolidation pressures and fragmentation opportunities. Concentration among the largest players reflects the advantages of scale in R&D, quality systems, and global distribution, yet the continued presence of numerous regional manufacturers indicates that local responsiveness, niche functionality, and price competitiveness remain viable differentiation paths. New entrants and expanding regional players can gain traction by focusing on underserved applications, developing cleaner-label modification profiles, or building reliable supply in regions where imported modified starches face tariff or logistics headwinds.
Recent activity among leading companies confirms the emphasis on innovation and market engagement. SMS Corporation's trade show participation in late 2025, including the unveiling of high-performance modified starch solutions at Fi Europe 2025 and the recognition at Gulfood Manufacturing 2025, illustrates how suppliers use visible innovation and industry recognition to strengthen positioning in food and industrial segments. Cargill's March 2025 product innovation further demonstrates the ongoing push toward differentiated functionality that supports label-friendly reformulation and sensory improvement.
Potato Starch Market
Future Trends and Commercial Opportunities
Trend 1: Cleaner-Label and Functionally Efficient Modified Starches
Over the next three to five years, demand for label-friendly modified starches is likely to intensify, driven by labeling guideline updates and consumer expectations for simpler ingredient statements. Commercial opportunities will arise for suppliers that can deliver stable viscosity, thickening, and texturizing performance without relying on nomenclature that complicates label readability. Formulations that can replace pectin, gum, or other more expensive or less desirable ingredients while maintaining sensory quality will be particularly valuable in food and beverage applications. The risk here lies in balancing clean-label positioning with performance consistency; manufacturers must ensure that cleaner ingredient narratives do not erode the functional reliability that customers depend on.
Trend 2: Regional Sourcing and Supply Chain Reconfiguration
Tariff impacts, raw material price volatility, and regional supply tightness are expected to accelerate reconfiguration of supply chains. Companies may increasingly favor regional production footprints, diversified feedstock sourcing, and long-term supply agreements that reduce exposure to single-commodity shocks. Opportunities exist for producers that can offer reliable delivery, transparent cost structures, and flexibility across starch sources such as corn, potato, tapioca, wheat, and peas. The key uncertainty is the trajectory of trade policy and commodity markets; shifts in tariff regimes or unexpected supply disruptions could alter the economics of regional versus cross-border supply strategies.
Trend 3: Industrial and Non-Food Diversification with Performance Focus
While food and beverages remain the largest application segment, industrial uses in paper, textiles, adhesives, and related sectors provide demand diversification and volume stability. Over the forecast period, opportunities will likely emerge for modified starches that deliver consistent binding, coating, and finishing performance at competitive cost, especially where manufacturers seek alternatives to more expensive synthetic additives. The risk is that industrial demand can be sensitive to macroeconomic cycles and substitution pressures; suppliers will need to manage capacity and pricing dynamically to preserve margins during demand fluctuations.
Actionable Guidance for Decision-Makers
For Manufacturers and Ingredient Suppliers
- Strengthen feedstock diversification and formulation flexibility to respond to raw material price volatility and regional supply tightness, particularly for tapioca and potato-based inputs.
- Invest in label-friendly and multifunctional modification profiles that align with evolving FDA and EU expectations, enabling customers to simplify ingredient statements while maintaining performance.
- Use application-level expertise and visible innovation, including trade show engagement and targeted product launches, to differentiate from both global incumbents and regional competitors.
For Investors
- Evaluate exposure to regulatory and tariff dynamics across key regions, recognizing that classification refinements, duty adjustments, and import tariffs can materially affect cost structures and competitive positioning.
- Prioritize companies with diversified feedstock access, application breadth, and the ability to shift between physical, chemical, and enzymatic modification pathways as customer requirements evolve.
- Monitor concentration trends and consolidation potential; while the market remains moderately concentrated, specialized players with strong application niches or regional supply advantages may present attractive value creation pathways.
For Procurement and Supply Chain Leaders
- Build multi-source sourcing strategies that reduce dependence on single starch types or single-origin suppliers, improving resilience against price spikes and supply tightness.
- Align supplier selection with regulatory-aware ingredient profiles, ensuring that modified starch choices support label objectives and trade compliance requirements in target markets.
- Incorporate total delivered cost, including logistics and tariff implications, into sourcing decisions rather than relying solely on ex-works pricing, especially when cross-border trade is involved.
Conclusion
The modified starch market is entering a phase where steady growth coexists with meaningful structural change. Raw material volatility, regulatory updates, and trade policy shifts are reshaping cost and compliance dynamics, while innovation in functionality and cleaner-label formulation is opening new commercial pathways. Companies that combine feedstock flexibility, application-specific expertise, and supply chain resilience are best positioned to convert these dynamics into durable advantage. For decision-makers seeking deeper segmentation data, regional cost modeling, and customized strategic recommendations, the full research report provides the detailed analysis needed to translate these market signals into actionable plans.
For detailed analysis of this topic, please visit the official page: Modified Starch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


