



Commercial Boilers Market: Why 4.2% CAGR and Condensing Tech Shift Strategy

The Commercial Boilers Market at an Inflection Point: Strategy for a High-Efficiency, Decarbonizing Future
The commercial boilers sector is navigating a structural transition. After reaching approximately 10,029.1 million USD in the base year, the market expands with a measured CAGR of 4.2 percent through the end of the forecast period, surpassing 13,000 million USD by the final projected year. The trajectory reflects steady demand for dependable heating infrastructure, but the composition of that demand is shifting. Efficiency mandates, fuel substitution, and digitalization are redefining what buyers expect from a core building systems component. For manufacturers, investors, and procurement leaders, the imperative is not simply to capture volume growth, but to align product roadmaps, capital allocation, and sourcing strategies with a market where performance, compliance, and operational flexibility increasingly determine competitive outcomes.
The Current Landscape and Core Challenges
The market size and growth rate signal a mature but evolving category. Historical expansion through the late 2020s and into the early 2030s demonstrates consistent investment in commercial heating capacity. Yet the headline numbers mask three pressure points that shape today’s decision-making environment.
PW Consulting
First, efficiency expectations have moved from desirable to mandatory. Condensing technology now accounts for a substantial share of the technology split and continues to gain ground as operators seek lower fuel consumption and tighter emissions compliance. This shift compresses margins for legacy non-condensing designs and raises the bar for manufacturers that must fund combustion optimization, heat recovery engineering, and validation testing while competing on a narrower performance delta.
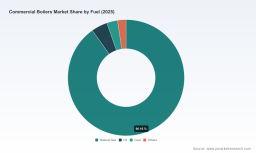
Second, fuel transition is uneven but undeniable. Natural gas continues to dominate the fuel mix and anchors the revenue base, yet rising scrutiny on carbon footprint, local air quality rules, and long-run fuel price volatility is accelerating experimentation with biomass, hybrid configurations, and electrified alternatives in niche applications. The practical challenge for commercial operators is that switching fuels often requires capital changes beyond the boiler itself—venting, storage, control systems, and utility coordination—which slows adoption and introduces project risk.
Third, operating economics and labor dynamics are reshaping total cost of ownership. Inspection fees, compliance verification, and service labor are becoming more visible line items in fleet management decisions. Recent regulatory updates in certain U.S. jurisdictions have adjusted inspection and pressure vessel fees, while energy programs increasingly require post-installation performance verification and combustion efficiency checks. Combined with skilled technician shortages, these factors push commercial buyers toward equipment that is easier to commission, simpler to maintain, and better integrated with remote monitoring.
Key Drivers Reshaping the Market
The commercial boilers market is being steered by four reinforcing forces. Understanding how they interact clarifies where value will be created over the next several years.
Technology Innovation and Breakthroughs. Efficiency gains are increasingly delivered through integrated systems rather than isolated hardware. Condensing boilers and high-efficiency water heating solutions continue to set the benchmark for fuel utilization in commercial applications. At the same time, modular and low-emission designs are expanding into process-intensive settings where steam and hot water demand must be met with fast response and minimal standby losses. The Danish dairy sector illustrates this convergence in practice. A whey processing facility introduced a 16 MW electric boiler to replace gas-fired units, enabling 72-hour unsupervised operation and demonstrating that electrified thermal assets can be integrated into continuous industrial processes when paired with robust controls. Alongside such electrification pilots, biomass projects are proving economically attractive in regions with favorable feedstock economics and support structures; a Danish dairy installation secured a subsidy and achieved rapid payback by displacing natural gas with a 2 MW biomass boiler. These examples underscore that technology leadership now spans combustion efficiency, emissions control, modularity, and the ability to partner with operators on hybrid or alternative-fuel architectures.
Policy and Regulatory Environment. Regulation is no longer a compliance checkbox; it is a design constraint and a demand catalyst. Emissions limits, inspection regimes, and incentive programs influence both equipment selection and the pace of replacement cycles. In the United States, updates to boiler and pressure vessel inspection rules have shifted cost assumptions for owners and service providers. Elsewhere, efficiency programs and utility-sponsored initiatives are embedding performance checks into installed bases—requiring combustion efficiency verification and post-tune-up reviews for certain greenhouse and commercial installations. For manufacturers and specifiers, this environment rewards designs that simplify compliance, document performance, and reduce the risk of failed inspections. For end users, it makes future-proofing a procurement criterion, especially in jurisdictions where rules are tightening on cadence.
Steam Boiler System Market
Demand-Side Behavior. Commercial operators are increasingly making heating decisions through a total cost lens that combines energy cost, maintenance burden, uptime requirements, and sustainability targets. Hospitals, offices, educational institutions, lodging, and food processing facilities each have distinct load profiles and reliability needs, but a common thread is the desire for systems that reduce unplanned downtime and simplify oversight. Dairy and other processing environments, for example, require commercial-grade hot water capacity with predictable operating costs; energy program technical manuals now reflect incremental cost assumptions that guide retrofit decisions. As building owners and facility managers weigh modernization against deferred maintenance, the value proposition shifts toward solutions that deliver measurable efficiency gains, faster commissioning, and clearer service interfaces.
Worldwide Water Tube Industrial Boilers Market
Supply Chain and Cost Structure. The commercial boilers market operates within broader input cost and logistics dynamics that affect lead times, pricing, and the economics of service networks. Raw material movements, component availability, and freight costs influence manufacturer margins and the timing of delivery commitments. On the demand side, the cost of inspections, compliance documentation, and skilled labor adds to the operating burden, making low-maintenance designs and remote diagnostics increasingly attractive. Companies that can stabilize cost structures, localize service capacity, and reduce the friction of installation and verification are better positioned to protect margins while competing on reliability and performance.
Competitive Landscape and Winning Strategies
The competitive field features a mix of established manufacturers with broad commercial portfolios and specialists oriented toward specific heat transfer or emission-control niches. Market concentration is moderate, and the structure creates room for differentiation through application expertise, integrated offering, and service depth rather than price alone.
Cleaver-Brooks positions around complete boiler room solutions, including firetube boilers and integrated systems tailored for commercial and industrial applications such as food processing and dairy. The strategic advantage here is system-level thinking: by spanning equipment, controls, and installation support, the company reduces integration risk for operators running continuous processes. Fulton Companies competes with high-efficiency steam and hydronic boilers, thermal fluid heaters, and custom heat transfer systems, leaning into application-specific engineering for commercial users that require precise temperature and pressure control. Hurst Boiler and Welding Co. broadens the fuel conversation with gas, oil, biomass, and hybrid steam and hot water boilers, an offering that aligns with operators exploring fuel flexibility or biomass substitution in regions with supportive economics.
On the efficiency and comfort side, Lochinvar and AERCO, a Watts brand, emphasize high-efficiency condensing boilers and water heating solutions for commercial settings. Their positioning reflects the broader market tilt toward condensing technology and the demand for water heating systems that perform reliably in continuous-use environments. Miura Boiler adds a distinct angle with modular low NOx steam boilers suited to commercial food processing and industrial uses, targeting sites where emissions limits and space constraints favor compact, quick-response units. Burnham Commercial Boilers and Laars Heating Systems round out the landscape with commercial-grade boilers and water heaters designed for HVAC and process heating applications, reinforcing the breadth of options available to specifiers across building types and load ranges.
The strategic patterns among leading players are converging on three themes. First, differentiation is shifting from unit efficiency alone to integrated value, including controls, commissioning support, and serviceability. Second, application specialization is becoming a moat; companies that understand the operating rhythms of food processing, healthcare, education, lodging, and office environments can tailor solutions that reduce downtime and simplify compliance. Third, flexibility in fuel and form factor is increasingly important as operators hedge against fuel price risk and regulatory change. The market is not consolidating rapidly enough to eliminate fragmentation, but it is rewarding companies that can bridge product capability with deployment and service realities. New entrants and niche specialists continue to find openings in modular, low-emission, and electrified thermal niches, while incumbents extend their advantage through installed base relationships and service networks.
Forward-Looking Trends for the Next 3–5 Years
The next several years will be defined by how quickly the market converts efficiency potential into deployed reality. Three trends stand out.
Efficiency as a baseline, integration as the differentiator. Condensing and high-efficiency designs will continue to expand their share, but the commercial opportunity will increasingly favor manufacturers that embed controls, diagnostics, and service-ready architecture into the product. Remote monitoring, predictive maintenance cues, and simplified verification of combustion performance will become selling points because they address labor constraints and compliance overhead simultaneously. Companies that make it easier to prove and sustain efficiency after installation will capture a disproportionate share of replacement and retrofit demand.
Fuel and thermal flexibility as risk management. While natural gas remains the dominant fuel, commercial operators will pursue options that reduce exposure to price volatility and evolving emissions expectations. Biomass, hybrid systems, and targeted electrification will grow where local conditions—feedstock cost, utility rates, incentives, and facility constraints—make the economics work. The strategic implication is that boiler offerings will need to support fuel transition pathways rather than single-fuel assumptions, and manufacturers will benefit from partnerships that extend to controls, venting, and commissioning for alternative configurations.
Serviceable, verified performance becoming part of the product promise. Inspection fee adjustments, program-driven performance checks, and the cost of skilled labor are elevating the importance of designs that are straightforward to inspect, tune, and sustain. Buyers will increasingly prioritize equipment that reduces ambiguity in compliance and minimizes the need for specialized intervention. This creates an opportunity for manufacturers and service providers to package equipment with clear documentation, verifiable efficiency targets, and support models that reduce lifecycle friction. The associated risk is that regulatory pace and program design vary by region, which can accelerate demand in some markets while slowing it in others, creating uneven near-term growth even as the long-term direction remains clear.
Strategic Moves for Decision-Makers
For manufacturers, the priority is to align product development with lifecycle value rather than initial specification. Invest in combustion and heat recovery refinements that hold efficiency in real-world operation, not just rated conditions. Build modularity and service access into designs, and equip sales and engineering teams to address fuel-flexible and hybrid scenarios where local economics justify them. Strengthen the link between equipment, controls, and documentation so that compliance verification and post-installation checks become easier for customers to manage. Where possible, pair hardware with service models that reduce the burden of inspection, tuning, and remote oversight, turning operational reliability into a competitive moat.
For investors, the signal is to look beyond top-line growth and assess which capabilities will command premium positioning as efficiency and compliance become default expectations. Evaluate exposure to condensing and high-efficiency segments, application specialization in process-intensive verticals, and the strength of installed-base service relationships. Consider the defensibility of manufacturers that can navigate fuel transition without fragmenting their portfolio, and favor players that translate regulatory and labor headwinds into product and service advantages. Watch regional variation closely: incentive structures, inspection regimes, and utility programs will create pockets of accelerated demand, and portfolio concentration in those pockets can materially affect growth trajectories.
For procurement and facility leaders, the practical move is to evaluate heating investments against a broader set of outcomes: efficiency sustainability over time, emissions compliance risk, service complexity, and integration with existing controls. Favor solutions that simplify verification and reduce dependence on scarce specialized labor, and model fuel transition scenarios where local incentives, feedstock, or utility economics make alternatives viable. Include inspection and compliance cost trends in total cost analysis, and treat documentation, commissioning support, and remote diagnostics as purchase criteria rather than optional extras.
The commercial boilers market is large enough to reward scale, but its future belongs to those who anticipate how efficiency, regulation, and operating economics will reshape purchasing criteria. Detailed segmentation data, regional dynamics, and company-level benchmarks are essential to translating these directional insights into actionable plans. For decision-makers seeking precise sizing across segments, competitive positioning detail, and tailored recommendations aligned to specific applications and geographies, the full research report provides the depth required to convert strategic direction into execution.
For detailed analysis of this topic, please visit the official page: Commercial Boilers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


