



Laminator Market 2026: Why 7.25% CAGR Forecasts a New Growth Trajectory

Strategic Trends and Commercial Opportunities in the Laminator Market
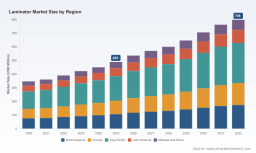
The laminator market has evolved from a niche machinery segment into a critical enabler of packaging integrity, print durability, and industrial surface protection. With the market valued at 347.0 million USD in 2020 and reaching 489.0 million USD in 2025, the sector demonstrates steady expansion driven by structural demand across packaging, printing, and commercial environments. The projected trajectory from 2026 through 2032 points toward sustained growth, with revenues scaling toward approximately 800 million USD by the end of the forecast period. A compound annual growth rate near 7.25 percent reflects a mature but still expanding equipment ecosystem, where incremental efficiency gains, format flexibility, and compliance requirements reshape procurement priorities. Understanding how this landscape is shifting matters for equipment manufacturers, converters, investors, and procurement leaders who must align capacity planning with demand signals rather than historical inertia.
Market Snapshot and Core Challenges
The laminator market spans a diverse range of machine architectures, from office-grade thermal pouch systems to high-throughput industrial and roll-to-roll units used in flexible packaging and graphic arts. Growth has been supported by the ongoing need for durable surface finishes, moisture resistance, and brand protection across consumer goods, medical packaging, and point-of-sale materials. At the same time, the market faces structural friction points that determine which operators will capture margin expansion and which will face margin compression.
One of the most consequential challenges is raw material volatility. Laminating films based on polypropylene and polyester, along with adhesive formulations tied to oil-derived inputs, create pricing uncertainty that directly influences machine utilization, conversion costs, and product positioning. When input costs swing sharply, manufacturers and converters must decide whether to absorb costs, pass them through, or redesign processes to reduce consumption. This dynamic pressures both equipment suppliers and end users, especially in packaging applications where thin-film optimization and material efficiency are becoming strategic levers.
A second challenge centers on safety and compliance scrutiny. Recent regulatory attention on thermal laminators highlights how product safety incidents can reshape procurement standards, especially in education, office, and small commercial environments. Recalls and hazard assessments trigger compliance reviews that affect purchasing cycles, after-sales expectations, and supplier qualification processes. For machine builders, the implication is clear: reliability, thermal management, and transparent safety documentation are no longer optional features but market-entry prerequisites.
A third challenge is the uneven cost environment for advanced lamination technologies. High manufacturing costs, combined with fluctuating film and adhesive pricing, can slow adoption of thermal lamination films in certain applications and constrain expansion where converters are already operating on narrow margins. This creates a divide between operators who can justify investment in automation and multi-function platforms, and those that remain tied to labor-intensive or fragmented workflows.
Core Demand Drivers Shaping the Market
The market’s direction is being shaped by several interconnected drivers, each pulling equipment requirements in different directions and rewarding manufacturers that can balance throughput, flexibility, and compliance.
Technological Innovation and Process Flexibility
A defining trend is the push toward machines that can handle multiple formats, curing methods, and finishing options within a single platform. The industry is seeing growing interest in systems that combine lamination with digital foil, UV and UV LED curing, embossing, and integrated slitting. This convergence reduces changeover time and broadens the value proposition for printing and packaging service providers who need to run shorter runs without sacrificing finish quality. Recent product unveilings at trade shows demonstrate that manufacturers are actively positioning versatility as a competitive differentiator, especially for converters seeking to serve both conventional and digitally enabled workflows.
Innovation is also visible in automation and process control. Automatic thermal film and roll-to-roll laminating systems with multi-function capabilities are increasingly associated with certifications and standardization that support international deployment. In a market where buyers compare total cost of ownership rather than initial price alone, equipment that improves repeatability, reduces waste, and simplifies operator training gains traction faster than machines that solve only one process step.
Policy, Safety, and Compliance Expectations
Regulatory and safety dynamics are becoming more influential in purchasing decisions, particularly where equipment affects end-user safety and brand risk. The recall of a widely recognized thermal laminator model due to overheating hazards illustrates how quickly compliance concerns can alter the commercial environment. Even when incidents are limited in scope, they prompt broader reviews of thermal management, electrical safety, and product documentation across categories.
BT Laminate Market
For industry participants, this environment rewards transparency and consistency. Companies that maintain recognizable safety certifications, clear usage guidelines, and traceable quality processes are better positioned to navigate procurement audits and institutional purchasing requirements. In commercial and office segments, compliance has become part of the value proposition, not just a legal checkbox.
Demand-Side Shifts in Packaging and Print
Demand behavior is shifting as brands and converters prioritize durable packaging, surface protection, and enhanced print presentation. Packaging continues to represent a substantial application base for lamination equipment, where lamination contributes to barrier performance, handling durability, and aesthetic finish. At the same time, printing and graphic arts applications rely on lamination for color enhancement, abrasion resistance, and shelf appeal.
A notable demand-side change is the increasing expectation for shorter runs, faster turnaround, and broader finish variation. This favors equipment that can move between tasks with minimal reconfiguration and supports hybrid production models where digital and conventional processes coexist. For converters, the commercial opportunity lies in expanding service offerings without proportionally expanding floor space or labor, which makes flexible laminator platforms strategically attractive.
Supply Chain and Cost Structure Pressures
Cost structure remains a pivotal force in market behavior. Volatile raw material costs for laminating films and adhesives create uncertainty in budgeting and can slow adoption where conversion margins are tight. These pressures do not simply affect consumables; they influence machine design priorities, since more efficient film handling, reduced waste, and better tension control can materially change operating economics.
At the same time, the supply chain environment is encouraging regional and application-specific specialization. Equipment providers that can deliver machines aligned with local production needs, certification requirements, and consumable availability often gain an advantage in markets where lead times, service access, and parts availability matter as much as equipment performance. This has contributed to a landscape where some players compete on global reach while others compete on localized process fit.
Competitive Landscape and Leading Strategies
The laminator market is characterized by a broad supplier base spanning office and print-shop equipment, commercial printing systems, and industrial packaging lines. Market concentration remains moderate, with the top three players holding roughly 26.5 percent and the top five near 30.1 percent, indicating room for differentiated positioning rather than domination by a small group of universal incumbents. This fragmentation creates both competition and opportunity, especially for companies that can claim distinct application strengths or technology leadership.
Laminating Machine Market
Strategic Positioning Across Market Segments
Several patterns emerge when comparing leading companies. In office and small commercial production, established players maintain strong recognition through thermal pouch and roll laminators designed for schools, offices, and light commercial use. Their advantage often rests on brand familiarity, distribution reach, and product ranges that address straightforward laminating needs with predictable operation. In this segment, sustained relevance depends on balancing ease of use, reliability, and service support.
In commercial printing and graphics protection, suppliers tend to emphasize print enhancement, film encapsulation, and reel-to-reel or reel-to-sheet systems. These companies compete on finish quality, format handling, and the ability to protect or elevate printed materials for demanding applications. Their differentiation typically comes from machine versatility, film compatibility, and the precision required for consistent high-end output.
In packaging and industrial applications, the competitive emphasis shifts toward roll-to-roll and solventless lamination, multi-technology coating and laminating, and integrated line solutions. Leading equipment suppliers in this space focus on flexible packaging, food and pharma-relevant processing, and high-throughput configurations that can be incorporated into broader converting lines. Their strategic edge often lies in combining lamination with slitting, gravure integration, or solventless adhesive compatibility, allowing operators to streamline production and reduce process complexity.
A parallel dynamic is emerging among machinery manufacturers that pursue international deployment through standardized certifications and patented automation features. Companies with explicit ISO and CE alignment, along with multi-function automatic thermal lamination designs, are positioned to serve buyers who require documented compliance and repeatable performance across multiple installations. This is particularly relevant for exporters and converters scaling operations across regions where qualification standards differ.
Market Evolution: Integration, Differentiation, and New Entry
The competitive landscape is evolving along several paths. One is consolidation through capability expansion, where existing players add curing, foil, embossing, or line-integration features to deepen their relevance in targeted verticals. Another is differentiation by format and application, with some manufacturers concentrating on packaging, others on commercial printing, and others on office and light commercial use. This specialization allows companies to build recognised expertise but also raises the risk of overlap when customer requirements cross traditional segment boundaries.
PW Consulting
New entrants and regional manufacturers continue to play an important role, especially where cost efficiency, rapid model updates, and application-tailored configurations are valued. Trade show activity suggests that live demonstrations and hands-on machine comparisons are increasingly central to procurement decisions, giving newer players a channel to establish credibility through visibility and performance proof. As a result, the market is not simply becoming more concentrated; it is becoming more competitive on the basis of demonstrated capability, compliance readiness, and production flexibility.
Future Trends and Commercial Implications
Looking ahead, several trends are likely to define the market’s next phase and shape where commercial value is created.
First, multi-function and hybrid laminator platforms will become more important as converters seek to manage shorter runs, varied finishes, and faster changeovers. Machines that can combine lamination with curing, foil application, or integrated slitting will appeal to operators trying to consolidate steps and reduce downtime. The commercial opportunity here is not only in selling equipment, but in enabling higher mix production with lower operational friction.
Second, safety, compliance, and documentation will increasingly influence procurement. Product incidents and regulatory scrutiny will continue to encourage buyers to evaluate thermal management, electrical safety, and quality assurance more carefully. Suppliers that can provide clear certification alignment and consistent product reliability will gain trust in segments where institutional purchasing and risk management are prominent.
Third, material and adhesive cost volatility will keep efficiency and waste reduction at the center of buying decisions. Equipment that optimizes film usage, improves tension control, or supports thinner or more cost-effective material setups will be especially valuable in packaging and flexible converting environments. In practice, this means machine choice will be judged not only by speed or throughput, but by how effectively it helps stabilize operating costs under variable input pricing.
These trends carry risk as well. Adoption of advanced platforms may slow if buyers face capex constraints or if raw material instability disrupts project economics. Regulatory attention may also raise compliance burdens that affect time-to-market for new equipment variants. In addition, regional differences in certification expectations and service infrastructure can limit how quickly a successful product in one market translates into another. Operators and investors should therefore treat flexibility and compliance readiness as core risk mitigants, not optional enhancements.
Actionable Guidance for Decision-Makers
For equipment manufacturers and converters, the priority is to align product and process strategy with where demand is becoming more complex. This means investing in platforms that reduce changeover time, support multiple curing or finishing options where relevant, and provide documented safety and quality credentials that simplify buyer qualification. Companies should also evaluate how machine design affects consumable efficiency, since film and adhesive cost volatility will continue to shape total operating economics. In markets where integrated packaging lines are gaining interest, positioning lamination as part of a broader process solution can strengthen commercial relevance.
For investors and strategic planners, the market’s moderate concentration and diverse application base suggest that value will be created through differentiated capability rather than uniform scale. Segments tied to packaging, commercial printing, and compliance-sensitive office use each present distinct growth logic, but they also require different product, service, and distribution approaches. Tracking trade show launches, product certifications, and application-focused positioning can provide early signals about where competitive advantage is forming. Given the pace of change in hybrid machine features and compliance expectations, detailed segmentation data becomes valuable when it is tied to real procurement drivers rather than broad category averages.
For procurement and operations leaders, purchasing decisions should weigh more than throughput or list price. Total cost of ownership considerations should include film and adhesive efficiency, service access, spare parts availability, safety documentation, and the machine’s ability to handle anticipated format variation. Where production environments require frequent changeovers or mixed finishing options, versatility and process stability may deliver more commercial value than raw speed alone. Evaluating suppliers against compliance readiness and operational support can reduce downstream risk, especially when safety or quality scrutiny is elevated.
The laminator market is entering a phase where growth is less about uniform expansion and more about matching equipment capability to shifting production realities. Machines that combine flexibility, efficiency, and compliance credibility will be better positioned to capture demand across packaging, printing, and commercial environments. For readers seeking deeper segmentation detail, regional application dynamics, and tailored strategic scenarios, the full PW Consulting Laminator Market report provides a more granular view of the opportunities and tradeoffs shaping this landscape.
For detailed analysis of this topic, please visit the official page: Laminator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


