



IP Cameras Market 2032: Why 13% CAGR and $32B Value Are Only Half the Story

The IP Cameras Market: Strategic Trends and Commercial Opportunities Through 2032
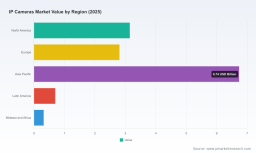
The IP cameras market is entering a phase of accelerated expansion, driven by a convergence of technological maturation, regulatory shifts, and evolving end-user expectations. By 2025, the global market has reached a valuation of approximately $13.72 billion, reflecting sustained momentum from the $8.15 billion recorded in 2020. The trajectory points toward a robust compound annual growth rate of 13.0 percent through the 2026–2032 forecast period, with projected revenues climbing to $32.22 billion by 2032. This growth roadmap signals more than incremental hardware sales; it underscores a structural transformation in how surveillance, safety, and operational intelligence are deployed across commercial, residential, and public infrastructure environments. For executives and investors, the market offers meaningful expansion potential, but success will hinge on navigating fragmentation, compliance mandates, and the rapid integration of intelligence into imaging hardware.
PTZ Camera Market
Market Landscape and Core Challenges
The IP cameras ecosystem has matured beyond simple video capture. Modern deployments function as distributed sensing nodes that feed into broader security, analytics, and facility management architectures. The market’s expansion reflects widespread adoption across multiple verticals, with commercial facilities, residential estates, and government or public safety installations each contributing substantial revenue streams. Fixed cameras continue to hold significant share, reflecting their cost-effectiveness and reliability in standardized monitoring scenarios. Pan-tilt-zoom units address the need for flexible, remotely directed surveillance, while infrared-capable devices cater to low-light and perimeter applications. This diversified product mix allows end users to piece together solutions that balance coverage, resolution, and budget constraints.
Behind the positive growth signals, several structural challenges are reshaping how companies compete and how buyers evaluate procurement decisions. One of the most pressing issues is regulatory compliance, which increasingly functions as both a market gatekeeper and a competitive differentiator. Procurement rules now restrict the use of certain non-compliant devices in sensitive deployments, creating clear boundaries around eligible suppliers. At the same time, data privacy expectations are becoming more stringent across healthcare, commercial, and public-sector environments, forcing manufacturers and integrators to embed privacy-preserving features directly into platforms rather than treating them as afterthoughts.
A second challenge lies in budget dynamics and capital allocation. While the demand for AI-enabled analytics and advanced imaging capabilities continues to rise, many organizations face constraints in funding large-scale upgrades. Hospitals, municipal authorities, and commercial operators frequently weigh the upfront investment in intelligent camera systems against operational budgets that must also cover staffing, maintenance, and core infrastructure. This tension creates an environment where value is measured not only by image quality or feature lists, but by measurable improvements in safety, workflow efficiency, and risk reduction.
A third challenge is the evolving infrastructure of deployment itself. Fixed dome configurations have become particularly prominent in sensitive indoor environments due to their discreet appearance, resistance to vandalism, and consistent coverage in corridors and waiting areas. This preference shapes product design priorities and installation practices, pushing manufacturers to refine form factors, mounting flexibility, and environmental durability. Meanwhile, enterprises are increasingly expecting seamless integration with existing facility systems, access control, and centralized management platforms, which raises the bar for interoperability and long-term support.
PW Consulting
Core Drivers of Market Change
Technological Innovation and Intelligence Integration
Progress in imaging sensors, edge computing, and on-device analytics is redefining what IP cameras can deliver. Modern devices are no longer passive recording endpoints; they increasingly support real-time detection, behavioral alerting, and metadata generation that feeds downstream systems. This shift is especially apparent in healthcare-adjacent deployments, where camera platforms are being positioned to support patient safety monitoring, fall detection, and privacy-compliant installations. Suppliers that can pair high-quality imaging with integrated analytics, secure access controls, and privacy mechanisms such as face blurring are gaining traction among organizations that need both protection and compliance.
The technology trajectory also favors platforms that reduce dependency on heavy backend processing. By moving more intelligence to the edge, deployments can lower bandwidth demands, improve responsiveness, and enhance resilience in environments where connectivity may be intermittent. For commercial operators and public safety agencies, this translates into more reliable monitoring and quicker decision-making without requiring massive centralized infrastructure upgrades.
Regulatory and Compliance Environments
Compliance has moved from a procurement footnote to a strategic constraint. In the United States, federal buyers are increasingly required to select NDAA-compliant cameras from approved suppliers, a development that directly shapes the competitive field in government and public safety applications. In parallel, privacy-related obligations continue to influence product design and deployment models, particularly where cameras may capture patient-related or personally identifiable information. Enterprise-grade platforms are increasingly expected to provide configurable privacy features, secure authentication, and auditable access management as standard capabilities.
Regulatory momentum is also expanding geographically. For example, standards requiring essential compliance for CCTV and IP cameras have become mandatory in certain markets for healthcare facility deployments, with enforcement timelines that compel early preparation. Organizations evaluating multi-country rollouts must now account for divergent certification requirements, local testing frameworks, and region-specific procurement rules. This compliance layer is becoming a major factor in vendor selection, implementation timelines, and total cost of ownership.
Demand-Side Shifts in End-User Behavior
End-user expectations are shifting from surveillance as a reactive measure to monitoring as part of a broader operational and safety strategy. In healthcare settings, the emphasis is increasingly on patient safety, facility flow, and clinical workflow support rather than purely on external perimeter defense. In commercial environments, organizations are seeking systems that can support occupancy insights, access coordination, and incident response without fragmenting their technology stack. Residential users, meanwhile, are responding to greater availability of connected, cloud-managed options that emphasize ease of use and remote access.
This demand evolution is also changing the buying conversation. Decision-makers increasingly compare solutions based on integration readiness, lifecycle support, and the ability to adapt to future analytics needs. The most compelling propositions combine reliable core imaging with extensible software capabilities, ensuring that a deployment can evolve without requiring full hardware replacement. Consequently, vendors that can articulate clear operating value, not just technical specifications, are gaining advantage in competitive evaluations.
Supply Chain and Cost Structure Dynamics
Cost structures across the IP cameras market are being shaped by both material innovation and product lifecycle strategy. Manufacturers are exploring environmentally sustainable design choices, including the use of recycled materials in new product lines, which signals a broader shift toward responsible sourcing and corporate accountability. While sustainability does not automatically reduce unit costs, it can influence purchasing decisions in organizations with formalized ESG targets and procurement policies.
At the same time, competitive pressure continues to push the market toward greater efficiency in manufacturing, logistics, and support. The balance between premium feature sets and affordability remains delicate, especially where budgets are constrained and buyers must justify capital expenditure. Companies that can manage cost while maintaining compliance readiness, durability, and platform extensibility are better positioned to defend margins and scale across multiple end markets.
Competitive Landscape and Leading Strategies
The market is marked by meaningful concentration at the top, with a small group of established players accounting for a substantial share of revenue. This concentration reflects the importance of brand trust, long-term deployment support, compliance readiness, and the ability to serve regulated verticals with specialized configurations. Yet the landscape is not static. Different leaders are pursuing distinct strategic positions, and the gap between hardware-centric suppliers and platform-oriented entrants is widening in terms of customer expectations.
Axis Communications has maintained a strong identity around purpose-built network IP cameras, with particular emphasis on healthcare surveillance, patient monitoring, and privacy-compliant installations. Its approach highlights the value of specialized use-case positioning, where product architecture is aligned with the operational and regulatory needs of sensitive environments. Hanwha Vision has pursued a similar vertical focus by supporting AI-enabled IP cameras and modular systems integrated into clinical environments, targeting hospital safety, fall detection, and workflow enhancement. This combination of imaging and application-level integration illustrates a broader trend: winning in regulated settings increasingly depends on demonstrating how a camera system fits into daily operations rather than simply offering higher resolution.
Dahua Technology and Hikvision continue to play significant roles in the broader ecosystem, offering video-centric AIoT IP cameras and network IP camera solutions aimed at facility operations and security. Their scale and breadth of product portfolios give them reach across multiple deployment contexts. Bosch Security Systems contributes a strong engineering reputation with IP camera systems designed for healthcare security monitoring and integration with hospital infrastructure, reinforcing the importance of infrastructure compatibility. Pelco has carved out a recognizable niche with IP camera series engineered for hospital patient safety monitoring and regulatory-compliant applications, while Honeywell International Inc. serves secure healthcare environments and facility upgrades with performance-oriented and explosion-proof options. Arecont Vision remains relevant for high-quality megapixel coverage in hospital video surveillance upgrades, where image fidelity is a primary requirement.
One of the more notable competitive shifts is the rise of cloud-managed platforms that bundle compliance and privacy features into the operating model. Verkada, for example, has positioned a cloud-managed IP camera platform with built-in HIPAA-relevant compliance and privacy features for hospital and healthcare facility security. This model appeals to organizations seeking simplified management, centralized visibility, and reduced reliance on fragmented on-premises administration. It also reflects a broader market movement toward subscription-friendly, software-forward service models that can lower operational friction for end users.
Recent product developments illustrate how competitive positioning is evolving in practice. In September 2025, Axis launched a new line of environmentally sustainable IP cameras utilizing recycled materials. This move signals that differentiation is expanding beyond imaging and analytics into materials, lifecycle impact, and procurement alignment with organizational sustainability commitments. In a market where multiple vendors can offer strong technical performance, such initiatives can influence buying decisions among customers with explicit environmental or procurement goals.
The competitive trajectory points toward both consolidation and differentiation. Larger players with strong compliance credentials, vertical expertise, and platform breadth are well placed to capture regulated and enterprise demand. At the same time, new entrants and regional specialists can still compete by targeting specific installation types, offering favorable integration economics, or delivering cloud-managed experiences that reduce deployment complexity. The most likely evolution is a market in which broad-scale vendors coexist with focused specialists, each winning on different combinations of compliance, integration, service model, and total cost of ownership.
Future Trends and Commercial Opportunities
Intelligence Becoming Standard Rather Than Optional
Over the next three to five years, AI-enabled capabilities are expected to move from premium add-ons to baseline expectations in many deployment categories. As edge processing becomes more efficient and analytics become easier to configure, organizations will increasingly expect cameras to contribute to detection, alerting, and workflow support without demanding heavy external infrastructure. The commercial opportunity lies in solutions that make these capabilities usable, not merely available. Suppliers that simplify configuration, improve false-positive management, and connect camera-generated insights to practical operational actions will have stronger competitive positioning. The risk is that feature competition alone will erode margins unless vendors can demonstrate tangible value in safety, efficiency, or compliance outcomes.
Compliance as a Market Filter and Growth Enabler
Regulatory requirements are likely to continue tightening the boundaries of eligible suppliers and deployment models. Rather than simply limiting competition, this trend can create growth opportunities for vendors that proactively align with compliance frameworks and communicate that alignment clearly. In healthcare and public-sector contexts, the ability to provide privacy controls, secure access management, and recognized certification readiness may become as important as image quality. Organizations that invest early in compliant architectures and integrate them into broader facility operations may benefit from faster procurement cycles and reduced redesign risk. The uncertainty lies in the pace and fragmentation of regulatory change across regions, which can complicate planning for multinational or multi-site rollouts.
Platform Models and Managed Services Reshaping Ownership
The market is gradually shifting toward models in which the camera is part of a managed platform rather than a standalone purchase. Cloud-managed visibility, centralized administration, and subscription-oriented service options can reduce operational burden for end users while creating recurring value streams for suppliers and integrators. This shift opens opportunities for companies that can combine reliable hardware with strong software experience, data security, and scalable support. At the same time, it raises expectations for long-term reliability, cybersecurity posture, and vendor continuity. Buyers will increasingly weigh how easily a system can be maintained, updated, and integrated over time, not just how it performs on day one.
Strategic Guidance for Decision-Makers
For manufacturers and technology providers, the priority is to connect product capabilities to operational outcomes that regulated and budget-conscious buyers can justify. Differentiation will increasingly come from compliance readiness, privacy-aware design, integration with existing infrastructure, and platform extensibility. Companies should evaluate where they can lead in specialized verticals such as healthcare-adjacent safety and monitoring, while ensuring that sustainability and supply chain credibility support broader procurement appeal. In practical terms, this means articulating not only what a camera can capture, but how it helps an organization reduce risk, improve workflow, and meet compliance requirements without inflating total cost of ownership.
For investors, the market offers expansion potential, but the most durable opportunities will likely belong to players that combine scale with vertical relevance and platform-oriented business models. The key is to distinguish between short-term hardware demand and longer-term value creation through software, services, and compliance-aligned positioning. Investments that support integration ecosystems, secure cloud-managed experiences, and analytics that are demonstrably useful in operational settings may offer stronger resilience as the market matures. Attention should also be paid to regulatory evolution, since compliance shifts can rapidly change which suppliers and deployment models are viable in important end markets.
For procurement leaders and end-user organizations, the strategic task is to move beyond feature comparison and evaluate total deployment value. This includes assessing NDAA compliance or equivalent regulatory alignment where applicable, confirming privacy and data protection capabilities, and verifying that the selected platform can integrate with existing security, access, and facility systems. Organizations should also weigh the operational model they prefer, whether that is locally managed infrastructure, cloud-managed visibility, or a hybrid approach, and ensure that staffing, maintenance, and lifecycle support are factored into the decision. Early planning for certification requirements and compliance timelines can prevent costly redesigns and speed up deployment.
Given the speed of change across technology, regulation, and end-user expectations, detailed segmentation data, region-specific compliance maps, and vendor-level positioning analysis can make a meaningful difference in strategic planning. The broader market direction is clear, but the practical choices around product architecture, procurement eligibility, and commercial model depend on granular intelligence that reflects local requirements and vertical realities. For decision-makers seeking to act with confidence in this environment, deeper research can help translate the overall growth narrative into targeted entry points, risk mitigations, and execution priorities.
Industrial Cameras Market
For detailed analysis of this topic, please visit the official page: IP Cameras Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


