



Ultrafiltration Membrane Filtration Market: How 7.45% CAGR and Key Applications Redefine Growth

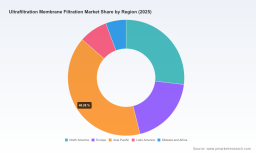
Navigating the Ultrafiltration Membrane Filtration Market: Strategic Trends and Commercial Opportunities Through 2032
The ultrafiltration membrane filtration market has entered a phase of steady, structurally supported expansion. Valued at approximately 195.4 million USD in 2025 and projected to reach 321.45 million USD by 2032, the sector is tracking a compound annual growth rate of 7.45 percent across the 2026–2032 horizon. This trajectory is underpinned by measurable historical momentum, with revenue climbing from 152.3 million USD in 2020 through successive annual increments to the current baseline. The market’s evolution reflects a convergence of tightening water quality standards, industrial process optimization demands, and technological maturation in membrane materials and module architectures. For executives and investors, the critical question is no longer whether the market will grow, but how growth will be distributed across regions, applications, and technology platforms, and where competitive positioning can be deliberately shaped rather than passively inherited.
Market Context and Core Challenges
The current market landscape is characterized by broad-based adoption across water and wastewater treatment, food and beverage processing, pharmaceutical and biotechnology operations, and chemical industry applications. Revenue concentration remains relatively fragmented, with the top three players accounting for roughly 18.75 percent of total market value and the top five reaching 25.6 percent. This dispersion signals a field where scale advantages exist but have not yet consolidated into dominant pricing power or exclusive technology gates. At the same time, the market is passing through a set of structural inflection points that will determine which participants capture disproportionate value over the next several years.
One of the most pressing challenges is the tension between performance durability and operational cost. Ultrafiltration systems are increasingly deployed in environments with high fouling potential, variable feed water quality, and stringent effluent requirements. Membrane biofouling, scaling, and mechanical degradation continue to drive energy consumption, chemical cleaning frequency, and replacement cycles. Participants that can demonstrably extend service life, reduce cleaning intensity, or lower footprint without compromising rejection rates are beginning to separate themselves from commoditized offerings. The challenge is not merely technical; it is commercial. Operators evaluate total cost of ownership over multi-year horizons, meaning that marginal improvements in flux stability or chemical resistance must translate into verifiable operational savings to justify premium positioning.
A second challenge lies in the uneven pace of regulatory and infrastructure modernization across geographies. In mature markets, existing water infrastructure is aging, and replacement cycles create steady demand for upgrade-grade filtration solutions. In emerging industrial corridors, rapid capacity expansion is colliding with tightening discharge norms and water reuse mandates. The result is a bifurcated demand environment: some segments move toward standardization and price sensitivity, while others prioritize reliability, compliance assurance, and integration with downstream processes. Suppliers that cannot adapt their commercial models, technical support, and application engineering to these differing buying contexts risk being trapped in low-margin volume competition.
A third challenge is the shifting economics of materials and manufacturing. Membrane fabrication depends on polymers, specialized coatings, and precision module assembly, all of which are sensitive to raw material volatility, energy costs, and supply chain continuity. At the same time, customers are increasingly scrutinizing lifecycle impacts, including chemical usage, water recovery rates, and end-of-life handling. Companies that rely on rigid product portfolios or single-source material dependencies face margin pressure and responsiveness gaps. The market is therefore rewarding participants that combine material science flexibility with scalable, regionally balanced production and service networks.
Key Drivers Shaping Market Direction
Technological Innovation and Module Architecture Evolution
Innovation in ultrafiltration is increasingly centered on module design, pore size control, and fouling mitigation rather than incremental polymer substitutions alone. Recent product movements illustrate a clear direction: integrated pre-filtration approaches that combine coarse screening with ultrafiltration in a single module are being positioned to reduce footprint and capital expenditure for drinking water and seawater applications. Alongside this, next-generation hollow-fiber modules with notably small nominal pore sizes are entering commercial rollout, targeting lower biofouling propensity and higher removal consistency. These developments matter because they shift the value proposition from standalone membrane performance to system-level efficiency. When pre-filtration and ultrafiltration are co-optimized, operators can reduce piping complexity, lower headloss, and simplify installation, which directly influences procurement decisions in space-constrained or cost-sensitive projects.
PW Consulting
Material differentiation remains important, particularly where chemical resistance, temperature tolerance, or위생 compatibility are decisive. Polysulfone, polyethersulfone, polyvinylidene fluoride, and ceramic-based platforms each occupy distinct niches defined by feed characteristics and operating conditions. The strategic signal is that no single material is universally dominant; rather, the opportunity lies in matching material architecture to application profiles while reducing the operational burden of cleaning and replacement. Companies that can offer configurable module formats, predictable performance envelopes, and documented longevity are better positioned to win in segments where downtime and compliance risk are unacceptable.
Membrane Filtration Market
Policy, Regulatory, and Standards Environment
Regulatory pressure continues to be a durable demand catalyst. Stricter limits on particulate matter, pathogen indicators, and industrial effluents are expanding the addressable base for ultrafiltration in both municipal and industrial settings. Equally important is the growing emphasis on water reuse and resilience, which pushes ultrafiltration into pretreatment and polishing roles that were historically handled by alternative technologies. In sectors such as semiconductor manufacturing and advanced industrial processing, water quality consistency is not merely an environmental concern but a process requirement, which elevates ultrafiltration from a cost center to a reliability enabler.
This regulatory and operational convergence is visible in recent contract and certification activity. High-value, long-duration operational contracts for complex water treatment facilities are being secured alongside public demonstrations of resilient wastewater treatment technologies at industry events. These moves indicate that leading participants are not only selling equipment but also embedding themselves into multi-year service and performance arrangements. For the market, this signals a shift toward outcome-based positioning, where technology selection is increasingly tied to guaranteed operational behavior, compliance documentation, and integration with broader treatment trains.
Ultrafiltration Membrane Market
Demand-Side Shifts in Industrial and Municipal Buying Behavior
Buyers are behaving differently than in prior cycles. In municipal and utility contexts, capital constraints and workforce limitations are favoring solutions that reduce installation complexity, simplify operation, and lower long-term maintenance burdens. In industrial settings, procurement is increasingly influenced by process continuity, footprint constraints, and the need to integrate filtration with downstream units such as reverse osmosis, membrane distillation, or specialty separation steps. The food and beverage sector adds another dimension: consistency, flavor preservation, and sanitary design can be as important as nominal filtration performance.
These demand-side shifts create a strategic implication: product specifications alone no longer win deals. Application engineering, pilot validation, and post-installation support have become decisive differentiators. Suppliers that can demonstrate how an ultrafiltration module behaves in a specific feed context, how it interacts with pretreatment chemistry, and how it affects total operating expense are gaining traction over suppliers that compete primarily on unit pricing. The market is therefore moving toward segment-specific value narratives rather than generic performance claims.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by material availability, manufacturing scalability, and the economics of service delivery. Companies with diversified material platforms and flexible module formats can better absorb input cost fluctuations and tailor supply to regional demand patterns. At the same time, logistics, installation support, and local technical service are becoming more influential in winning and retaining contracts, particularly where project timelines are tight or where operators lack specialized filtration expertise.
This environment favors participants that view the supply chain as a commercial asset rather than a back-office function. Regional production presence, application testing capabilities, and responsive spare-part networks can translate into shorter delivery cycles, lower risk for buyers, and stronger customer lock-in. Conversely, suppliers dependent on centralized production and limited service footprints may find themselves disadvantaged in markets where responsiveness and localization are increasingly weighted in procurement decisions.
Competitive Landscape and Strategic Positioning
The competitive field includes large diversified material and membrane manufacturers, water technology integrators, and specialized membrane producers with deep application focus. This mix creates a layered competitive dynamic. Larger players benefit from broad R&D resources, global distribution, and the ability to bundle membranes with systems, controls, and service. Smaller or regionally anchored specialists compete through material specificity, customization, and close engagement with niche applications such as high-throughput industrial processing, bioprocess filtration, or specialty food and beverage clarification.
Several strategic positions are evident. One is the module-integration advantage, where combined pre-filtration and ultrafiltration architectures are used to reduce footprint and capital cost while simplifying installation. A second is fouling-resistance and pore-size differentiation, where smaller nominal pore sizes and lower-biofouling designs are positioned for environments that demand higher removal consistency and reduced cleaning intensity. A third is application-centric specialization, where ceramic-based or custom flat-sheet and spiral-wound formats are tailored to demanding industrial feeds, sanitary processing, or laboratory and bioprocess requirements. A fourth is market-entry expansion through localized manufacturing and commercial presence, which enables faster response to regional demand and reduces reliance on distant supply chains.
The market is also showing signs of evolving through selective consolidation and targeted expansion rather than across-the-board merger activity. Large players are strengthening system-level offers and securing long-duration operational roles in complex facilities, while specialized manufacturers are widening their reach through trade presence, technical presentations, and application-specific demonstrations. New entrants and regional manufacturers are gaining ground where local cost structures, feed-specific expertise, or first-mover status in domestic production provide a foothold. The overall direction suggests that competitive advantage will increasingly depend on the ability to combine material and module innovation with regional responsiveness, application engineering, and service integration.
Forward Outlook: Three Trends to Watch Through 2032
The first trend is the continued shift toward integrated and footprint-optimized filtration solutions. As installation space, capital budgets, and operational simplicity become more prominent decision factors, modules and systems that reduce component count, lower piping complexity, and combine pre-filtration with ultrafiltration will see growing interest. Commercial opportunity lies in offering validated, application-ready configurations that shorten project cycles and reduce total installed cost, especially in municipal upgrades and space-constrained industrial facilities.
The second trend is the widening role of ultrafiltration as a resilience and reuse enabler. Water scarcity, discharge tightening, and process-water reliability requirements are pushing ultrafiltration into more pretreatment, polishing, and reuse positions across municipal, industrial, and specialized manufacturing contexts. The opportunity here is not simply volume growth but value-tier expansion: participants that can document recovery performance, chemical robustness, and integration compatibility with downstream processes are better positioned to capture higher-margin roles rather than competing solely as commodity membrane suppliers.
The third trend is the growing importance of lifecycle economics and service-embedded offerings. Buyers are increasingly weighing cleaning frequency, membrane lifespan, energy behavior, and support responsiveness alongside initial purchase price. This opens the door to performance-based service models, predictive maintenance support, and region-specific technical engagement. The risk is that companies with rigid product portfolios or weak local support may be squeezed as operators prioritize predictable operation over lowest upfront cost. Uncertainty remains in the pace of regulatory adoption, the volatility of material inputs, and the degree to which large-scale infrastructure programs translate into discrete filtration procurement opportunities. Participants should therefore treat macro growth as an enabling condition rather than a guarantee, and build flexibility into product, pricing, and service strategies.
Strategic Recommendations for Decision-Makers
For membrane and module manufacturers, the priority is to move beyond specification competition toward application-validated value propositions. This means investing in feed-specific performance data, configurable module formats, and demonstrable reductions in cleaning intensity or footprint. Manufacturers that align material choices with clear operating envelopes and back them with regional technical support will be better positioned to defend margins and win complex projects. It also means evaluating supply chain resilience as a strategic lever, including material diversification and localized production where demand growth and service expectations justify the investment.
For investors, the most relevant signal is that growth is real but uneven across segments and geographies. Capital allocation should favor participants with durable application ties, module or system integration capabilities, and credible service economics rather than those competing primarily on volume pricing. The market’s moderate concentration and ongoing product launches suggest continued room for differentiators, but also the risk of margin erosion where technology gaps narrow. Due diligence should therefore weigh total cost of ownership narratives, pipeline visibility in reuse and industrial treatment, and the ability to convert product launches into commercial traction across target regions.
For procurement leaders and operations executives, the practical imperative is to evaluate ultrafiltration choices within the full treatment context rather than as isolated components. Pilot validation, cleaning and replacement cost modeling, and integration compatibility with downstream processes should carry as much weight as nominal pore size or material label. Where projects are space- or capital-constrained, integrated module approaches and footprint-optimized designs merit close scrutiny. Where process reliability is paramount, documented fouling behavior and service responsiveness should be treated as primary selection criteria. Strategic sourcing decisions made with this broader lens are more likely to deliver durable operational savings and lower compliance risk.
The ultrafiltration membrane filtration market is moving from broad-based expansion toward more differentiated, application-led competition. The participants that will capture disproportionate value are those that can combine material and module innovation with system-level efficiency, regional responsiveness, and credible lifecycle economics. Understanding where these advantages are forming, and how procurement and investment decisions are shifting in response, is essential for shaping strategy through 2032. The broader market trajectory is clear; the real leverage lies in the details of segmentation, material and module positioning, regional demand patterns, and competitive move sequencing. For decision-makers seeking to translate these dynamics into concrete plans, a detailed examination of segmented market sizing, application-specific growth paths, regional nuances, and company-level strategic plays provides the necessary foundation for sharper capital allocation, product roadmap decisions, and procurement strategy.
For detailed analysis of this topic, please visit the official page: Ultrafiltration Membrane Filtration Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


