



Microbial Air Samplers Market Surpasses $158M: 5 Shifts Reshaping 2032 Growth

Strategic Trends and Commercial Opportunities in the Microbial Air Samplers Market
Market Overview: Navigating a Maturing Landscape
The global market for microbial air samplers has demonstrated steady, measured expansion over the past half-decade, evolving from a niche compliance tool into a core component of environmental quality management. Between 2020 and 2025, the sector moved from a base of approximately 127 million USD to nearly 159 million USD, reflecting annual revenue growth that has stabilized around a low-to-mid single-digit pace. Looking ahead through the early 2030s, the trajectory suggests a continuation of this measured expansion, with the market expected to approach the 220 million USD mark by 2032. This progression is not explosive, but it is structurally meaningful: it signals a transition from reactive, post-event sampling to systematic, real-time contamination control embedded within manufacturing and healthcare workflows.
PW Consulting
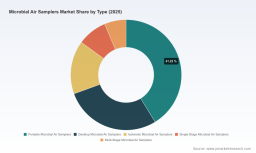
The revenue distribution across equipment categories further illustrates how the market has matured. Portable units command the largest share of the equipment mix, underscoring the enduring demand for flexibility, mobile verification, and rapid deployment across multi-line or multi-site facilities. Desktop and isokinetic configurations together represent a substantial secondary layer, catering to fixed monitoring stations and environments where airflow accuracy matters. Single-stage and multi-stage systems occupy a smaller but increasingly specialized niche, particularly where cascade impaction or size-fractionated sampling is required for detailed microbial characterization. The diversity of form factors is not a symptom of fragmentation; it reflects a market responding to heterogeneous operational requirements, from grade A aseptic suites to routine environmental verification across food processing or hospital spaces.
As the sector approaches its next growth phase, several structural realities define the commercial landscape. Demand is no longer driven solely by regulatory minimums; it is increasingly shaped by operational risk tolerance, productivity targets, and the economics of quality failures. At the same time, the supplier base remains modestly concentrated, leaving room for differentiation through engineering, service, and data integration rather than pure volume. For decision-makers, this creates a market where performance credibility, regulatory alignment, and total cost of ownership matter more than upfront sticker price alone.
Air Sampling Pumps Market
Core Challenges and Inflection Points
Regulatory Pluralism and the Cost of Compliance Misalignment
One of the most pressing operational challenges in this market is the absence of a single, globally uniform compliance framework. Cleanroom and critical-environment monitoring must align with overlapping expectations, including EU-GMP Annex 1, ISO 14698, EN 17141, FDA aseptic guidance, and USP standards. While this layered regulatory environment strengthens patient and product safety, it also introduces complexity for equipment selection, validation, and ongoing qualification. Manufacturers and end users alike must ensure that sampling heads, flow paths, and data outputs satisfy not just one standard but the entire stack of requirements relevant to their jurisdiction and production type. When a device is optimized for one framework but fails to accommodate another cleanly, the consequence is often rework, revalidation cycles, or delayed qualification, all of which erode the commercial value of otherwise capable instruments.
Sterilization, Contamination Control, and Lifecycle Management
A second challenge lies in the interplay between sampling performance and decontamination practicality. In high-risk environments, sampling heads and internal flow paths must be fully compatible with vaporized hydrogen peroxide and other decontamination methods, while surfaces must resist particulate retention and secondary contamination. Electropolished stainless steel and VHP-compatible materials have become essential rather than optional features in many Grade A and B settings. At the same time, consumable components such as membrane filters must balance retention efficiency, shelf stability, and sterility assurance. Filters with long shelf life and high spore retention can reduce waste and logistics complexity, but they also raise procurement costs and inventory management questions. The market is therefore shifting from a focus on sampling alone toward a broader consideration of the entire monitoring lifecycle, including preparation, execution, decontamination, documentation, and consumable management.
The Data Integrity Premium
A third inflection point is the growing emphasis on data integrity and electronic recordkeeping. Modern cleanroom operations increasingly require auditable, tamper-resistant data streams that satisfy requirements such as 21 CFR Part 11. This elevates the importance of remote and connected sampling solutions that can support continuous monitoring, time-stamped records, and robust user-access controls. The challenge for suppliers is not simply to add connectivity, but to design instruments where data generation, storage, and retrieval are integrated in a way that reduces manual handling and human error. For buyers, the lesson is that a sampler with strong physical performance can still fail commercially if its documentation and data architecture do not align with enterprise quality systems.
Key Drivers Shaping the Market
Technological Innovation: From Sampling Devices to Smart Monitoring Nodes
The most visible driver of change is the shift toward smart, integrated sampling systems. Recent product developments have highlighted a move beyond mechanical reliability alone toward instruments that combine process safety, minimal secondary contamination risk, and higher assurance of data integrity. In this context, features such as magnetic perforated lids, smart functional controls, and enhanced usability are not cosmetic; they are engineering responses to real operational pain points. By reducing handling variability and improving repeatability, these innovations help operators achieve more consistent environmental verification and lower the risk of false signals caused by sample contamination or user error.
At the same time, connected and remote sampling options are gaining traction because they address the need for continuous observation without constant manual intervention. In pharmaceutical and semiconductor cleanrooms, where interruptions can carry significant operational and compliance costs, remote samplers can support ongoing monitoring regimens while preserving documentation rigor. This trend is expanding the market’s value proposition: samplers are increasingly judged not only on capture efficiency but also on how seamlessly they fit into broader quality and digital ecosystems.
Regulatory and Standards Evolution as a Catalyst for Upgrade Cycles
Regulatory and guidance evolution continues to act as a structural catalyst for equipment refreshes. As expectations around Grade A and B environments tighten, and as standards for viable air monitoring become more explicit, facilities often re-evaluate legacy equipment against updated requirements. The result is a recurring upgrade cycle driven by compliance modernization, especially in sectors where environmental monitoring is integral to product release and audit readiness. Importantly, this dynamic does not depend on regulatory shocks; it is sustained by incremental clarification, harmonization efforts, and the broader industry drift toward proactive contamination control. Suppliers that can demonstrate clear alignment with current expectations and foreseeable updates are better positioned to participate in these refresh cycles.
Demand-Side Shifts: Risk Management Beyond Pharma
Demand is also broadening as organizations in adjacent sectors recognize the value of routine viable air monitoring. Pharmaceutical and biopharmaceutical production remains the dominant application context, but hospital and healthcare environments are increasingly integrating air monitoring into infection-prevention strategies. Reducing healthcare-associated infections is a systemic priority, and environmental verification can contribute to that objective when conducted consistently and interpreted correctly. Similarly, food and beverage production, research laboratories, and cleanroom monitoring functions are cultivating a more preventive mindset. In these settings, air sampling is less about passing an audit and more about understanding environmental variability, supporting root-cause investigations, and reducing the probability of costly quality events.
Active Air Sampler Market
Supply Chain and Cost Structure Considerations
Underlying all of these demand shifts is the reality of cost and supply dynamics. High-performance materials, sterilization-compatible components, and durable consumables influence both purchase price and ongoing operational expense. A filter or sampling head that offers strong retention and long shelf life can lower replacement frequency and support inventory stability, but it must be balanced against procurement budgets and sterilization workflows. Meanwhile, the ability to standardize on fewer device families can reduce validation burden, training requirements, and service complexity across sites. In practice, cost competitiveness in this market is increasingly defined by total lifecycle economics rather than unit price alone. Buyers are looking for instruments that lower validation friction, reduce consumable waste, and simplify training, because those factors translate directly into lower cost of ownership over time.
Competitive Landscape and Leading Strategies
The supplier landscape is shaped by a mix of specialized manufacturers and broader life-science players, with activity centered on cleanroom and critical-environment monitoring. Several firms have established recognizable positions by combining instrument design, application expertise, and service models that match the risk profile of regulated environments.
One recurring strategic theme is specialization with regulatory clarity. Companies that focus on microbial air sampling for cleanrooms tend to differentiate through designs that support compliance-intensive use cases. This includes devices marketed for pharmaceutical-grade environments, with emphasis on Grade A and B suitability, decontamination compatibility, and documentation support. Where these suppliers succeed, it is often because their instruments are presented as part of a monitoring solution rather than as isolated tools, with attention to sampling accuracy, contamination control, and the practical needs of validation teams.
Another theme is distribution leverage and ecosystem reach. Some players compete not only through their own device portfolios but also by acting as global distributors for established sampling platforms. This expands access to customers across pharmaceutical, biopharmaceutical, food, and medical device segments, while reducing the barrier to adoption in regions where local service and support networks matter. Distribution-oriented strategies can be particularly effective when paired with strong application support, because regulated buyers often choose suppliers based on confidence in installation, qualification, and post-deployment assistance.
A third differentiator is application breadth across sectors. While pharmaceutical production remains the most demanding and highest-profile use case, several suppliers have expanded their positioning to cover food, hospital, and medical device environments. This diversification can stabilize demand against sector-specific cycles, but it also requires the ability to tailor value propositions. A device that excels in aseptic manufacturing may need different communication and support when sold to a hospital or food facility, where the priorities are operational continuity and infection control rather than product release assurance.
Recent product activity reinforces these strategic directions. Newer iterations of portable sampling platforms have introduced features designed to reduce secondary contamination and improve process safety, reflecting the market’s sensitivity to sample integrity and operator workflow. Updated product catalogs and continued refinement of established series indicate that incumbents are focusing on incremental innovation, reliability, and compliance alignment rather than dramatic category disruption. At the same time, remote and active sampling concepts are gaining visibility because they respond to the demand for continuous monitoring and data integrity support.
Looking at the broader competitive evolution, the market appears to be moving toward selective consolidation of value rather than a race to the bottom on price. Buyers are likely to favor suppliers that can demonstrate clear regulatory fit, robust data handling, and dependable service. This environment favors incumbents with mature portfolios and application credibility, while leaving room for new entrants that can solve a specific pain point exceptionally well, such as portability with uncompromised accuracy, or connectivity that genuinely integrates with quality systems. The presence of both manufacturers and distributors also complicates direct comparison, because commercial advantage may come from either device design or market access, depending on the buyer’s procurement model.
Future Trends and Commercial Opportunities
Trend One: Connected Monitoring as a Standard Expectation
Over the next three to five years, the market is likely to treat connected, auditable monitoring as a baseline expectation rather than a premium feature. As quality systems become more digitized and audit scrutiny intensifies, devices that can support continuous or semi-continuous monitoring with reliable recordkeeping will gain preference. The commercial opportunity here is not simply in selling more connected units, but in helping buyers reduce manual documentation burden, improve trend detection, and strengthen deviation management. Suppliers that can show how instrumentation fits into broader data workflows, rather than functioning as an isolated endpoint, will be better positioned to command value.
Trend Two: Lifecycle-Driven Procurement and Standardization
Another likely trend is a shift toward procurement decisions that weigh the full monitoring lifecycle. Facilities are expected to place greater weight on decontamination compatibility, consumable stability, training simplicity, and cross-site standardization. This creates an opportunity for suppliers to articulate total cost of ownership more convincingly, especially in multi-plant or multi-site operations where device homogeneity can reduce validation and service complexity. It also creates an opening for consumables strategies that lower logistical friction while preserving sterility and retention performance. In practice, the winning offerings will be those that make ongoing monitoring easier to sustain at scale.
Trend Three: Broadening Adoption with Sector-Specific Value Narratives
Adoption is likely to broaden beyond the most traditional pharmaceutical settings, but with an important caveat: growth will be strongest where suppliers can express value in sector-specific terms. In healthcare, the narrative will center on infection-prevention support and environmental control. In food and beverage, it will focus on process hygiene and contamination prevention. In research and cleanroom monitoring, it will emphasize reproducibility, data quality, and risk reduction. The commercial opportunity lies in tailoring messaging and support packages so that the same underlying monitoring discipline can be positioned appropriately for each audience. A generic “compliance tool” narrative will be less effective than an application-specific story that connects sampling outcomes to real operational decisions.
These trends carry risks as well. If regulatory expectations diverge further across regions, procurement teams may face longer qualification timelines and more complex documentation. If connectivity features are added without clear integration benefits, buyers may perceive them as overhead rather than value. And if consumables or sterilization demands become more costly without offsetting operational savings, adoption could slow in price-sensitive segments. The market’s trajectory will depend on whether suppliers can convert technical sophistication into measurable ease, compliance confidence, and economic efficiency.
Actionable Guidance for Decision-Makers
For manufacturers and suppliers, the priority should be to reinforce credibility in the areas that regulated buyers weigh most heavily: validation alignment, decontamination compatibility, and data integrity support. Rather than competing only on feature count, companies can create advantage by reducing friction in qualification and use. That means designing instruments and consumables with lifecycle economics in mind, documenting performance in ways that facilitate audit readiness, and offering service models that match the operational tempo of critical environments. Differentiation is increasingly likely to come from how well a product simplifies compliance and daily operation, not from how many functions it can claim.
For investors, the market’s appeal lies less in rapid headline growth and more in its resilience and structural upgrade potential. Demand is anchored by ongoing cleanroom use, regulatory modernization, and expanding environmental monitoring practices across healthcare and adjacent industries. The most attractive opportunities are likely to be found where value is tied to reliability, service access, and compliance fit, because those attributes support retention and reduce the volatility associated with price-driven competition. Investors should also pay attention to where connected monitoring, consumables strategy, and application diversification intersect, since those intersections often define the next step in commercial differentiation.
For procurement and quality leaders, the strategic question is not simply which device performs best in isolation, but which solution will reduce risk and effort across the entire monitoring process. Procurement decisions should assess decontamination compatibility, documentation architecture, consumable logistics, training burden, and service responsiveness alongside sampling performance. Standardization may offer real advantages in multi-site contexts by lowering validation and maintenance complexity. At the same time, end users should resist the temptation to over-index on a single feature without considering how it affects qualification, recurring costs, and day-to-day workflow. The strongest buying decisions are those that align instrument choice with long-term operating reality rather than immediate procurement convenience.
Conclusion
The microbial air samplers market is entering a phase where growth is increasingly defined by how well products integrate with compliance discipline, operational reliability, and data-driven quality management. The sector’s steady expansion reflects durable demand, but the more important story is the shift in what buyers value: confidence in measurement, assurance in decontamination and sample integrity, and support for scalable, auditable monitoring practices. Suppliers and investors who understand these priorities will be better positioned to capture the market’s next wave of opportunity, while procurement leaders who evaluate total lifecycle economics will be better equipped to reduce risk and cost over time. The commercial winners in this space will be those who treat microbial air sampling not as a standalone instrument purchase, but as part of a broader quality-control strategy that must perform consistently under real-world conditions.
For detailed analysis of this topic, please visit the official page: Microbial Air Samplers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


